Medical Devices Cuffs Market Size, Share & Industry Analysis, By Type (Blood Pressure Cuffs, Cuffed Endotracheal Tube, Tracheostomy Tube), By End-Use (Hospitals, Clinics, Ambulatory Surgery Centers), and Regional Forecast, 2026-2034
 Download Free Sample

Medical Devices Cuffs Market Overview
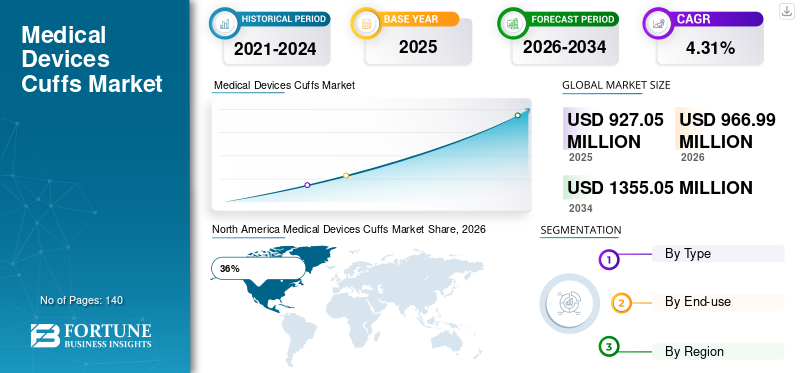
The global medical devices cuffs market size was valued at USD 927.05 million in 2025. The market is projected to grow from USD 966.99 million in 2026 to USD 1355.05 million by 2034, exhibiting a CAGR of 4.31% during the forecast period.

The medical devices cuffs market is witnessing steady expansion due to the growing use of blood pressure monitoring systems, airway management devices, and respiratory care products across healthcare facilities. Medical cuffs are critical components used in blood pressure cuffs, cuffed endotracheal tubes, and tracheostomy tubes for patient monitoring and airway protection. Increasing cases of hypertension, respiratory disorders, surgical procedures, and intensive care admissions are supporting demand. Manufacturers are focusing on disposable products, infection-control features, improved cuff materials, and patient comfort. The medical devices cuffs market Report indicates rising adoption of technologically advanced cuffs that provide accurate pressure control and reduce complications during treatment.
The United States accounts for approximately 36% of the medical devices cuffs market. Demand is supported by a large hospital network, high rates of cardiovascular disease, advanced intensive care infrastructure, and strong adoption of respiratory care technologies. Blood pressure monitoring remains a routine clinical procedure throughout healthcare settings. Growth in outpatient procedures, home healthcare services, and critical care admissions continues to increase product utilization. Medical device manufacturers are investing in advanced cuff technologies that improve patient safety and measurement accuracy. The medical devices cuffs industry analysis highlights continued procurement of disposable cuffs and infection-prevention products across healthcare facilities throughout the country.
Download Free sample to learn more about this report.
Medical Devices Cuffs Market Key Takeaways
 Global Market Size & Forecast
- 2025 Market Size: USD 927.05 Millio
- 2026 Market Size: USD 966.99 Million
- 2034 Forecast Market Size: USD 1,355.05 Million
- CAGR: 4.31% from 2026-2034
 Market Share
- The market in North America dominated with a revenue share of 36% in 2025.
- Blood pressure cuffs dominated by type with a market share of approximately 48%.
- Hospitals dominated by end use with a market share of approximately 62%.
 Key Regional Highlights
North America
North America led the market with a 36% share, supported by advanced healthcare infrastructure and strong demand for patient monitoring devices.
Europe
Europe accounted for 28% of the market, driven by established healthcare systems and increasing demand for diagnostic and respiratory care products.
Asia-Pacific
Asia-Pacific held a 25% share, supported by expanding healthcare infrastructure and rising demand for medical monitoring technologies.
U.S
The U.S. remains a key market, supported by high healthcare expenditure and strong adoption of advanced monitoring and airway management devices.
Japan
Japan accounted for approximately 22% of the Asia-Pacific market, supported by advanced healthcare infrastructure and established diagnostic and critical care capabilities.
Read More

medical devices cuffs market Latest Trends
The medical devices cuffs market trends reveal a strong transition toward disposable and single-patient-use products. Healthcare facilities are emphasizing infection prevention, resulting in higher adoption of antimicrobial cuff materials and sterile disposable solutions. Digital blood pressure systems with enhanced cuff integration are becoming common across hospitals and clinics. Manufacturers are introducing lightweight materials that improve patient comfort while maintaining measurement accuracy. Another significant trend is the increasing use of pressure-regulating cuff technologies in endotracheal and tracheostomy tubes. These products help reduce airway injuries and complications associated with prolonged ventilation. Smart monitoring systems capable of tracking cuff pressure in real time are gaining attention among critical care providers.
Download Free sample to learn more about this report.
Demand for pediatric-specific and geriatric-specific cuff designs is also increasing as healthcare providers seek customized solutions. The medical devices cuffs market research report further identifies rising adoption of home monitoring devices equipped with advanced blood pressure cuffs. Expansion of telehealth services has increased demand for easy-to-use monitoring equipment. Manufacturers are focusing on latex-free materials due to growing awareness regarding allergic reactions. Product innovations emphasizing patient comfort, durability, and clinical accuracy continue to shape competitive strategies across the global Medical Devices Cuffs Industry.
medical devices cuffs market Dynamics
DRIVER
Rising Prevalence of Cardiovascular and Respiratory Disorders
The increasing burden of hypertension, cardiovascular disease, chronic obstructive pulmonary disease, and respiratory complications remains the primary growth driver for the medical devices cuffs market. Blood pressure cuffs are essential for routine diagnosis and patient monitoring across healthcare facilities. Growing intensive care admissions have expanded the use of cuffed endotracheal tubes and tracheostomy tubes for airway management. Aging populations worldwide require frequent monitoring and respiratory support, contributing to higher product demand. Hospitals continue expanding critical care capacity, creating additional opportunities for cuff-based medical devices. The medical devices cuffs market growth is also supported by increasing awareness regarding early disease detection and continuous patient monitoring.
RESTRAINT
Pricing Pressure and Procurement Limitations
Pricing pressure from healthcare institutions remains a significant restraint within the medical devices cuffs market. Hospitals and government healthcare facilities often prioritize cost-effective procurement strategies, limiting premium product adoption. Emerging economies face budget constraints that influence purchasing decisions. Reusable alternatives continue to compete with disposable solutions in several regions. Regulatory compliance requirements also increase manufacturing expenses and certification costs. Smaller manufacturers may encounter challenges related to product approvals and quality validation. These factors can affect profitability and slow adoption of advanced cuff technologies despite increasing clinical demand across healthcare environments.
OPPORTUNITY
Expansion of Home Healthcare and Remote Monitoring
The growing home healthcare sector presents substantial opportunities for the medical devices cuffs market. Rising demand for remote patient monitoring has increased the utilization of home blood pressure devices equipped with advanced cuffs. Telemedicine adoption continues to expand among aging populations and patients with chronic diseases. Manufacturers are developing ergonomic cuff designs that improve usability and accuracy outside hospital settings. Emerging healthcare infrastructure across developing economies is creating new distribution channels. Portable monitoring equipment and connected health solutions are expected to generate additional opportunities. The medical devices cuffs market outlook remains favorable as healthcare systems increasingly support decentralized patient care models.
CHALLENGE
Product Standardization and Patient Safety Requirements
Maintaining consistent product quality across different patient groups remains a major challenge for the Medical Devices Cuffs Industry. Improper cuff sizing can affect blood pressure accuracy and clinical outcomes. Endotracheal and tracheostomy cuff pressure management requires precise control to prevent airway damage. Manufacturers must comply with evolving regulatory standards related to safety, sterilization, and material performance. Product recalls and quality concerns can affect brand reputation and market penetration. Training healthcare professionals on proper cuff selection and application remains important. The need for continuous innovation while maintaining affordability creates additional challenges for industry participants.
medical devices cuffs market Segmentation
By Type
Blood pressure cuffs account for approximately 48% market share. These products remain fundamental components of diagnostic and monitoring systems used across hospitals, clinics, and home healthcare environments. Rising hypertension prevalence continues supporting strong demand. Manufacturers are introducing digital-compatible cuffs with enhanced comfort and measurement precision. Disposable blood pressure cuffs are gaining popularity due to infection prevention initiatives. Pediatric and bariatric cuff variants are expanding product portfolio.
Cuffed endotracheal tubes represent approximately 32% market share. These products play a critical role in airway management during surgeries, emergency interventions, and intensive care treatment. Increasing ventilator utilization and critical care admissions are supporting demand growth. Advanced cuff materials help reduce leakage and improve ventilation efficiency. Healthcare providers increasingly prefer products with pressure-monitoring capabilities to minimize airway complications. Growth in surgical procedures and respiratory disease management continues strengthening this segment. The medical devices cuffs market forecast indicates sustained demand for cuffed endotracheal tubes within hospital and emergency care environments.
Tracheostomy tubes hold approximately 20% market share. Demand is primarily driven by patients requiring long-term airway support and mechanical ventilation. Rising cases of neurological disorders, respiratory diseases, and prolonged intensive care stays support utilization. Manufacturers are introducing cuff designs that improve patient comfort and reduce tissue injury. Specialized products for pediatric and adult populations continue expanding segment opportunities. Home healthcare adoption among tracheostomy patients also contributes to demand. The medical devices cuffs market research report highlights increasing clinical emphasis on effective airway management as a key factor supporting this category.
To know how our report can help streamline your business, Speak to Analyst
By End-use
Hospitals account for approximately 62% market share. These facilities remain the largest consumers of medical device cuffs due to high patient volumes, surgical activity, intensive care admissions, and diagnostic procedures. Blood pressure monitoring is routinely performed throughout hospital departments. Cuffed endotracheal and tracheostomy tubes are extensively used in operating rooms and critical care units. Healthcare institutions increasingly prioritize infection control measures, driving demand for disposable cuff products. Advanced monitoring systems and integrated respiratory care technologies further strengthen hospital procurement activities.
Clinics represent approximately 24% market share. These healthcare facilities generate consistent demand for blood pressure cuffs and patient monitoring equipment. Preventive healthcare programs and chronic disease management initiatives contribute to product utilization. Outpatient consultations frequently require routine blood pressure assessment, supporting recurring replacement demand. Compact and easy-to-use cuff systems are particularly popular among clinic operators. Growth in specialty clinics focused on cardiology and respiratory care is creating additional opportunities.
Ambulatory surgery centers hold approximately 14% market share. These facilities perform a growing number of outpatient procedures requiring anesthesia and patient monitoring. Demand for cuffed airway management products continues increasing as procedural volumes expand. Cost efficiency and rapid patient turnover encourage adoption of disposable cuffs and respiratory devices. Technological advancements in minimally invasive surgery are further supporting utilization. Ambulatory surgery centers increasingly invest in advanced monitoring systems that incorporate reliable cuff technologies.
medical devices cuffs market Regional Outlook
North America
North America Medical Devices Cuffs Market Share, 2025 (%)
To get more information on the regional analysis of this market, Download Free sample
North America accounts for approximately 36% of the medical devices cuffs market share. The region benefits from sophisticated healthcare systems, high utilization of monitoring equipment, and widespread adoption of advanced respiratory care devices. Hospitals maintain substantial inventories of blood pressure cuffs, cuffed endotracheal tubes, and tracheostomy products. Rising prevalence of hypertension and respiratory disorders continues supporting demand. Healthcare providers prioritize patient safety and infection prevention, increasing procurement of disposable cuff solutions. Strong regulatory frameworks encourage product innovation and quality improvement. Growth in outpatient procedures and home healthcare services further strengthens market expansion. The United States remains the primary revenue contributor, while Canada supports regional growth through healthcare modernization initiatives. The medical devices cuffs market Insights indicate continued investment in monitoring technologies and critical care infrastructure throughout North America.
Europe
Europe represents approximately 28% market share in the medical devices cuffs market. Demand is supported by advanced healthcare delivery systems, growing elderly populations, and increasing respiratory disease management requirements. Hospitals throughout the region continue adopting high-quality airway management devices and blood pressure monitoring solutions. Infection control regulations encourage use of disposable medical products. Healthcare providers focus on patient comfort and treatment efficiency, driving innovation in cuff technologies. Surgical procedure volumes remain high across major European countries. Public healthcare investments contribute to steady product procurement. The medical devices cuffs market Research highlights Germany, the United Kingdom, France, and Italy as major regional contributors supporting overall market development.
Germany medical devices cuffs market
Germany accounts for approximately 24% of the European medical devices cuffs market. The country benefits from a strong healthcare infrastructure and extensive hospital network. Demand for blood pressure cuffs remains consistent due to widespread cardiovascular monitoring programs. Intensive care facilities generate significant utilization of cuffed airway management devices. German healthcare providers emphasize quality standards and advanced medical technologies. Disposable cuff products are increasingly adopted to support infection prevention initiatives. The medical devices cuffs market analysis identifies Germany as a leading regional market supported by technological innovation, healthcare investment, and a growing elderly population requiring continuous monitoring and respiratory support.
United Kingdom medical devices cuffs market
The United Kingdom holds approximately 19% of the European medical devices cuffs market. National healthcare services continue investing in monitoring equipment and respiratory care technologies. Demand for cuffed endotracheal tubes and tracheostomy products remains strong within intensive care units. Blood pressure monitoring programs contribute to stable procurement of diagnostic cuffs. Infection control priorities encourage utilization of single-use products across healthcare facilities. Outpatient services and ambulatory treatment centers are expanding adoption of advanced monitoring systems. The medical devices cuffs market outlook for the United Kingdom remains positive due to ongoing healthcare modernization and increasing chronic disease management requirements.
Asia-Pacific
Asia-Pacific accounts for approximately 25% market share and represents one of the fastest expanding regions within the medical devices cuffs market. Healthcare infrastructure development across China, India, Japan, and Southeast Asia continues supporting product demand. Growing populations and increasing prevalence of hypertension, cardiovascular disease, and respiratory disorders contribute significantly to market expansion. Hospitals are expanding intensive care capacity and adopting advanced airway management technologies. Rising healthcare expenditure and improved access to medical services further strengthen growth. Local manufacturing capabilities are increasing, improving product availability and affordability. The medical devices cuffs industry analysis identifies strong opportunities associated with hospital modernization and home healthcare adoption across the region.
Japan medical devices cuffs market
Japan contributes approximately 22% of the Asia-Pacific medical devices cuffs market. The country's aging population generates substantial demand for patient monitoring and respiratory support equipment. Hospitals maintain high standards for airway management and intensive care treatment. Blood pressure monitoring remains a critical component of preventive healthcare programs. Advanced medical technology adoption supports utilization of premium cuff products. Manufacturers focus on comfort-oriented and precision-engineered designs that align with clinical requirements. The medical devices cuffs market Report highlights Japan as a technologically advanced market with strong demand for high-performance monitoring and respiratory care devices.
China medical devices cuffs market
China accounts for approximately 34% of the Asia-Pacific medical devices cuffs market. Rapid healthcare infrastructure expansion and increasing hospital capacity continue driving demand. Rising prevalence of chronic diseases has increased utilization of blood pressure monitoring equipment. Intensive care development supports adoption of cuffed endotracheal tubes and tracheostomy products. Domestic manufacturers are expanding production capabilities while improving product quality. Government healthcare initiatives encourage modernization of medical facilities. Demand from urban hospitals and regional healthcare centers continues growing. The medical devices cuffs market growth in China is supported by healthcare reforms, rising patient awareness, and increasing investment in medical technology.
Rest of World
The Rest of World region accounts for approximately 11% market share. Demand is increasing across Latin America, the Middle East, and Africa as healthcare infrastructure continues improving. Hospitals are investing in patient monitoring systems and respiratory care equipment to address growing healthcare needs. Rising awareness regarding cardiovascular disease management supports blood pressure cuff adoption. Critical care expansion is increasing utilization of cuffed airway devices. International manufacturers continue strengthening regional distribution networks to improve product accessibility. Government healthcare initiatives and private sector investments are contributing to market development. The medical devices cuffs market Opportunities within emerging economies remain significant as healthcare access expands and clinical standards continue advancing.
List of Top Medical Devices Cuffs Companies
- Medtronic plc
- Smith’s Medical (Smiths Group plc)
- Teleflex Incorporated
- ConvaTec Inc.
- Cook Medical (Cook Group Incorporated)
- Troge Medical GmbH
- Fuji Systems Corporation
- Well Lead Medical Co., Ltd.
- TRACOE medical GmbH
- Pulmodyne, Inc.
Top Two Companies with Highest Market Share
- Medtronic plc – approximately 21% market share
- Teleflex Incorporated – approximately 17% market share
Investment Analysis and Opportunities
The medical devices cuffs market is attracting investment due to rising healthcare demand and increasing focus on patient monitoring technologies. Manufacturers are allocating resources toward research and development programs that improve cuff accuracy, durability, and patient comfort. Investment activity is particularly strong within respiratory care and critical care product categories. Healthcare facilities continue modernizing equipment inventories, creating long-term procurement opportunities.
Expansion of home healthcare services represents an important investment area. Companies are developing connected monitoring solutions that integrate advanced cuff technologies with digital healthcare platforms. Emerging economies offer substantial opportunities due to improving healthcare infrastructure and expanding patient populations. Strategic partnerships between manufacturers and healthcare providers are increasing product adoption. Investments in automated manufacturing and material innovation are helping improve production efficiency. The medical devices cuffs market Opportunities are also supported by increasing demand for infection-control products, disposable devices, and specialized cuffs designed for pediatric, bariatric, and geriatric patient populations.
New Product Development
Product innovation remains a key competitive factor within the medical devices cuffs market. Manufacturers are introducing advanced blood pressure cuffs that improve measurement consistency and patient comfort. Lightweight materials and ergonomic designs are becoming standard across new product launches. Digital integration allows healthcare professionals to collect and analyze patient data more efficiently.
In airway management applications, companies are developing cuffed endotracheal tubes with enhanced pressure regulation capabilities. These innovations help reduce airway trauma and improve ventilation performance. Antimicrobial coatings and infection-control features are increasingly incorporated into product designs. Tracheostomy tubes are being redesigned to improve patient comfort during long-term use. Disposable products continue gaining popularity due to growing infection prevention requirements. The medical devices cuffs market trends indicate strong emphasis on smart monitoring systems capable of providing real-time cuff pressure information. Manufacturers are also investing in latex-free materials and environmentally responsible production methods.
Five Recent Developments (2023-2025)
- Medtronic expanded its airway management product portfolio with advanced cuffed respiratory devices designed for critical care applications during 2025.
- Teleflex introduced enhanced cuff technology focused on pressure control and infection prevention for intensive care environments during 2025.
- ConvaTec strengthened respiratory care product development initiatives by expanding specialized tracheostomy solutions during 2024.
- Well Lead Medical increased manufacturing capacity and international distribution of airway management products during 2024.
- TRACOE medical GmbH launched updated tracheostomy tube solutions emphasizing patient comfort and long-term respiratory support during 2023.
Report Coverage Of medical devices cuffs market
The medical devices cuffs market Report provides comprehensive evaluation of industry structure, competitive positioning, product categories, application trends, and regional developments. Coverage includes detailed analysis of blood pressure cuffs, cuffed endotracheal tubes, and tracheostomy tubes across multiple healthcare environments. The report examines demand drivers, restraints, opportunities, and challenges influencing market performance.
Request for Customization to gain extensive market insights.
Market segmentation analysis evaluates product utilization across hospitals, clinics, and ambulatory surgery centers. Regional assessment covers North America, Europe, Asia-Pacific, and Rest of World markets, highlighting healthcare infrastructure developments and adoption trends. Company profiling includes major manufacturers participating in respiratory care and patient monitoring segments. The report also reviews investment activity, product innovation strategies, technological advancements, and emerging opportunities influencing future industry direction. The medical devices cuffs market research report supports decision-making for manufacturers, distributors, healthcare providers, investors, and procurement organizations seeking detailed understanding of market dynamics and competitive developments.
Frequently Asked Questions
Fortune Business Insights says that the global market value stood at USD 927.05 billion in 2025 and is projected to reach USD 1,355.05 billion by 2034.
The market is expected to exhibit a CAGR of 4.31% during the forecast period of 2026-2034.
Blood pressure cuffs were the leading type segment, accounting for approximately 48% of the market, supported by their widespread use for routine blood pressure monitoring.
Key players include Medtronic plc, Smith’s Medical (Smiths Group plc), Teleflex Incorporated, ConvaTec Inc., Cook Medical, and Troge Medical GmbH.
Major trends include growing adoption of disposable and single-patient-use cuffs with antimicrobial features and increasing use of smart, pressure-monitoring technologies. North America led the market with a 36% share.


- 2021-2034
- 2025
- 2021-2024
- 140
-

(Offer valid till 15th Oct 2026)
Get 30-60 hrs Free Customization
Expand Regional and Country Coverage, Segments Analysis, Company Profiles, Competitive Benchmarking, and End-user Insights.













.webp)






-
US +1 833 909 2966 ( Toll Free )
-
Get In Touch With Us