Vehicle to Infrastructure Communication Market Size, Share & Industry Analysis, By Component (Hardware and Software), By Communication Technology (Cellular V2X, DSRC, ITS-G5, and Others), By Communication Direction (Infrastructure-to-Vehicle, Vehicle-to-Infrastructure, and Bidirectional Communication), By Application (Road-Safety Applications, Traffic-Management Applications, Environmental Applications, and Others), By Vehicle Type (Hatchback & Sedan, SUV, LCV, and HCV), and Regional Forecast, 2026–2034
 Download Free Sample

(Offer valid till 15th Oct 2026)

Vehicle to Infrastructure Communication Market Size and Future Outlook
 Listen to Audio Version
The vehicle to infrastructure communication market size was valued at USD 1.80 billion in 2025. The market is projected to grow from USD 2.14 billion in 2026 to USD 7.08 billion by 2034, exhibiting a CAGR of 16.1% during the forecast period. Asia Pacific dominated the vehicle to infrastructure communication market with a market share of 54.44% in 2025.
The market comprises technologies, hardware, software, and services that enable vehicles to exchange real-time data with road infrastructure such as traffic signals, toll systems, parking facilities, and roadside units. These V2I systems improve road safety, traffic flow, navigation, emissions management, and automated driving performance. The market growth is driven by connected vehicle adoption, smart infrastructure city investments, 5G deployment, intelligent transportation systems, and government initiatives supporting cooperative mobility ecosystems worldwide.
Major players in the market include Qualcomm Technologies, DENSO, Continental, Yunex Traffic, and Cohda Wireless, competing through advanced C-V2X and DSRC technologies, roadside and onboard communication units, 5G connectivity, interoperable platforms, real-time traffic management, cybersecurity, and safety-focused connected mobility solutions.
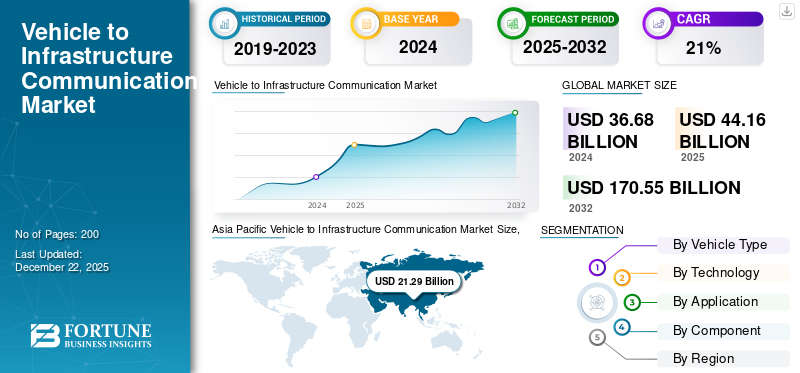
Download Free sample to learn more about this report.
VEHICLE TO INFRASTRUCTURE COMMUNICATION MARKET TRENDS
Growing Shift Toward Cellular V2X and 5G-Enabled Communication is an Emerging Market Trend
A major trend in the market is increasing shift toward cellular vehicle-to-everything and 5G-enabled communication technologies. These systems support low-latency data exchange, wider network coverage, and direct communication between vehicles and transportation infrastructure. Cellular connectivity enables traffic signals, roadside units, toll systems, and traffic management centers to deliver timely information to vehicles. The vehicle technology also supports over-the-air updates, cloud-based analytics, edge computing, and integration with autonomous driving platforms. Automakers and infrastructure providers are gradually adopting communication systems that can operate across multiple network generations and geographic regions. This shift is encouraging the development of scalable and software-driven V2I platforms. Continued improvements in network reliability, processing speed, and data capacity are expected to support broader commercial deployment.
MARKET DYNAMICS
MARKET DRIVERS
Download Free sample to learn more about this report.
Expanding Connected Vehicle Deployment to Accelerate V2I Communication Demand Boosts Market Growth
The increasing adoption of connected vehicles is a major driver of the vehicle to infrastructure communication market growth. Modern vehicles are increasingly equipped with communication modules, sensors, navigation systems, and advanced driver-assistance technologies that require continuous interaction with roadside infrastructure. V2I communication enables vehicles to receive information about traffic signals, road conditions, speed limits, congestion, tolling, and nearby hazards in real-time. Automakers, transport authorities, and technology providers are therefore investing in interoperable communication platforms that support safer and more efficient mobility. The expansion of cellular vehicle-to-everything technology, 5G networks, and roadside communication units further strengthens deployment. Growing demand for reduced travel time, improved traffic flow, and better accident prevention is expected to maintain market growth.
MARKET RESTRAINTS
High Infrastructure Investment Requirements to Restrict Large-Scale Deployment
The high cost of developing, installing, and maintaining connected roadside infrastructure remains a key restraint for the market. Large-scale implementation requires roadside units, communication gateways, traffic signal controllers, sensors, fiber networks, cloud platforms, cybersecurity systems, and supporting software. Public authorities must also upgrade existing transportation infrastructure, which can be expensive in older cities and developing economies. Limited municipal budgets, lengthy procurement processes, and uncertain investment returns may delay deployment. In addition, infrastructure must be maintained continuously to ensure reliable communication and accurate data exchange. Smaller cities and rural regions may struggle to justify investment due to lower traffic density and limited connected vehicle penetration. These financial barriers can create uneven adoption across countries and slow the establishment of fully connected transportation networks.
MARKET OPPORTUNITIES
Smart City Programs to Create Strong Infrastructure Expansion Opportunities
The rapid development of smart cities presents a significant opportunity for the market. Governments and urban authorities are investing in intelligent traffic systems, adaptive traffic signals, digital tolling, automated parking, emergency vehicle prioritization, and real-time congestion management. V2I communication can connect these systems with vehicles, allowing transportation networks to respond dynamically to changing road conditions. Integration with public transport, pedestrian monitoring, and environmental management platforms can further improve urban mobility. Emerging economies also offer considerable potential as cities modernize roads and deploy digital transportation infrastructure. Partnerships among governments, telecom operators, automakers, and technology companies can support wider implementation and reduce deployment costs. As cities seek to improve safety, reduce congestion, and lower emissions, V2I solutions will become highly important within broader smart mobility programs.
MARKET CHALLENGES
Interoperability and Cybersecurity Concerns to Challenge Market Development
Ensuring interoperability and cybersecurity across vehicles, infrastructure, communication networks, and software platforms is a major challenge for the market. Vehicles from different manufacturers must communicate reliably with roadside systems supplied by multiple technology providers. Differences in communication protocols, spectrum allocation, data formats, and regulatory requirements can complicate cross-border and large-scale deployment. Cyberattacks may also target traffic signals, roadside units, connected vehicles, or central management platforms, creating risks related to road safety and data privacy. Market participants must therefore implement encryption, identity verification, secure software updates, and continuous threat monitoring. Establishing common technical standards and certification procedures requires close cooperation among governments, automakers, telecom companies, vehicle and infrastructure operators. Failure to resolve these issues could reduce user confidence and delay adoption.
Segmentation Analysis
By Component
Expanding Roadside Infrastructure Deployment to Reinforce Hardware Segment’s Dominance
Based on component segmentation, the market is categorized into hardware and software.
The hardware segment dominates the market as large-scale deployment depends on roadside units, onboard communication modules, traffic signal controllers, sensors, antennas, and network gateways. Governments and transport agencies prioritize infrastructure installation to enable reliable, low-latency data exchange across highways and urban corridors. Growing connected vehicle penetration, smart traffic management systems projects, and upgrades to tolling and signal systems sustain hardware procurement, replacement, and maintenance demand across developed and emerging markets.
The software segment is projected to grow at a CAGR of 17.1% during the forecast period. Rising demand for real-time traffic analytics, cloud platforms, cybersecurity, over-the-air updates, and AI-based mobility management is accelerating software adoption across increasingly connected transportation ecosystems.
By Communication Technology
Broad Network Coverage and Low-Latency Connectivity to Strengthen Cellular V2X Segment Dominance
Based on communication technology segmentation, the market is categorized into cellular V2X, DSRC, ITS-G5, and others.
The cellular V2X segment dominates the market due to its broad network coverage, low-latency communication, and compatibility with existing cellular infrastructure. It supports direct interaction between vehicles, roadside units, traffic signals, and network platforms, improving collision avoidance and traffic efficiency. Expanding 5G deployment, growing connected vehicle production, and government-backed cooperative transportation programs further encourage C-V2X adoption across urban roads, highways, smart cities, and automated mobility networks.
The ITS-G5 segment is projected to expand at a CAGR of 15.4% during the forecast period. Its standardized short-range communication, strong interoperability, low-latency performance, and deployment across European cooperative intelligent transportation projects support adoption in road-safety, traffic-management, and infrastructure communication applications.
By Communication Direction
Real-Time Two-Way Data Exchange to Reinforce Bidirectional Communication Segment’s Dominance
Based on communication direction segmentation, the market is categorized into infrastructure-to-vehicle, vehicle-to-infrastructure, and bidirectional communication.
The bidirectional communication segment held the largest vehicle to infrastructure communication market share as it enables continuous two-way data exchange between vehicles and roadside infrastructure. This functionality supports hazard alerts, adaptive traffic signals, dynamic route guidance, congestion management, and emergency vehicle prioritization. Growing deployment of connected vehicles, smart intersections, C-V2X networks, and cooperative intelligent transportation systems strengthens demand for bidirectional platforms that improve road safety, traffic efficiency, and automated driving performance across urban and highway environments.
The vehicle-to-infrastructure segment is projected to grow at a CAGR of 16.9% during the forecast period. Increasing vehicle-generated data, real-time traffic reporting, automated tolling, parking communication, and road-condition monitoring are accelerating adoption across connected mobility and smart transportation networks.
By Application
Rising Demand for Collision Prevention to Sustain Road-Safety Applications Segment’s Leadership
Based on application segmentation, the market is categorized into road-safety applications, traffic-management applications, environmental applications, and others.
The road-safety applications segment dominates the market as it supports collision warnings, signal violation alerts, emergency braking assistance, pedestrian detection, and hazardous road-condition notifications. Governments and transportation agencies prioritize safety-focused deployments to reduce accidents and improve driver awareness. Growing installation of smart intersections, roadside units, connected traffic signals, and cooperative intelligent transportation systems further strengthens adoption across urban roads, highways, school zones, and accident-prone corridors.
The environmental applications segment is projected to grow at a CAGR of 17.9% during the forecast period. Rising demand for emission monitoring, eco-routing, congestion reduction, and fuel-efficient traffic signaling is encouraging V2I deployment within sustainable transportation and smart-city programs.
By Vehicle Type
To know how our report can help streamline your business, Speak to Analyst
Expanding Premium Utility Vehicle Adoption to Reinforce SUV Segment’s Dominance
Based on vehicle type segmentation, the market is categorized into hatchback & sedan, SUV, LCV, and HCV.
The SUV segment dominates the market due to strong global sales, higher integration of connected technologies, and widespread adoption of advanced driver-assistance systems. SUVs increasingly feature embedded telematics, navigation platforms, C-V2X modules, and automated safety functions that depend on infrastructure communication. Growing consumer preference for premium and electric SUVs, combined with automaker investments in connected mobility, supports extensive V2I deployment across urban roads, highways, and smart transportation networks.
The LCV segment is projected to grow at a CAGR of 16.9% during the forecast period. Expanding e-commerce, urban deliveries, fleet telematics, route optimization, automated tolling, and real-time traffic coordination are accelerating V2I adoption across commercial vehicle fleets.
Vehicle to Infrastructure Communication Market Regional Outlook
By geography, the market is categorized into Europe, North America, Asia Pacific, Middle East & Africa, and Latin America.
Asia Pacific
Asia Pacific Vehicle to Infrastructure Communication Market Size, 2025 (USD Billion)
To get more information on the regional analysis of this market, Download Free sample
Asia Pacific dominates the global market, supported by large automotive production, rapid urbanization, and expanding intelligent transportation networks. China, Japan, South Korea, and India are investing in connected roads, smart traffic signals, 5G networks, and cooperative mobility platforms. Rising vehicle density and congestion encourage governments to deploy real-time traffic-management and road-safety systems. Strong participation from automakers, telecom companies, and infrastructure providers further accelerates C-V2X adoption across highways, metropolitan corridors, industrial zones, and emerging smart cities.
China Vehicle to Infrastructure Communication Market
The China market in 2026 is estimated at around USD 0.60 billion, propelled by 5G expansion, smart-city investments, connected vehicle production, and government-backed intelligent transportation deployment.
Japan Vehicle to Infrastructure Communication Market
The Japan market in 2026 is estimated at around USD 0.34 billion, supported by advanced automotive technology, cooperative safety systems, smart highways, and automated mobility development.
Europe
Europe represents the second largest market and is projected to expand at a CAGR of 15.0% during the forecast period. Regional growth is supported by cooperative intelligent transportation programs, connected road corridors, strict road-safety objectives, and extensive ITS-G5 and C-V2X trials. Germany, France, the U.K., and Nordic countries are advancing smart intersections, digital traffic management, and cross-border communication standards. Strong regulatory coordination and collaboration among automakers, road operators, and technology suppliers support interoperable V2I deployment across urban and highway networks.
U.K. Vehicle to Infrastructure Communication Market
The U.K. market in 2026 is estimated at around USD 0.07 billion, supported by connected-road programs, safety mandates, smart intersections, and nationwide cooperative mobility deployment projects.
Germany Vehicle to Infrastructure Communication Market
The Germany market in 2026 is estimated at around USD 0.14 billion, driven by automotive innovation, C-V2X trials, digital highways, and sustained intelligent transportation infrastructure investment.
North America
North America holds the third-largest share of the global market, driven by connected vehicle penetration, highway modernization, and smart traffic-management investments. The U.S. leads regional adoption through deployments involving roadside units, automated tolling, emergency vehicle prioritization, and signal-phase communication. Canada also supports intelligent corridor development and cooperative mobility trials. Expanding 5G coverage, growing C-V2X compatibility, and collaboration among transportation agencies, automakers, and telecom operators are strengthening regional implementation across cities, highways, logistics routes, and public transportation networks.
U.S. Vehicle to Infrastructure Communication Market
The U.S. market in 2026 is estimated at around USD 0.33 billion, supported by federal V2X programs, connected intersections, highway modernization, and strong domestic technology ecosystems.
Middle East & Africa
The Middle East & Africa market is expanding as governments invest in smart cities, digital road networks, and intelligent transportation infrastructure. The UAE, Saudi Arabia, and selected African urban centers are deploying connected traffic signals, automated tolling, smart parking, and real-time mobility platforms. Large infrastructure projects and increasing adoption of connected vehicles create opportunities for V2I communication providers. However, growth remains concentrated in major cities due to uneven digital infrastructure, funding limitations, and lower connected vehicle penetration across several developing markets.
UAE Vehicle to Infrastructure Communication Market
The UAE market in 2026 is estimated at around USD 0.02 billion, driven by smart-city programs, connected-road infrastructure, autonomous vehicle trials, and advanced digital traffic management.
Latin America
Latin America is expected to register steady growth as major cities address congestion, road accidents, and inefficient traffic management. Brazil, Mexico, Chile, and Colombia are gradually adopting smart traffic signals, digital tolling, fleet connectivity, and integrated mobility platforms. Growing urban populations and expanding logistics activity increases demand for real-time vehicle and infrastructure communication. Market development is also encouraged by public-private transportation projects.
Brazil Vehicle to Infrastructure Communication Market
The Brazil market in 2026 is estimated at around USD 0.04 billion, supported by urban traffic modernization, digital tolling, fleet connectivity, and nationwide road-safety improvement initiatives.
COMPETITIVE LANDSCAPE
Key Industry Players
Technology Innovation, Strategic Partnerships, and Interoperability Shape Market Competition
Competition in the global market is shaped by automotive technology suppliers, semiconductor companies, traffic-management specialists, and communication platform providers. Leading participants such as Qualcomm Technologies, DENSO, Continental, Yunex Traffic, and Cohda Wireless compete through C-V2X capabilities, roadside units, onboard communication modules, cloud platforms, and cybersecurity solutions. These companies focus on low-latency connectivity, interoperability, scalable deployment, and compatibility with smart-city infrastructure. Strategic partnerships with automakers, telecom operators, governments, and road authorities help vendors secure pilot projects, standards participation, and long-term infrastructure contracts across major regional markets and connected highway modernization programs.
Market competition is increasingly influenced by software differentiation, data analytics, artificial intelligence, over-the-air updates, and secure network management. Established automotive suppliers benefit from OEM relationships, engineering expertise, and global manufacturing networks, while specialized V2X companies compete through flexible platforms and rapid innovation. Participants are expanding regional presence through demonstrations, public-sector tenders, technology licensing, and joint development agreements. As deployment scales, competitive advantage will depend on meeting regional standards, protecting vehicle and infrastructure data, reducing installation costs, and supporting both legacy DSRC systems and emerging 5G-based communication architectures across diverse markets.
LIST OF KEY VEHICLE TO INFRASTRUCTURE COMMUNICATION COMPANIES PROFILED
- DENSO Corporation (Japan)
- Qualcomm Technologies, Inc., (U.S.)
- Continental AG (Germany)
- Yunex Traffic (Germany)
- Cohda Wireless (Australia)
- Commsignia (U.S.)
- Kapsch TrafficCom AG (Austria)
- NXP Semiconductors (Netherlands)
- Siemens (Germany)
- Iteris, Inc. (U.S.)
KEY INDUSTRY DEVELOPMENTS
- April 2026: DENSO launched the upgraded MobiQ RSU-5941 roadside unit, enabling real-time wireless communication among vehicles, road infrastructure, and traffic networks. The deployment-ready system supports traffic signals, electronic signs, pedestrian alerts, transit priority, freight priority, and emergency vehicle pre-emption.
- January 2026: Qualcomm and Hyundai Mobis demonstrated a V2X safety solution detecting non-line-of-sight hazards, including obstructed vehicles and two-wheelers. The technology enables earlier warnings, soft braking at higher speeds, and emergency braking where traditional onboard sensors face visibility limitations.
- January 2026: Cohda Wireless announced that U.S.-supplied MK6 roadside and onboard units aligned with Build America, Buy America requirements. Domestic assembly through Cohda Wireless America supports federally funded connected-transportation projects and simplifies procurement for agencies, integrators, and infrastructure partners.
- August 2025: DENSO presented its MobiQ V2X roadside and onboard units at ITS World Congress. The systems support signal priority, traveller information, vehicle-to-vehicle, and vehicle-to-infrastructure applications, helping transportation agencies improve safety, traffic flow, fuel efficiency, and connected fleet operations.
- August 2025: Commsignia launched the next generation of Commsignia Central, enabling agencies to configure, monitor, and manage multi-vendor roadside units, sensors, and ITS devices through one platform. The solution improves interoperability, remote diagnostics, coverage, and real-time V2X message delivery.
- August 2025: INTEGRITY Security Services, Danlaw, and Cohda Wireless formed a partnership to develop secure, interoperable V2X communications. Danlaw RouteLink roadside units integrated ISS TrafficAuth security libraries, supporting standards-compliant connectivity across vehicles, traffic infrastructure, emergency services, and mobility systems.
- June 2025: Qualcomm completed its acquisition of Autotalks, adding production-ready V2X chipsets and solutions to the Snapdragon Digital Chassis portfolio. The combined offering supports DSRC, LTE-V2X, and 5G-V2X deployments across vehicles, roadside infrastructure, two-wheelers, and automated driving applications globally.
REPORT COVERAGE
The global vehicle to infrastructure communication market analysis provides an in-depth study of market size and forecast by all the market segments included in the report. It includes details on the market dynamics and market trends expected to drive the market in the forecast period. It offers information on the technological advancements, new product launches, key industry developments, and details on partnerships, mergers & acquisitions. The market research report also encompasses a detailed competitive landscape, including market share and profiles of key operating players.
Request for Customization to gain extensive market insights.
Report Scope & Segmentation
| ATTRIBUTE | DETAILS |
| Study Period | 2021-2034 |
| Base Year | 2025 |
| Estimated Year | 2026 |
| Forecast Period | 2026-2034 |
| Historical Period | 2021-2024 |
| Growth Rate | CAGR of 16.1% from 2026-2034 |
| Unit | Value (USD Billion) |
| Segmentation | By Component, ByCommunication Direction, By Application, By Vehicle Type, By Communication Technology, and By Region |
| By Component |
|
| By Communication Technology |
|
| By Communication Direction |
|
| By Application |
|
| By Vehicle Type |
|
| By Region |
|
Frequently Asked Questions
Fortune Business Insights says that the global market value stood at USD 1.80 billion in 2025 and is projected to reach USD 7.08 billion by 2034.
In 2025, Asia Pacific market value stood at USD 0.98 billion.
The market is expected to grow at a CAGR of 16.1% during the forecast period of 2026-2034
By vehicle type, SUV segment led the market.
Expanding connected vehicle deployment to accelerate V2I communication demand.
Asia Pacific held the largest share in the market.


- 2021-2034
- 2025
- 2021-2024
- 150
-
(Offer valid till 15th Oct 2026)
Get 30-60 hrs Free Customization
Expand Regional and Country Coverage, Segments Analysis, Company Profiles, Competitive Benchmarking, and End-user Insights.




















Related Reports
-
US +1 833 909 2966 ( Toll Free )
-
Get In Touch With Us