Ropivacaine Market Size, Share & Industry Analysis, By Product Type (Branded and Generic), By Therapy Type (Surgical Anesthesia, Acute Pain Management, and Others), By Age Group (Pediatric and Adults), By Application (Orthopedic Surgery, General & Abdominal Surgery, Obstetric & Gynecologic Procedures, and Cardiothoracic Surgery), By Route of Administration (Epidural, Perineural / Peripheral Nerve Block, and Local Infiltration), By Distribution Channel (Hospital Pharmacies, Drug Stores and Retail Pharmacies, Specialty Pharmacies, and Online Pharmacies), and Regional Forecast, 2026-2034
 Download Free Sample

Ropivacaine Market Size and Future Outlook
 Listen to Audio Version
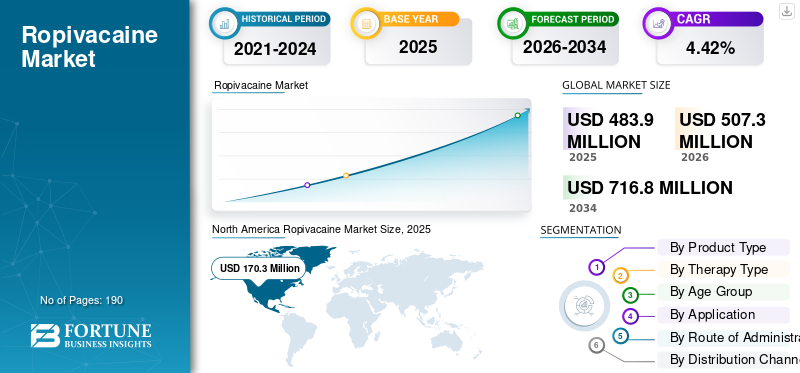
The ropivacaine market size was valued at USD 483.9 million in 2025. The market is projected to grow from USD 507.3 million in 2026 to USD 716.8 million by 2034, exhibiting a CAGR of 4.42% during the forecast period. North America dominated the ropivacaine market with a market share of 35.19% in 2025.
The market is supported by increasing use of regional anesthesia and targeted pain-management techniques across hospitals and surgical facilities. Ropivacaine is widely administered for epidural anesthesia, major peripheral nerve blocks, and local infiltration during surgical procedures, including cesarean sections, as well as for postoperative and labor-related pain management. The market is also witnessing increasing competition from generic injectable manufacturers, which is improving product availability and supporting cost-effective hospital procurement. Expanding surgical activity, wider adoption of regional anesthesia, and the continued introduction of generic formulations are expected to support market growth.
- For instance, in October 2025, Glenmark Pharmaceuticals launched Ropivacaine Hydrochloride Injection USP in 40 mg/20 mL, 150 mg/30 mL and 200 mg/20 mL single-dose vials in the U.S. The development highlights the growing focus of pharmaceutical manufacturers on introducing affordable generic ropivacaine formulations and strengthening product availability across hospital and surgical-care settings.
Furthermore, key players, such as Fresenius Kabi AG, Sandoz Group AG, Aspen Holdings, and Baxter, are participating in strategic collaborations and acquisitions, as well as regulatory approval and investment initiatives to expand market presence.
Download Free sample to learn more about this report.
ROPIVACAINE MARKET TRENDS
Growing Adoption of Regional Anesthesia for Surgical and Postoperative Pain Management is a Key Market Trend
Healthcare providers are increasingly incorporating regional anesthesia into perioperative pain-management protocols to provide targeted pain relief and reduce dependence on systemic opioids. Ropivacaine is used in epidural anesthesia, major peripheral nerve blocks, and local infiltration, making it suitable for anesthesia and acute pain management across several surgical procedures. The growing use of ultrasound-guided nerve blocks and procedure-specific pain protocols is also improving the precision and clinical acceptance of regional anesthesia. This trend is expected to increase the utilization of conventional and long-acting ropivacaine formulations across hospitals and surgical centers.
- For instance, in December 2025, Nanjing Delova Biotech announced positive results from two Phase III trials of QP-6211, its investigational long-acting ropivacaine injection, for postoperative pain following hemorrhoidectomy and bunionectomy. The formulation provided sustained pain relief for up to 72 hours and reduced opioid consumption compared to conventional ropivacaine and placebo.
MARKET DYNAMICS
MARKET DRIVERS
Download Free sample to learn more about this report.
Rising Surgical Procedure Volumes and Aging-Related Orthopedic Demand to Drive Market Growth
The increasing number of surgical procedures, particularly orthopedic interventions such as hip and knee replacements, is anticipated to support the ropivacaine market growth. Older adults are more likely to develop osteoarthritis, fractures, and other degenerative musculoskeletal conditions that may require surgical treatment. Ropivacaine is being increasingly used in epidural anesthesia, peripheral nerve blocks, and local infiltration. As hospitals expand surgical capacity and adopt multimodal pain-management protocols, the consumption of ropivacaine across operating rooms and postoperative care settings is expected to increase.
- For instance, the American Joint Replacement Registry’s 2025 report captured more than 4.6 million hip and knee procedures performed between 2012 and 2024, representing an 8.8% increase. Such increasing volumes of surgical procedures are expected to elevate demand.
|
Rank |
Market Driver |
Expected Impact on Market Growth |
CAGR Contribution (2026-2034) |
Impact: 2026-2028 |
Impact: 2029-2031 |
Impact: 2032-2034 |
|
1 |
A large diagnosed and self-treating population |
High |
2.05% |
High |
High |
High |
|
2 |
Longer and less predictable pollen exposure. |
High |
1.65% |
Medium |
High |
High |
|
3 |
Broad OTC access and consumer self-care |
High |
1.35% |
High |
High |
Medium |
|
4 |
Expansion of differentiated intranasal combinations |
Medium-High |
1.20% |
Medium |
High |
High |
|
5 |
Growing clinical and payer recognition of allergen immunotherapy |
Medium |
1.25% |
Medium |
Medium |
High |
|
6 |
Others |
Low |
0.72% |
Low |
Low |
Low |
|
Total Gross Growth Contribution |
8.22% |
MARKET RESTRAINTS
Intense Generic Price Erosion and Tender-Based Procurement to Compress Manufacturer Margins
The increasing availability of generic ropivacaine products is intensifying price competition among injectable manufacturers. Hospitals and public healthcare systems frequently procure mature injectable drugs through large-volume tenders, where suppliers are required to offer substantial price discounts to secure contracts. However, sterile injectable manufacturing continues to involve significant costs related to aseptic production, regulatory compliance, quality testing and supply-chain maintenance. Continued price reductions can therefore compress manufacturer margins and reduce the commercial attractiveness of maintaining or expanding ropivacaine production.
- For instance, in November 2025, Viatris and Medicines for Europe published an independent study showing that the average prices of selected off-patent medicines declined while manufacturing costs increased substantially. The study reported that average prices fell by 10.4% between 2020 and 2024, while producer, labor and energy costs rose sharply.
|
Rank |
Market Restraint |
Expected Impact on Market Growth |
Negative CAGR Contribution (2026-2034) |
Impact: 2026-2028 |
Impact: 2029-2031 |
Impact: 2032-2034 |
|
1 |
Genericization and manufacturer-price compression |
High |
1.5% |
High |
High |
Medium |
|
2 |
Incomplete adherence and incorrect nasal-spray technique |
Medium-High |
1.0% |
High |
Medium |
Medium |
|
3 |
Safety, labeling, and age restrictions |
Medium |
0.85% |
Medium |
Medium |
Low |
|
4 |
Others |
Low |
0.45% |
Low |
Low |
Low |
|
Total Market Reduction |
3.8% |
MARKET OPPORTUNITIES
Expansion of Ready-to-Use and Closed Delivery Formats to Create New Revenue Opportunities
The development of ready-to-use bags, prefilled infusion systems and closed delivery formats offers a significant growth opportunity for ropivacaine manufacturers. Conventional vial-based products may require dose preparation, dilution, labelling and transfer before administration, increasing the workload on hospital pharmacy and clinical staff. Manufacturer-prepared formats can reduce preparation steps, support standardized dosing and lower the risks of medication errors, contamination and drug wastage. These advantages are particularly valuable in operating rooms, postoperative units, and ambulatory surgical centres, where rapid and reliable administration is important. Therefore, investment in convenient and closed ropivacaine delivery systems could expand product adoption and create higher-value market segments.
- For instance, in May 2024, Bowmed Ibisqus launched a ready-to-use ropivacaine infusion bag containing 400 mg/200 mL of ropivacaine at a concentration of 2 mg/mL. The product was introduced as part of the company’s anesthesia portfolio and is supplied in packs of five.
MARKET CHALLENGES
Risk of Local Anesthetic Systemic Toxicity and Administration Errors to Challenge Market Expansion
The risk of local anesthetic systemic toxicity and dosing-related errors represents an important challenge for the market. Excessive dosing, unintended intravascular injection, or incorrect concentration calculations can expose patients to serious neurological and cardiovascular complications. These safety requirements increase the need for trained anesthesia professionals, standardized hospital protocols, emergency preparedness, and close patient observation. Concerns are greater in smaller healthcare facilities that have limited regional-anesthesia expertise or inadequate access to toxicity-management resources. Consequently, the clinical risks and operational safeguards associated with ropivacaine may restrict its wider adoption across lower-resource surgical settings.
- For instance, in October 2024, the Royal College of Anaesthetists responded to a coroner’s Prevention of Future Deaths report concerning a patient who sustained irreversible brain injury and subsequently died after excessive ropivacaine was administered during hip replacement surgery. The coroner raised concerns regarding unclear responsibility for checking the dose and insufficient safeguards against excessive administration. The incident highlighted how calculation errors, inadequate communication, and unclear administration protocols can result in severe outcomes and reinforce the need for stricter safety controls when using ropivacaine.
Segmentation Analysis
By Product Type
Broad Availability and Cost-Effective Hospital Procurement Supported Generic Segment Leadership
Based on the product type, the market is categorized into branded and generic.
The generic segment accounted for the larger ropivacaine market share in 2025. The dominance of the segment can be attributed to the availability of multiple therapeutically equivalent products across different concentrations. Ropivacaine is a mature injectable drug and is preferred as hospitals generally prioritize products that meet required quality standards while lowering acquisition costs. Generic formulations are also widely included in institutional tenders and wholesaler contracts, enabling manufacturers to supply large volumes to hospitals and surgical facilities. Therefore, wider supplier participation, competitive pricing, and established clinical use resulted in the segment’s leading market share.
- For instance, in November 2024, Meitheal Pharmaceuticals launched Ropivacaine Hydrochloride Injection USP in three single-dose vial presentations in the U.S. The company subsequently listed several AP-rated strengths equivalent to Naropin, demonstrating the continued expansion of generic ropivacaine availability across institutional distribution channels.
The branded segment is expected to grow at a CAGR of 1.61% over the forecast period.
To know how our report can help streamline your business, Speak to Analyst
By Therapy Type
Broad Use Across Multiple Operative Procedures Led to Surgical Anesthesia Segment Dominance
Based on therapy type, the market is segmented into surgical anesthesia, acute pain management, and others.
In 2025, the surgical anesthesia segment captured the largest share of the market. Ropivacaine is used to produce regional or local anesthesia during a broad range of operative procedures. It can be administered through epidural block, major peripheral nerve block, and local infiltration, allowing anesthesiologists to use the drug across obstetric, orthopedic, abdominal, and other surgeries. Each eligible surgical procedure creates a direct requirement for an anesthetic dose, resulting in consistent product consumption across operating rooms. Consequently, its wide procedural applicability and established place in regional-anesthesia protocols supported the segment’s dominant position.
- For instance, in January 2024, Amneal expanded its portfolio with AP-rated Ropivacaine Hydrochloride Injection USP in multiple single-dose infusion-bag strengths. The accompanying prescribing information specifically included epidural block for surgery, major nerve block, and local infiltration under surgical anesthesia, highlighting the broad operative use of the product.
The others segment is projected to grow at a 5.87% CAGR during the forecast period.
By Age Group
Higher Prevalance of Diagnosed Adult Population Propelled Segment Dominance
Based on age group, the market is segmented into pediatric and adult.
The adult segment dominated the market due to the larger number of patients. Surgical and pain-management procedures are more commonly performed among adults. Additionally, several major product labels specifically indicate ropivacaine for adults. This broader labeled population and higher procedure burden resulted in greater consumption among adults.
- For instance, in April 2024, Baxter launched ready-to-use Ropivacaine Hydrochloride Injection USP bags in 200 mg/100 mL and 400 mg/200 mL strengths in the U.S. The product was indicated in adults for local or regional anesthesia during surgery and for acute pain management, reinforcing the commercial focus on the adult patient population.
The pediatric segment is expected to rise at a 5.30% CAGR during the forecast period.
By Application
Orthopedic and Musculoskeletal Surgery Segment Dominated Due to High Joint-Replacement and Musculoskeletal Procedure Volumes
Based on the application, the market is segmented into orthopedic and musculoskeletal surgery, general and abdominal surgery, obstetric and gynecologic procedures, cardiothoracic surgery, urologic surgery, plastic, reconstructive and breast surgery, head, neck and maxillofacial surgery, trauma and emergency procedures, and others.
The orthopedic and musculoskeletal surgery segment dominated the market due to the large and increasing volume of joint-replacement, fracture-repair, ligament-reconstruction, and other bone and soft-tissue procedures. These surgeries can produce considerable postoperative pain, encouraging the use of peripheral nerve blocks, epidural anesthesia, and local infiltration as part of multimodal pain-management protocols. Aging populations and the rising burden of degenerative joint conditions are further increasing the number of patients requiring orthopedic intervention. As a result, the combination of high procedure volumes and extensive regional-anesthesia use generated significant ropivacaine consumption in this application.
- For instance, in December 2025, the Government of Ontario announced an investment of approximately USD 125.0 million to support 20,000 additional orthopedic surgeries annually across community surgical and diagnostic centres. The initiative included hip and knee replacements and illustrates the continuing expansion of orthopedic surgical capacity, which creates additional demand for regional anesthetics such as ropivacaine.
The plastic, reconstructive and breast surgery segment is projected to grow at a CAGR of 5.02% over the forecast period.
By Route of Administration
Established Use in Surgery, Caesarean Sections and Continuous Analgesia Drives Epidural Segment Dominance
Based on the route of administration, the market is segmented into epidural, perineural/peripheral nerve block, local infiltration, and others.
The epidural segment dominated the market as this route supports both surgical anesthesia and extended acute pain management. Largely used during major surgical procedures, epidural ropivacaine can subsequently be administered through continuous infusion or intermittent boluses for postoperative or labour-related pain. This dual application creates higher utilization per patient than routes limited to a single administration. Epidural catheters also allow clinicians to adjust dosing according to the duration of surgery and the patient’s postoperative requirements. Therefore, its established use across operating rooms, maternity units and postoperative care settings supported the route’s leading market position.
- For instance, in December 2020, Hikma Pharmaceuticals launched Ropivacaine Hydrochloride Injection USP in the U.S. for anesthesia and acute pain management. The company highlighted its use in epidural anesthesia for caesarean sections and in continuous or intermittent epidural administration for postoperative and labour pain, demonstrating the route’s broad clinical role.
The others segment is projected to grow at a CAGR of 5.17% during the forecast period.
By Distribution Channel
Centralized Surgical Procurement and Requirement for Controlled Administration Propelled Hospital Pharmacy Leadership
Based on the distribution channel, the market is segmented into hospital pharmacies, drug stores & retail pharmacies, specialty pharmacies, and online pharmacies.
In 2025, hospital pharmacies dominated the distribution channel. Extensive use of ropivacaine during surgery, labour, and inpatient or procedure-based pain management leads to high demand in hospitals. Hospital pharmacies procure multiple concentrations and formats in bulk and supply them directly to operating rooms, anesthesia departments, and postoperative units. Institutional contracts and historical-demand allocations also make hospital procurement more structured than retail or online distribution. Consequently, the hospital-based nature of administration and centralized inventory management supported the segment’s dominant market share.
- For instance, in October 2024, Fresenius Kabi Canada announced the return of its Ropivacaine Hydrochloride Injection USP 5 mg/mL ampoule to distribution centres following a supply interruption. The product was placed on allocation, with contract customers receiving quantities based on their historical monthly demand, highlighting the importance of institutional contracts and centralized supply management in ropivacaine distribution.
The specialty pharmacies segment is projected to grow at a CAGR of 7.83% over the forecast period.
Ropivacaine Market Regional Outlook
By geography, the market is categorized into Europe, North America, Asia Pacific, Latin America, and the Middle East & Africa.
North America
North America Ropivacaine Market Size, 2025 (USD Million)
To get more information on the regional analysis of this market, Download Free sample
North America was valued at USD 163.0 million in 2024 and maintained its leading position in 2025 at USD 170.3 million. High surgical volumes, broad use of regional anesthesia, and strong hospital procurement of generic and ready-to-use ropivacaine formats support market growth.
U.S. Ropivacaine Market
Given North America's substantial contribution and the U.S. dominance in the region, the U.S. market is estimated at around USD 162.9 million in 2026, accounting for roughly 32.12% of the global market.
Europe
Europe is projected to grow at 3.25% CAGR over the forecast period, the second-highest among all regions, and reach a valuation of USD 135.5 million by 2026. The market is expanding in Europe due to an aging population, rising joint-replacement procedures, and increasing adoption of opioid-sparing perioperative pain protocols.
U.K. Ropivacaine Market
The U.K. market is estimated at USD 22.2 million in 2026, accounting for roughly 4.38% of the global market.
Germany Ropivacaine Market
Germany's market is projected to reach approximately USD 29.2 million in 2026, equivalent to around 5.75% of the global market.
Asia Pacific
Asia Pacific accounted for the third largest share in the market in 2025 and is estimated to reach USD 133.0 million in 2026. Expanding hospital infrastructure, improving access to surgical and anesthesia care, and growing procedure volumes are expected to drive regional growth. Wider availability of affordable generic injections also supports adoption across emerging economies.
Japan Ropivacaine Market
The Japanese market in 2026 is estimated at around USD 28.1 million, accounting for approximately 5.54% of the global market.
China's Ropivacaine Market
China's market is projected to be among the largest worldwide, with 2026 revenues estimated at around USD 50.6 million, accounting for approximately 9.97% of global sales.
India Ropivacaine Market
The Indian market is estimated at around USD 20.9 million in 2026, accounting for roughly 4.13% of global revenue.
Latin America and the Middle East & Africa
The Latin America is expected to witness substantial growth in this market during the forecast period and reach a valuation of USD 31.7 million in 2026. Healthcare investment and regional initiatives improve emergency, critical, and operative care and are expanding surgical capacity. As hospitals modernize and access to procedures improves, demand for cost-effective anesthetics such as generic ropivacaine is expected to rise. In the Middle East & Africa, the GCC is set to reach USD 13.6 million in 2026.
South Africa Ropivacaine Market
The South African market is projected to reach approximately USD 6.2 million by 2026, accounting for roughly 1.21% of global revenue.
COMPETITIVE LANDSCAPE
Key Industry Players
Generic Portfolio Expansion, Ready-to-Use Formats, and Supply Reliability to Intensify Market Competition
The presence of established injectable-drug manufacturers and specialized generic pharmaceutical companies characterizes the ropivacaine market. Competition is increasing as hospital pharmacies seek products that combine competitive pricing with convenient preparation, dependable availability and consistent quality. Large manufacturers benefit from established sterile-production facilities, broad distribution networks and institutional purchasing relationships. Based on current product availability, formulation breadth, manufacturing quality and supply continuity are becoming important competitive differentiators. Manufacturers with diversified sterile-injectable portfolios, reliable regulatory compliance and the ability to maintain continuous hospital supply are expected to retain stronger competitive positions. At the same time, new generic entrants are likely to increase pricing pressure in established markets.
- For instance, in October 2025, Glenmark Pharmaceuticals Inc., U.S. launched Ropivacaine Hydrochloride Injection USP, 40 mg/20 mL (2mg/mL), 150 mg/30 mL (5 mg/mL), and 200 mg/20 mL (10 mg/mL) Single-Dose Vials. These are bioequivalent and therapeutically equivalent to the reference listed drug, Naropin Injection.
Companies actively operating in the market include Fresenius Kabi, Baxter International Inc., Amneal Pharmaceuticals, Hikma Pharmaceuticals, Glenmark Pharmaceuticals, Meitheal Pharmaceuticals, Eugia US, Gland Pharma, Anthea Pharma, NorthStar Rx and other regional injectable manufacturers. These companies compete through generic launches, branded and therapeutically equivalent products, ready-to-use bags, concentration breadth, hospital-tender participation and geographic distribution.
LIST OF KEY ROPIVACAINE COMPANIES PROFILED
- Fresenius Kabi AG (Germany)
- Sandoz Group AG (Switzerland)
- Aspen Holdings (South Africa)
- Baxter (U.S.)
- Braun SE (Germany)
- Aurobindo Pharma Limited (India)
- Hikma Pharmaceuticals PLC (U.K.)
- Sagent Pharmaceuticals (U.S.)
- Amneal Pharmaceuticals, Inc. (U.S.)
- Sintetica SA (Switzerland)
- Meitheal Pharmaceuticals, Inc. (U.S.)
KEY INDUSTRY DEVELOPMENTS
- July 2026: Sino Biopharmaceutical Limited submitted a new drug application for ropivacaine hydrochloride sustained-release solution, a national Category new drug independently developed by Beijing Tide Pharmaceutical Co., Ltd., to China’s National Medical Products Administration, for postoperative long-acting analgesia in adults.
- June 2026: PRF Technologies Ltd. reported results from its previously reported preclinical study directly comparing its lead product candidate, PRF-110, to ZYNRELEF. PRF-110 is an extended-release formulation of ropivacaine designed to be deposited directly into the surgical wound bed prior to closure. The product candidate is being developed to provide prolonged local analgesia following surgery through a single administration at the surgical site. Such a product is designed to reduce the use of opiates for post-surgical pain.
- February 2026: CSPC Pharmaceutical Group Limited announced that its Ropivacaine Long-acting Injection (SYH9089 Injection) received clinical trial approval from China’s National Medical Products Administration for the development of an ultra-long-acting postoperative analgesic with a potential duration of up to one week.
- November 2025: Pacira BioSciences, Inc. collaborated with AmacaThera for the development and commercialization of AMT-143, a novel long-acting formulation of the non-opioid analgesic ropivacaine for postsurgical pain control.
REPORT COVERAGE
The ropivacaine market report provides a detailed assessment of all market segments, highlighting the key drivers, trends, opportunities, restraints, and challenges influencing industry growth. It includes a market analysis covering its various applications. The study further assesses generic product launches, regulatory approvals, pricing pressure, supply availability, and competitive strategies adopted by manufacturers. It also examines surgical procedure volumes, adoption of regional anesthesia, hospital procurement patterns, product-quality requirements, and the growing use of convenient delivery formats. The report further highlights regional growth patterns across North America, Europe, Asia Pacific, Latin America, and Middle East & Africa, along with the major factors supporting the adoption in each region.
Request for Customization to gain extensive market insights.
Report Scope & Segmentation
| ATTRIBUTE | DETAILS |
| Study Period | 2021-2034 |
| Base Year | 2025 |
| Estimated Year | 2026 |
| Forecast Period | 2026-2034 |
| Historical Period | 2021-2024 |
| Growth Rate | CAGR of 4.42% from 2026 to 2034 |
| Unit | Value (USD Million) |
| Segmentation | By Product Type, Therapy Type, Age Group, Application, Route of Administration, Distribution Channel, and Region |
| By Product Type |
|
| By Therapy Type |
|
| By Age Group |
|
| By Application |
|
| By Route of Administration |
|
| By Distribution Channel |
|
| By Region |
|
Research Methodology:
1. Bottom Up Approaches
Approach 1: Revenues and Market Share of Major Ropivacaine Players
- Collection of ropivacaine-related revenue indicators from annual reports, regulatory filings, investor presentations, company websites, product catalogs, and prescribing information.
- Identification of branded and generic ropivacaine products marketed by companies such as Fresenius Kabi, Sandoz, Aspen Pharmacare, Baxter International, B. Braun, Aurobindo Pharma/Eugia, Hikma Pharmaceuticals, Sagent Pharmaceuticals, Amneal Pharmaceuticals, and Sintetica.
- Mapping of products by concentration, pack size, vial, ampoule, infusion bag, ready-to-use format, marketing authorization holder, and geographic availability.
- Estimation of company-level sales using product volumes, manufacturer selling prices, hospital penetration, tender participation, distribution coverage, and regional presence.
- Validation of estimated company revenues against hospital procurement volumes, product registrations, surgical procedure demand, shortages, and competitive activity.
- Aggregation of individual company revenues and estimation of unorganized or smaller regional suppliers to arrive at the global market.
Approach 2: Surgical Procedure Volume and Ropivacaine Utilization Analysis
- Estimation of country-level volumes for orthopedic, abdominal, obstetric, gynecologic, cardiothoracic, urologic, reconstructive, trauma, and other eligible surgical procedures.
- Estimation of the proportion of procedures using epidural anesthesia, peripheral nerve blocks, local infiltration, or other regional anesthesia techniques.
- Assessment of ropivacaine adoption relative to competing local anesthetics such as bupivacaine, levobupivacaine, lidocaine, and mepivacaine.
- Evaluation of utilization across surgical anesthesia, postoperative pain management, labor analgesia, and other acute pain applications.
- Estimation of average dosage, concentration, product units, infusion volume, and wastage per procedure.
- Calculation of market value using eligible procedures, regional anesthesia adoption, ropivacaine penetration, units consumed per procedure, and manufacturer selling prices.
- Country-level estimates are summated to calculate regional markets, which are subsequently aggregated to derive the global market.
Approach 3: Product Sales and Price-Volume Analysis
- Identification of all commercially available ropivacaine products from FDA, DailyMed, EMA, TGA, PMDA, NMPA, CDSCO, national drug registries, and company product catalogs.
- Mapping of each product by manufacturer, marketing authorization holder, brand or generic status, concentration, pack size, vial, ampoule, or infusion-bag presentation.
- Coverage of products marketed by companies such as Fresenius Kabi, Baxter, B. Braun, Hikma Pharmaceuticals, Aurobindo/Eugia, Sagent Pharmaceuticals, Amneal Pharmaceuticals, Meitheal Pharmaceuticals, Glenmark Pharmaceuticals, and Sintetica.
- Estimation of annual product units sold using tender quantities, distributor sales, product availability, import-export records, supply contracts, regulatory launch dates, and company disclosures.
- Collection of pack-level prices from public tenders, government procurement portals, reimbursement lists, hospital price schedules, and manufacturer or distributor catalogs.
- Calculation of market value for each product using annual units sold multiplied by the corresponding manufacturer-level price.
- Adjustment for inventory changes, safety stock, product wastage, shortages, recalls, discontinuations, and differences between sell-in and actual utilization was conducted.
2. Top Down Approaches
Approach 1: Parent Injectable Local Anesthetics Market Analysis
- Assessment of the broader hospital anesthesia and injectable local anesthetics market across the countries included in the study.
- Exclusion of topical, dental, dermatological, ophthalmic, and other anesthetic applications that do not directly represent the ropivacaine market.
- Estimation of the injectable local anesthetics market attributable to epidural anesthesia, nerve blocks, surgical infiltration, postoperative analgesia, and obstetric analgesia.
- Calculation of the ropivacaine share based on clinical adoption, hospital formulary inclusion, regulatory registrations, generic availability, and competitive positioning.
- Comparison of ropivacaine penetration against bupivacaine, levobupivacaine, lidocaine, and other injectable local anesthetics.
- Regional allocation based on surgical procedure volumes, healthcare expenditure, hospital infrastructure, anesthesia practices, and product availability.
- Final market size was estimated through weighted triangulation of company revenues, procedure demand, hospital procurement, and parent-market estimates.
3. List of Key Sources
- Regulatory Sources: FDA, FDA Orange Book, DailyMed, EMA, PMDA, NMPA, CDSCO, TGA, and Health Canada.
- Government and institutional sources: national ministries of health, hospital databases, procurement portals, pharmaceutical tender databases, surgical procedure databases, and national birth statistics.
- Global organizations: WHO, OECD, World Bank, Eurostat, United Nations, UN Comtrade, and International Trade Centre.
- Company sources: annual reports, regulatory filings, investor presentations, product catalogs, prescribing information, company websites, press releases, and manufacturing disclosures.
- Clinical sources: PubMed, NCBI, ClinicalTrials.gov, anesthesia journals, clinical guidelines, systematic reviews, hospital protocols, and formulary documents.
- Validation Inputs: product approvals, generic launches, recalls, shortages, tender awards, manufacturing expansions, product discontinuations, and regional anesthesia adoption trends.
4. Primary Interviews
Supply Side Interviews: 60%
- Ropivacaine manufacturers, generic sterile-injectable companies, contract manufacturers, distributors, commercial partners, and marketing authorization holders.
- Respondents included sales directors, marketing managers, product managers, regulatory-affairs executives, supply-chain managers, manufacturing personnel, and business-development teams.
- Interviews validated company revenues, unit sales, pricing, branded-generic mix, manufacturing capacity, tender participation, distribution networks, and regional market presence.
- Discussions also covered product shortages, new launches, pack-size preferences, infusion-bag adoption, capacity expansion, and competitive positioning.
Demand Side Interviews: 40%
- Anesthesiologists, regional anesthesia specialists, surgeons, pain-management physicians, hospital pharmacists, procurement managers, and maternity-care specialists.
- Interviews assessed the number and type of procedures using ropivacaine, preferred concentration, average dose, administration route, and units consumed per procedure.
- Respondents validate utilization across epidural anesthesia, peripheral nerve blocks, local infiltration, postoperative analgesia, and labor analgesia.
- Discussions also evaluated hospital formulary preferences, branded versus generic selection, substitution with competing local anesthetics, product wastage, tender pricing, and supply availability.
- Demand-side findings were used to refine procedure-based adoption assumptions and hospital consumption estimates.
Frequently Asked Questions
According to Fortune Business Insights, the global market value stood at USD 483.9 million in 2025 and is projected to reach USD 716.8 million by 2034.
In 2025, North America market value stood at USD 170.3 million.
The market is expected to grow at a CAGR of 4.42% over the forecast period of 2026-2034.
The generic product type segment is expected to lead the market.
Rising surgical procedure volumes and aging-related orthopedic demand are driving market growth.
Fresenius Kabi AG, Sandoz Group AG, Aspen Holdings, and Baxter are among the major players in the global market.
North America accounted for the largest global market share in 2025.


- 2021-2034
- 2025
- 2021-2024
- 190
Get 30-60 hrs Free Customization
Expand Regional and Country Coverage, Segments Analysis, Company Profiles, Competitive Benchmarking, and End-user Insights.













.webp)






-
US +1 833 909 2966 ( Toll Free )
-
Get In Touch With Us