 Download Free Sample



Get a Quote
Receive a tailored pricing based on your needs.
- Choose license type
- Multiple user options
- Custom scope & coverage
- Fast turnaround
"Electrifying your pathway to success through in-depth market research"
 Listen to Audio Version
The global printed circuit board market size was valued at USD 74.12 billion in 2025. The market is projected to grow from USD 77.27 billion in 2026 to USD 126.93 billion by 2034, exhibiting a CAGR of 6.4% during the forecast period.
The market covers the design and manufacturing of boards that mechanically support and electrically connect electronic components. The market covers rigid boards, including single-layer, double-layer, and multilayer boards, along with HDI boards, flexible boards, and specialized products such as rigid-flex, metal core, ceramic, and embedded component PCBs. These products are widely used in automotive, consumer electronics, telecommunication, healthcare, energy and power, military, utilities, and others. Printed circuit boards are essential components in electronic systems because they provide compact circuit integration, reliable electrical connections, signal transmission, and support for increasingly complex electronic designs.
The market is mainly driven by rising demand for advanced electronics, electric vehicles, 5G infrastructure, and high-performance computing systems. Zhen Ding Technology Holding Limited, TTM Technologies, Inc., Unimicron Technology Corporation, and Nippon Mektron, Ltd. are the top players in the global market.
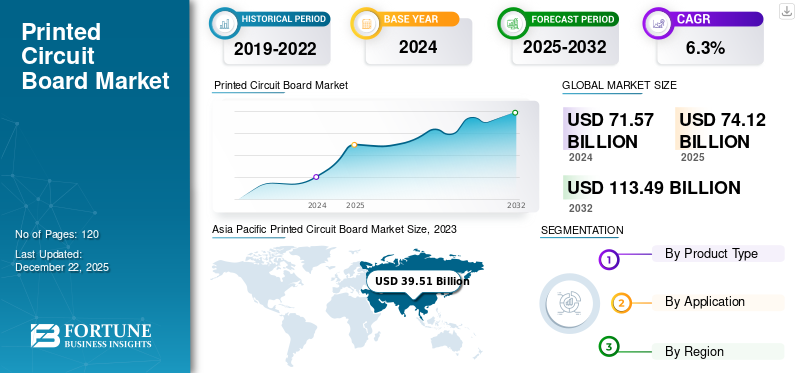
Download Free sample to learn more about this report.
Growing Adoption of Advanced PCBs for AI Infrastructure
The growing deployment of AI servers and data centers is increasing demand for advanced printed circuit boards. Current market trends in the global market show rising adoption of high-density interconnect and high-layer-count PCBs for servers, networking equipment, accelerators, and optical communication systems. The expansion of the Internet of Things (IoT) is also increasing the need for compact and reliable boards. PCB manufacturers are investing in advanced materials, finer PCB design, automation, and expanded manufacturing capacity. These developments are expected to support demand throughout the forecast period.
Download Free sample to learn more about this report.
Growing Adoption of Electric Vehicles to Drive PCB Demand
The rising adoption of electric vehicles is a major factor driving the printed circuit board market growth. Electric vehicles use PCBs across battery management systems, power electronics, infotainment, sensors, charging systems, and advanced driver assistance systems. The increasing demand for PCBs is also supported by rising electronic content across the automotive and broader electronics industry. Each electronic component requires reliable circuit connectivity, which increases PCB usage per vehicle. These factors are expected to support higher growth rates and strengthen the automotive segment's market share.
Market Drivers - Impact & CAGR Contribution (2026–2034)
| Rank | Market Drivers | Overall Impact Rank | Estimated Gross Market Growth Contribution (USD Billion) | Impact: 2026-2028 | Impact: 2029-2031 | Impact: 2032-2034 |
|---|---|---|---|---|---|---|
| 1 | AI, cloud, and HPC growth is increasing the demand for advanced PCBs used in servers and data centers. | High | 14.42 | High | High | High |
| 2 | EV and connected vehicle adoption is increasing PCB use in ADAS, batteries, infotainment, and power electronics. | High | 11.18 | High | High | High |
| 3 | Growing consumer electronics production is supporting the demand for rigid, flexible, and advanced PCBs. | High | 9.76 | High | Medium | Medium |
| 4 | Expansion of 5G and telecom infrastructure is increasing the demand for high-frequency and high-performance PCBs. | High | 8.42 | High | High | Medium |
| 5 | Electronic miniaturization is supporting adoption of HDI, flexible, and rigid-flex PCBs. | Medium | 7.65 | Medium | High | High |
| 6 | Others (Growing demand from industrial electronics, healthcare devices, energy systems, and so on) | Medium | 7.68 | Medium | Medium | High |
| Total Positive Growth Contribution | 59.11 | |||||
Source: Fortune Business Insights
Download Free sample For In-Depth Market Restraints & Risk Analysis
High Capital Requirements and Complex Manufacturing to Limit Market Growth
The high cost of advanced PCB manufacturing is a major restraint for the market. Producing HDI, flexible, multilayer, and high-layer-count boards requires specialized equipment, advanced materials, and strict quality controls. Costs also increase across PCB assembly, testing, drilling, plating, imaging, and inspection processes. While single-sided boards remain relatively cost-effective, advanced boards require much higher investment. Large manufacturers such as TTM Technologies continue to invest in advanced production capabilities, but high capital requirements can create barriers for smaller manufacturers.
Market Restraints - Impact & Negative CAGR Contribution (2026–2034)
| Rank | Market Restraints | Overall Impact Rank | Estimated Reduction in Market Size (USD Billion) | Impact: 2026-2028 | Impact: 2029-2031 | Impact: 2032-2034 |
|---|---|---|---|---|---|---|
| 1 | Volatile raw material prices increase PCB production costs and supply risks. | High | 3.02 | High | Medium | Medium |
| 2 | Advanced PCB manufacturing requires high capital investment and complex production processes. | High | 2.54 | High | High | Medium |
| 3 | Strong price competition and electronics demand cycles pressure utilization and margins. | Medium | 2.01 | High | Medium | Medium |
| 4 | Others (Environmental regulations, compliance costs, manufacturing complexity, and so on) | Medium | 1.88 | Medium | Medium | High |
| Total Negative Growth Impact | 9.45 | |||||
Source: Fortune Business Insights
Download Free sample For In-Depth Market Restraints & Risk Analysis
Expansion of Local PCB Manufacturing to Create Growth Opportunities
The growing focus on local electronics manufacturing is creating a major opportunity for the PCB industry. Governments and companies are working to reduce dependence on concentrated supply chains and expand regional production of electronic components. Although Asia Pacific remains the main PCB manufacturing hub, investments in North America and other regions are supporting geographic diversification. New PCB plants, automation, and advanced manufacturing technologies can improve supply security and reduce delivery times. This shift is also becoming an important consideration as manufacturers expand closer to major electronics customers.
Rigid Boards Segment Dominated the Market Due to Wide Use across Numerous Applications
Based on product type, the market is separated into rigid boards, HDI boards, flexible boards, and others.
In 2025, the rigid boards segment held the largest share of 50.9% due to their widespread use across consumer electronics, automotive systems, industrial equipment, telecommunications, and power electronics. Their strong mechanical stability, mature manufacturing process, broad availability, and lower cost compared with advanced PCB types support their high adoption.
The HDI boards segment is expected to grow at the highest CAGR of 8.6% over the forecast period due to rising demand for compact, lightweight, and high-performance electronic devices with greater circuit density. Increasing use of AI servers, smartphones, advanced automotive electronics, and high-speed communication equipment is further supporting HDI board adoption.
To know how our report can help streamline your business, Speak to Analyst
Consumer Electronics Segment Led the Market Due to High PCB Demand
Based on application, the market is divided into automotive, consumer electronics, telecommunication, healthcare, energy & power, and others.
In 2025, the consumer electronics segment held the dominant printed circuit board market share of 34.1% due to the large production volumes of smartphones, computers, televisions, wearables, gaming devices, and other connected products. Frequent product upgrades and growing demand for smaller and more powerful electronic devices continue to generate strong PCB consumption.
The automotive segment is projected to witness the highest CAGR of 8.6% during the forecast period due to increasing electronic content in electric, connected, and software-defined vehicles. Growing adoption of battery management systems, ADAS, infotainment, sensors, power electronics, and vehicle connectivity is increasing the number and complexity of PCBs used per vehicle.
By geography, the market is categorized into North America, South America, Asia Pacific, Europe, and the Middle East & Africa.
Asia Pacific Printed Circuit Board Market Size, 2025 (USD Billion)
To get more information on the regional analysis of this market, Download Free sample
Asia Pacific dominates the market due to its strong electronics manufacturing base, large semiconductor ecosystem, and concentration of major PCB producers. China, Taiwan, Japan, and South Korea have extensive production capacity for consumer electronics, telecom equipment, automotive electronics, and computing devices. Strong supplier networks, lower manufacturing costs, and continued investments in advanced PCB technologies further support regional leadership.
To know how our report can help streamline your business, Speak to Analyst
The Japan market was valued at around USD 6.97 billion in 2025, accounting for roughly 9.4% of global revenues.
The China market is projected to be one of the largest globally, with 2025 revenues valued at USD 28.40 billion, roughly 38.3% of global sales.
The Indian market was valued at USD 3.94 billion in 2025, accounting for roughly 5.3% of global revenues.
North America holds the second-largest market share due to strong demand from aerospace, defense, automotive, telecommunications, data centers, and advanced computing applications. The U.S. has a well-developed electronics ecosystem and growing demand for high-reliability and advanced PCBs. Increasing investments in semiconductor manufacturing, AI infrastructure, electric vehicles, and domestic electronics production are also supporting PCB demand across the region.
The U.S. market was valued at around USD 7.11 billion in 2025, accounting for roughly 9.6% of global sales.
Europe holds a significant market share due to strong demand from automotive, industrial automation, healthcare, aerospace, and energy applications. Germany, France, Italy, and other European countries have established manufacturing industries that require reliable and advanced electronic components. Growth in electric vehicles, renewable energy systems, factory automation, and connected devices continues to support demand for high-performance and specialized PCBs across the region.
The U.K. market was valued at approximately USD 0.92 billion in 2025, accounting for roughly 1.2% of global revenues.
The Germany market reached USD 1.65 billion in 2025, equivalent to around 2.2% of global sales.
The Middle East & Africa market is projected to grow at the highest CAGR over the forecast period due to rising investments in digital infrastructure, telecommunications, renewable energy, industrial automation, and local electronics manufacturing. Countries in the GCC are expanding data centers, smart cities, electric mobility, and advanced communication networks. Growing demand for electronic equipment and efforts to diversify regional economies are expected to increase PCB consumption significantly.
The GCC market reached USD 0.54 billion in 2025, accounting for roughly 0.7% of global revenues.
South America accounts for a relatively small share of the global market due to limited local PCB manufacturing capacity and greater dependence on imported electronic components. The regional electronics manufacturing ecosystem is less developed compared with Asia Pacific, North America, and Europe. However, demand is gradually increasing from automotive, telecommunications, consumer electronics, industrial equipment, and renewable energy projects, particularly in Brazil and other major economies.
The Brazil market was valued at USD 1.14 billion in 2025, accounting for roughly 1.5% of global revenues.
Major Players Invest in HDI and Advanced Manufacturing Technologies for a Competitive Advantage
Competition in the printed circuit board market is increasing as demand grows for advanced PCBs used in AI servers, data centers, automotive electronics, and high-performance devices. Leading manufacturers are investing in HDI, ultra-HDI, high-layer-count boards, flexible circuits, and advanced manufacturing technologies. Companies are also expanding production capacity across major manufacturing regions to support rising customer demand and strengthen supply chains. Investments in automation, finer circuit designs, higher interconnect density, and advanced materials are further helping PCB manufacturers improve performance and strengthen their competitive positions.
The printed circuit board market report provides a detailed analysis of market size, forecasts, segmentation, market drivers, restraints, opportunities, key trends, and major developments. It covers major product types such as rigid boards, HDI boards, flexible boards, and other types. The report also studies key applications, including automotive, consumer electronics, telecommunication, healthcare, energy and power, and others. It examines market trends across North America, South America, Europe, the Middle East & Africa, and Asia Pacific. The report also covers market share, business strategies, SWOT analysis, Porter’s Five Forces, competitive landscape, and leading companies operating worldwide.
Request for Customization to gain extensive market insights.
| ATTRIBUTE | DETAILS |
| Study Period | 2021-2034 |
| Base Year | 2025 |
| Estimated Year | 2026 |
| Forecast Period | 2026-2034 |
| Historical Period | 2021-2024 |
| Growth Rate | CAGR of 6.4% from 2026 to 2034 |
| Unit | Value (USD Billion) |
| Segmentation | By Product Type, By Application, and By Region |
| By Product Type |
|
| By Application |
|
| By Region |
|
Fortune Business Insights says that the global market value stood at USD 74.12 billion in 2025 and is projected to reach USD 126.93 billion by 2034.
In 2025, the Asia Pacific market value stood at USD 55.08 billion.
The market is expected to grow at a CAGR of 6.4% over the forecast period.
By application, the consumer electronics segment led the market in 2025.
The key factors driving the market include the expansion of electric vehicles, 5G infrastructure, and connected devices.
Zhen Ding Technology Holding Limited, TTM Technologies, Inc., Unimicron Technology Corporation, and Nippon Mektron, Ltd. are among the top players in the market.
Asia Pacific held the largest market share in 2025.
The major factors expected to favor product adoption include the growing demand for compact and high-performance electronic devices.

Get 30-60 hrs Free Customization
Expand Regional and Country Coverage, Segments Analysis, Company Profiles, Competitive Benchmarking, and End-user Insights.




















Related Reports
Get In Touch With Us
US +1 833 909 2966 ( Toll Free )
Receive a tailored pricing based on your needs.
Discuss your questions with our industry experts.
Have questions? Get quick answers before you purchase.

