 Download Free Sample



Get a Quote
Receive a tailored pricing based on your needs.
- Choose license type
- Multiple user options
- Custom scope & coverage
- Fast turnaround
"Designing Growth Strategies is in our DNA"
 Listen to Audio Version
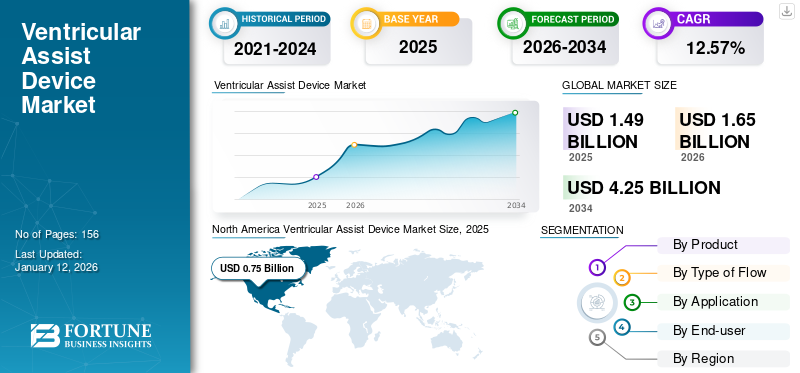
The ventricular assist device market size was valued at USD 1.49 billion in 2025. The market is projected to grow from USD 1.64 billion in 2026 to USD 3.54 billion by 2034, exhibiting a CAGR of 10.1% during the forecast period.
Ventricular assist devices (VAD) are implanted in heart failure patients with severe symptoms to provide them with mechanical circulatory support by pumping blood from the chambers of the heart to the whole body. The increasing prevalence of heart failure has been fueling the demand for these devices globally.
Abbott, ABIOMED, and Berlin Heart held the largest global market share in 2025. The market players’ increased focus on R&D initiatives to develop efficient devices is contributing to their dominance.
Download Free sample to learn more about this report.
Increasing Technological Developments to Fuel the Demand for Mechanical Circulatory Support System
Technological advancements in the healthcare industry are assisting healthcare professionals to record and monitor clinical data regularly through artificial intelligence with minimal errors. The high-performance capabilities of artificial intelligence (AI) algorithms will transform the market outlook.
AI can be helpful in determining the risk of cardiovascular diseases, which can be used to enhance risk prediction and treatment among patients. It can also be utilized during surgeries to analyze the patient’s anatomy, risk factors, history of disease, and other factors, which can enhance the results of the surgeries.
In cardiothoracic surgery, machine learning algorithms can outperform standard operative risk scores in predicting intra-hospital mortality after cardiac procedures. Thus, the development of technology in cardiac procedures is likely to propel ventricular assist device adoption.
Technological developments in medical devices have enhanced the efficiency of these devices. Thus, the rate of infection through the devices is reduced simultaneously. Latest devices, such as HeartMate III and DuraHeart, have features such as lower rotational speeds, smaller sizes, higher efficiency, and enhanced anatomic design. The LVAD pump is surgically implanted inside the patient's body and connected to an external controller and power source through a percutaneous driveline that exits through the skin. It provides mechanical circulatory support to patients with weakened hearts and helps pump oxygenated blood from the left ventricle into the ascending aorta. Thus, the development of these effective devices in the market is expected to propel the market growth during the forecast period.
Download Free sample to learn more about this report.
Increasing Prevalence of Heart Failure to Increase the Demand for VAD
Heart failure is one of the leading causes of mortality worldwide, affecting more than 1-2% of the population in Western countries. For instance, the American Heart Association reported in May 2025 that approximately 6.7 million adults were living with heart failure, with the number projected to exceed 8 million by 2030.
When medications are not very effective in the disease treatment and heart transplantation is not feasible, mechanical circulatory support devices are also used to assist cardiac circulation, which is used either to partially or to completely replace the function of a failing heart, mechanical support systems include VAD, Total Artificial Heart (TAH), extracorporeal Membrane Oxygenator (ECMO) Pumps, and Intra-Aortic Balloon Pumps (IABP).
The increasing prevalence and rising death cases due to the failure of the heart have increased the demand for VAD, as it can be used for both bridges to transplant as well as destination therapy.
Furthermore, to fuel the increasing demand for VAD, market players have been focusing on new product launches and the expansion of their production capacity. For instance, in June 2021, Abbott expanded the supply of its ventricular assist device, HeartMate 3, to fuel the growing demand. Such a scenario is anticipated to drive the global ventricular assist device market growth during the forecast period.
Market Drivers - Impact & CAGR Contribution (2026–2034)
| Rank | Market Drivers | Expected Impact on Market Growth | Estimated Gross Market Growth Contribution (USD Billion) | Impact: 2026-2028 | Impact: 2029-2031 | Impact: 2032-2034 |
|---|---|---|---|---|---|---|
| 1 | Increasing prevalence of heart failure increases the demand for VADs | High | 0.78 | High | High | High |
| 2 | Persistent shortage of donor hearts and increasing utilization of VADs for BTT, BTC, and destination therapy | High | 0.62 | High | High | High |
| 3 | Technological advancements in VAD systems, including magnetically levitated pumps, improved hemocompatibility, miniaturization, and connected monitoring | Medium-High | 0.50 | Medium | High | High |
| 4 | Expansion of advanced heart-failure/VAD centers and improving reimbursement and healthcare infrastructure, particularly in emerging markets | Medium-High | 0.36 | Medium | Medium | High |
| 5 | Increasing product approvals, geographic commercialization, and replacement/reimplantation demand from the expanding installed VAD base | Medium | 0.31 | Medium | Medium | Medium |
| 6 | Others (pediatric VAD adoption, clinical guideline expansion, remote monitoring, hospital investment, patient awareness and competitive market entry) | Low | 0.18 | Low | Low | Medium |
| Total Positive Growth Contribution | 2.75 | |||||
Source: Fortune Business Insights
Download Free sample For In-Depth Market Restraints & Risk Analysis
High Cost Associated with the Use of VAD to Limit its Adoption
The limited availability of heart donors and the increasing prevalence of heart failure have increased the penetration of these devices. However, the high costs associated with the implantation of these devices have been limiting their adoption.
Such high costs associated with the implantation of these devices have been restricting their adoption by the patient population globally.
Sometimes these devices might stop working efficiently after implantation. For instance, a VAD might not pump blood effectively, or the power supply might fail. These problems require immediate medical attention and may require the pump to be replaced. Such factors limit the product penetration.
Therefore, the high costs and other complications associated with the device might limit the device’s adoption in the forecast period.
Market Restraints - Impact & Negative CAGR Contribution (2026–2034)
| Rank | Market Restraints | Expected Impact on Market Growth | Estimated Reduction in Market Size (USD Billion) (2026-2034) |
Impact: 2026-2028 | Impact: 2029-2031 | Impact: 2032-2034 |
|---|---|---|---|---|---|---|
| 1 | High Cost Associated with the Use of VAD | High | 0.34 | High | High | High |
| 2 | Risk of bleeding, infection, stroke, pump thrombosis, and other device-related complications | Medium-High | 0.28 | High | High | Medium |
| 3 | Limited availability of specialized VAD centers, trained cardiothoracic surgeons and multidisciplinary heart-failure teams in several countries. | Medium-High | 0.15 | Medium | Medium | High |
| 4 | Others (regulatory delays, stringent clinical requirements, product recalls, patient-selection limitations and supply-chain constraints) | Low | 0.08 | Low | Low | Low |
| Total Market Reduction | 0.85 | |||||
Source: Fortune Business Insights
Download Free sample For In-Depth Market Restraints & Risk Analysis
Expansion of Destination Therapy Among Non-Transplant-Eligible Patients to Create New Market Opportunities
In recent years, there has been an increasing demand for left ventricular assist devices (LVADs) as destination therapy (DT) as they provide long-term mechanical circulatory support to patients with advanced heart failure who are not suitable candidates for heart transplantation owing to advanced age, comorbidities, or other clinical factors.
Current CMS coverage includes FDA-approved LVADs for long-term mechanical circulatory support, including destination therapy, which is further creating significant opportunity for VADs as destination therapy (DT).
Risk of Bleeding, Infection, Thrombosis, and Other Device-Related Complications to Limit Adoption
Despite substantial improvements in VAD design and hemocompatibility, the device and treatment-related complications remain an important challenge to wider adoption of ventricular assist devices. Also, the patients receiving durable LVADs require prolonged anticoagulation and continuous device management, increasing overall treatment costs. Moreover, Several complications persist even with contemporary magnetically levitated devices.
This is potentially discouraging eligible patients and physicians from choosing VAD therapy, which is expected to pose a major challenge for the market’s expansion.
Increasing Implantations to Drive Growth of the LVAD Segment
Based on product, the market is segregated into left ventricular assist device (LVAD), right ventricular assist device, and bi-ventricular assist device.
The LVAD segment accounted for the highest market share in 2025 due to the number of implantation procedures amongst patients globally. Market players are focusing on developing these devices for patients with heart failure and other cardiovascular diseases, as they help the heart to function by supporting the chambers of the heart in patients. For instance, in September 2025, AdventHealth joined the INNOVATE pivotal trial and performed its first BrioVAD implantation, expanding clinical evaluation of the next-generation durable LVAD.
The biventricular assist device (Bi-VAD) segment is expected to grow at a CAGR of 7.6% during the forecast period.
To know how our report can help streamline your business, Speak to Analyst
High Efficiency Associated with the Use of Continuous Flow Devices to Surge Segment Growth
Based on type of flow, the market is segmented into pulsatile flow and continuous flow.
The continuous flow segment held a significant market share in 2025 due to the benefits of continuous flow. Continuous flow devices have benefits such as lower maintenance, minimal noise, rare replacements, and a few moving parts. The benefits of continuous flow devices have been increasing their demand among physicians and researchers. To meet the demand in the market, the major players, such as Heart Inc., launched DuraHeart LVAD, a continuous flow device.
The pulsatile flow segment is projected to grow at a substantial CAGR of 9.2% during the forecast period.
Growing Use of Long-Term Mechanical Circulatory Support to Drive Destination Theraphy Segment
In terms of application, the market is segmented into bridge to transplant (BTT), bridge to candidacy (BTC), destination therapy (DT), and bridge to recovery (BTR).
The destination therapy (DT) segment accounted for the highest ventricular assist device market share during 2025, owing to a rise in final-stage cardiac failure incidence. DT is an alternative to transplant that can improve functional capacity, extend patients' lives, and relieve symptoms of heart failure. LVADs have their application as destination therapy for the treatment of patients who cannot undergo heart transplantation. The limited availability of heart donors and complications associated with heart transplantation surgeries fueled the segment’s growth. Furthermore, the segment is expected to account for a 45.7% share of the market by 2026.
However, the bridge to transplant (BTT) segment is growing at a higher growth rate of 10.7% during the forecast period.
Hospitals & Ambulatory Surgery Centers (ASCs) to Account for Largest Share Owing to Demand in Surgical Procedures
In terms of end-user, the market is segmented into hospitals & ASCs and specialty clinics & others. The hospitals & ASCs segment is expected to hold the dominant share in the market during the forecast period due to an increase in hospital stays of patients undergoing heart surgeries such as device placement or implant procedures.
The specialty clinics & others segment is expected to grow at a CAGR of 13.8% during the forecast period.
North America Ventricular Assist Device Market Size, 2025 (USD Billion)
To get more information on the regional analysis of this market, Download Free sample
North America dominated the global market and generated revenue of USD 0.75 billion in 2025, and in 2024, the regional market value was USD 0.69 billion. The dominance of this regional market is attributable to the growing prevalence of cardiovascular diseases and heart transplantation volumes in the region. Moreover, an increasing number of collaborations and agreements amongst the key players emphasizing the development of this market have been fueling the adoption of these devices in the region.
In 2026, the U.S. is anticipated to reach USD 0.81 billion, accounting for approximately 49.3% of the global sales.
Europe is projected to record a CAGR of 10.1% during the forecast period, the second-highest globally. The market is expected to reach USD 0.51 billion in 2026. The region’s growth is attributed to higher investments for the development of ventricular assist devices and the presence of key players in the region.
The Asia Pacific is likely to be the third-largest market with a value of USD 0.19 billion in 2026 and witness a fast-paced growth during the forecast period owing to advancements in healthcare facilities and favorable government policies. Medical device companies are making investments in the region for these devices to increase their adoption in the market, which is projected to boost the market growth.
Japan is projected to reach approximately USD 0.04 billion in revenue in 2026, representing nearly 2.4% of the global sales.
In 2026, China is anticipated to reach USD 0.08 billion, accounting for approximately 4.9% of the global sales.
In 2026, India is anticipated to reach USD 0.01 billion, accounting for approximately 0.7% of the global sales.
Latin America and the Middle East & Africa accounted for a comparatively lower share of the market, with Latin America accounting for the value of USD 0.06 billion in 2026. The share is due to increasing penetration by key players in Latin America. Moreover, the Middle East & Africa market growth is attributed to awareness programs initiated by government organizations, leading to increased diagnosis and treatment rates for heart failure in the region.
Companies with Strong Sales of VAD to Boost Market Competition
Abbott, ABIOMED, and Berlin Heart are among the prominent players in the market and captured a considerable global market share in 2025.
This is due to the companies’ strong sales of the devices and well-established brand reputation. Moreover, the company has a strong focus on strategic initiatives with an aim to expand its product offerings globally.
Other prominent players present in the market are focusing on receiving approval from regulatory bodies to expand the product portfolio and strengthen market shares during the forecast period.
Moreover, several companies have their products in the R&D stage. The launch of these products is expected to grab significant market shares in the coming years.
The research report provides a detailed competitive landscape. It includes the number of VAD implantations and key industry developments such as partnerships, mergers, and acquisitions. Additionally, it focuses on key points such as new product launches in the market. Furthermore, the report covers a regional analysis of different segments, company profiles of key market players, and market trends. The report consists of quantitative and qualitative insights contributing to the market growth.
Request for Customization to gain extensive market insights.
| ATTRIBUTE | DETAILS |
| Study Period | 2021-2034 |
| Base Year | 2025 |
| Estimated Year | 2026 |
| Forecast Period | 2026-2034 |
| Historical Period | 2021-2024 |
| Growth Rate | CAGR of 10.1% over 2026 to 2034 |
| Unit | Value (USD Billion) |
| Segmentation | By Product, Type of Flow, Application, End-user, and Region |
| By Product |
|
| By Type of Flow |
|
| By Application |
|
| By End-user |
|
| By Region |
|
Fortune Business Insights says that the global market is projected to grow from USD 1.49 billion in 2025 to USD 3.54 billion by 2034.
The market is expected to exhibit a CAGR of 10.1% during the forecast period (2026-2034).
The left ventricular assist device segment is set to lead the market by product.
The key factors driving the market are the increasing prevalence of heart failure worldwide.
Abbott, ABIOMED, and Berlin Heart are the top players in the market.

Get 30-60 hrs Free Customization
Expand Regional and Country Coverage, Segments Analysis, Company Profiles, Competitive Benchmarking, and End-user Insights.













.webp)






Related Reports
Get In Touch With Us
US +1 833 909 2966 ( Toll Free )
Receive a tailored pricing based on your needs.
Discuss your questions with our industry experts.
Have questions? Get quick answers before you purchase.

