Urea Market Size, Share & Industry Analysis, By Grade (Fertilizer Grade, Feed Grade, and Technical Grade), By Application (Agriculture, Animal Feed, Chemical Synthesis, and Others), and Regional Forecast, 2026-2034
 Download Free Sample

(Offer valid till 15th Oct 2026)

Urea Market Size and Industry Overview
 Listen to Audio Version
The global urea market size was valued at USD 85.33 billion in 2025. The market is projected to grow from USD 78.88 billion in 2026 to USD 104.54 billion by 2034, exhibiting a CAGR of 3.6% during the forecast period.
Commercially, ammonium carbamate is produced by reacting ammonia with carbon dioxide. Further, ammonium carbamate is decomposed to yield urea (carbamide) in solid form. As the product is enriched with nitrogen, it has become a popular choice as a source of nitrogen in the fertilizer industry. Protein requirements in ruminant animals can be sufficiently met by feed grade. Industrially, it is produced through the reaction of ammonia and carbon dioxide under high pressure and temperature, primarily as part of the Haber-Bosch process. It is also widely utilized in industrial applications, including the manufacture of resins, adhesives, plastics, and pharmaceuticals, as well as in environmental control systems such as Diesel Exhaust Fluid (DEF) for reducing nitrogen oxide emissions. The market’s growth is driven by rising global food demand, increasing agricultural productivity needs, expansion of industrial uses, and regulatory measures promoting cleaner emissions.
Furthermore, the market encompasses several major players such as SABIC, Yara International, and Nutrien.
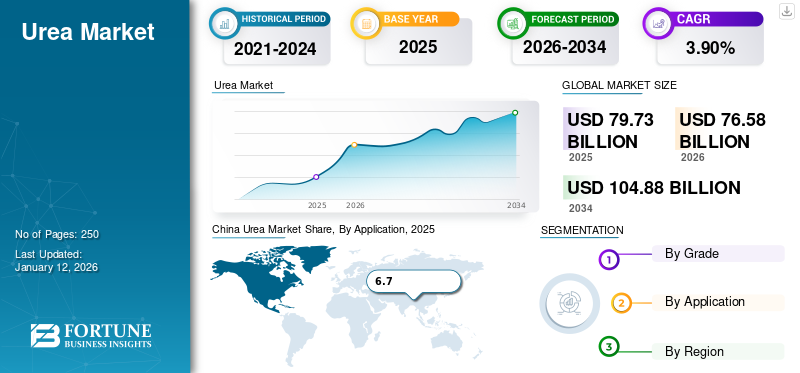
Download Free sample to learn more about this report.
Urea Market Trends
Technological Developments in Manufacturing Processes to Aid Market Growth
Developments in production technologies such as Blue Urea present lucrative opportunities for urea market growth. This innovative product is produced under attenuated reaction conditions using water, nitrogen, and carbon dioxide as raw materials. The energy used in the production process is obtained from renewable sources such as wind turbines located at a point of use or closer to agricultural land. During the reaction, hydrogen is produced through the process of electrolysis. The equipment can be housed in a standardized ISO container at the point of use. This helps in the delocalization of production, eliminating costs and emissions associated with transportation. This technique also helps to overcome emissions of different pollutants associated with the conventional manufacturing process. Also, the composition of the product obtained by this technique is free of contaminants, making it ideal for use.
Market Dynamics
Market Drivers
Download Free sample to learn more about this report.
Rising Crop-Nutrition Requirements and Government-Supported Fertilizer are Key Drivers for Market Growth
Urea remains a critical agricultural input as it contains approximately 46% nitrogen, making it one of the most concentrated solid nitrogen fertilizers commercially available. Its high nutrient content, relatively low transportation cost per unit of nitrogen, and suitability for direct soil application, fertigation, and fertilizer blending support widespread adoption across cereals, oilseeds, fruits, and vegetables. Additionally, population growth, food-security priorities, and the need to raise crop yields on constrained agricultural land are expected to sustain nitrogen-fertilizer consumption. The United Nations estimated the global population at 8.2 billion in 2024 and projects that it is to peak at approximately 10.3 billion during the mid-2080s, increasing long-term pressure on agricultural productivity and food supply systems. Urea supports vegetative growth and yield formation by replenishing nitrogen removed from soils through repeated crop harvesting.
Moreover, government subsidies and regulated pricing continue to protect agricultural urea consumption from international price volatility. Such support substantially improves affordability for farmers and helps maintain application volumes even when natural gas, ammonia, freight, or imported carbamide costs increase.
Feed-grade urea provides an additional, although comparatively smaller, source of market demand. Rumen microorganisms can convert carbamide-derived non-protein nitrogen into microbial protein when sufficient fermentable energy is available. FAO guidance indicates that commercially prepared dairy-cattle concentrate feeds commonly contain approximately 1-2% urea, replacing part of the nitrogen otherwise supplied by oilseed meals and protein-rich feed ingredients. Its cost advantage may support adoption in cattle and sheep production, particularly where conventional protein-feed prices are elevated.
Growing Demand from Industrial Applications to Drive Market Growth
Recently, there has been a huge rise in demand for carbamide from the manufacturing sectors owing to its wide range of industrial applications. It has the ability to trap different organic compounds due to its property of forming interpenetrating helices by forming hydrogen bonds. This property makes it a suitable product for the separation of mixtures and to be used in the production of aviation fuels and lubricating oils. It is also used in the separation of paraffin. In the automotive industry, the product is used to reduce nitrogen oxide pollutants from the combustion of fuel. For instance, BlueTec solutions inject the aqueous solution into the exhaust system. After decomposition, ammonia converts nitrogen oxide emissions into water and nitrogen in a catalytic converter.
Technical grade is used as a raw material in the manufacturing of urea-formaldehyde resins, adhesives such as urea-melamine-formaldehyde used in marine plywood, and stabilizers in nitrocellulose explosives. In the pharmaceutical and cosmetics industry, it finds a wide range of applications. It serves as a source of hydrogen in rehydration products as well as subsequent power generation in fuel cells. It is a key raw material for manufacturing different drugs and chemical intermediates, such as an ingredient in hair removers, hair conditioners, bath oils, skin softeners, lotions, disinfectants, and others. Other commercial applications include de-icers by airports, ingredients of yeast nutrients, flavor-enhancing additives for cigarettes, protein denaturants, and radioactive detectors in different diagnostic tests.
Market Drivers - Impact & CAGR Contribution (2026–2034)
| Rank | Market Drivers | Overall Impact Rank | CAGR Contribution (2026-2034) | Impact: 2026-2028 | Impact: 2029-2031 | Impact: 2032-2034 |
|---|---|---|---|---|---|---|
| 1 | Rising food demand and crop-nutrition requirements | High | 1.6% | High | High | High |
| 2 | Government subsidies and support for domestic fertilizer production | High | 1.2% | High | High | Medium |
| 3 | Expansion of industrial and environmental-control applications | High | 1.0% | Medium | High | High |
| 4 | Advancement of low-carbon and enhanced-efficiency urea technologies | Medium | 0.9% | Medium | High | High |
| 5 | Growing use of feed-grade urea in animal nutrition | Medium | 0.7% | Medium | Medium | Medium |
| 6 | Others (Includes expansion of fertilizer-distribution networks, growth in emerging agricultural markets, increased fertilizer blending, technical product innovation, and wider adoption of precision agriculture.) | Low | 0.5% | Low | Low | Low |
| Total Positive Growth Contribution | 5.90% | |||||
Source: Fortune Business Insights
Download Free sample For In-Depth Market Drivers & Impact Forecasts
Market Restraints
Shift Toward Organic and Nutrient-Efficient Farming to Hinder Market Growth
Growing concern regarding soil degradation, nutrient runoff, ammonia volatilization, and greenhouse-gas emissions is encouraging governments, food companies, and farmers to reduce excessive dependence on conventional nitrogen fertilizers. Organic farming systems generally restrict synthetic urea and instead rely on crop rotation, legumes, compost, manure, and other biological nutrient management practices. As certified organic acreage expands, carbamide demand per cultivated hectare may decline in selected crops and developed agricultural markets.
According to the Research Institute of Organic Agriculture, global organic farmland increased by 2.6% in 2023 to 98.9 million hectares, managed by approximately 4.3 million organic producers. Organic agriculture is practiced in nearly 190 countries and currently represents slightly more than 2% of global agricultural land. Europe accounted for approximately 19.5 million hectares of organic farmland, making it one of the markets where the shift away from synthetic fertilizers could exert a comparatively greater effect.
Market Restraints - Impact & Negative CAGR Contribution (2026–2034)
| Rank | Market Restraints | Overall Impact Rank | Negative CAGR Contribution (2026-2034) | Impact: 2026-2028 | Impact: 2029-2031 | Impact: 2032-2034 |
|---|---|---|---|---|---|---|
| 1 | Environmental regulations and nitrogen-emission concerns | High | -0.8% | Medium | High | High |
| 2 | Shift toward organic and nutrient-efficient farming | Medium | -0.6% | Medium | Medium | High |
| 3 | Trade protectionism, geopolitical instability, and supply-chain disruption | Medium | -0.5% | High | High | Medium |
| 4 | Others (Includes natural-gas price volatility, production outages, high capital requirements, competition from alternative nitrogen fertilizers, currency fluctuations, and seasonal demand variability.) | Low | -0.2% | Low | Low | Low |
| Total Negative Growth Impact | -2.10% | |||||
Source: Fortune Business Insights
Download Free sample For In-Depth Market Restraints & Risk Analysis
Market Opportunities
Government Support for Fertilizer Affordability, Domestic Production, and Sustainable Urea Manufacturing Creates Growth Opportunities
Government intervention remains an important opportunity for the global market, particularly in countries where food security and agricultural productivity are strategic priorities. Subsidies, regulated pricing, input support programs, and government procurement mechanisms improve fertilizer affordability for farmers and help maintain stable carbamide demand despite fluctuations in energy, feedstock, and international market prices.
Governments are also encouraging domestic carbamide production to reduce import dependence and improve supply security. Investments in new plants, plant restarts, modernization, energy-efficiency upgrades, and distribution infrastructure create opportunities for urea producers, engineering companies, technology licensors, equipment suppliers, and logistics providers. These initiatives can strengthen regional availability and reduce exposure to international supply disruptions.
Market Challenges
Environmental and Regulatory Pressures Could Lead to Several Market Challenges
Excessive use of urea-based fertilizers in agriculture contributes to nitrogen runoff, which leads to water pollution, eutrophication, and greenhouse gas emissions, particularly nitrous oxide, a potent climate-warming gas. Governments and environmental agencies across the globe are increasingly imposing restrictions on nitrogen fertilizer usage to mitigate these impacts. Policies such as carbon taxation, emission reduction mandates, and fertilizer application limits are forcing carbamide producers to adopt more sustainable production methods and promote efficient fertilizer usage among end consumers. Compliance with these environmental regulations often requires significant investment in cleaner production technologies, energy-efficiency upgrades, and carbon capture systems, increasing operational costs. Additionally, public awareness about the environmental consequences of synthetic fertilizers is driving demand for alternative products, such as bio-based or slow-release fertilizers, creating competitive pressure.
Impact of Trade Protectionism and Geopolitical
Trade protectionism, including the imposition of tariffs, export restrictions, and import quotas, can significantly disrupt the supply-demand balance in key urea-producing and consuming regions. For instance, major producers such as India, China, and Russia have periodically adjusted export policies to protect domestic supply, impacting global prices and availability. Such measures can result in sudden price volatility, forcing import-dependent countries to seek alternative suppliers at higher costs, thereby increasing operational and logistical challenges for farmers and fertilizer distributors. Geopolitical tensions further compound these challenges by creating uncertainty in supply chains. Conflicts in major producing regions can disrupt production, export, and shipping routes, as seen with events affecting Russian and Middle Eastern fertilizer exports. Political instability may also influence investment decisions in capacity expansion or greenfield projects, as companies hesitate to commit resources to high-risk regions.
Research and Development (R&D) Trends
The development of "green" urea production methods aims to reduce the environmental impact of traditional processes. For instance, plasma-ice interaction techniques utilizing gas mixtures such as N₂ + CO₂ and NH₃ + CO₂ have shown promise in synthesizing urea in an energy-efficient and environmentally friendly manner. These methods leverage high-energy species to produce reactive intermediates, facilitating carbamide formation under milder conditions compared to conventional processes. Additionally, advancements in catalyst design are being accelerated through Artificial Intelligence (AI) workflows. By integrating large language models and Bayesian optimization, researchers can expedite the development of catalysts for ammonia production, a precursor to urea synthesis. This approach enhances the efficiency and precision of catalyst optimization, potentially leading to more sustainable and cost-effective carbamide production methods.
Segmentation Analysis
By Grade
Fertilizer Grade Segment Led the Market Due to Extensive Adoption as Key Nitrogen Fertilizer
Based on grade, the market is classified into fertilizer grade, feed grade, and technical grade.
In 2025, the fertilizer grade segment held the leading urea market share at 74.1% and is expected to retain its position in the coming years. The segment’s growth is attributed to the increased use of fertilizers to enhance the production of crops. Recent decades have witnessed a significant increase in population, particularly in developing regions such as Asia and Africa. This population growth has increased food demand, placing greater burden on limited agricultural land and driving higher fertilizer use.
The feed grade segment is projected to grow at a CAGR of 3.18% during the forecast period. Increased industrialization has led to a decrease in grazing and pasture land, creating the need for alternative feed sources for animals. This has led to an increase in demand for feed-grade products to supplement the diets of cattle and other ruminants. Cattle and ruminants convert urea into protein by digestion through bacterial action. It helps in maximizing the feed benefits, especially in the dry season.
The technical grade segment is growing at the fastest rate owing to increasing industrialization throughout the globe. Major technical applications include glue and resins, plastic manufacturing, metal treatment, the wood industry, tanneries, construction, and civil engineering. Also, technical-grade urea has a wide range of applications in health and beauty products.
By Application
To know how our report can help streamline your business, Speak to Analyst
Agriculture Segment Accounted for the Leading Share Owing to Higher Demand
Based on application, the market is classified into agriculture, animal feed, chemical synthesis, and others.
The agriculture segment held the leading market share in 2025. The segment’s dominance can be attributed to the large-scale use of carbamide as a fertilizer for increasing crop yield. Granular and prilled forms make it easy for transportation and handling in agricultural applications. It is applied to the soil surface or mixed with soil; however, it can also be applied manually or mechanically. It is used before the plantation as well as after the plantation, as per the requirements of the soil and crop.
The animal feed segment is expected to grow at a CAGR of 3.18% over the forecast period. The shortage of protein feeds and the high cost of supplementing proteins are making carbamide an alternative supplement for animal feed. The feed-grade product comes with around 45% nitrogen content, which is equivalent to 281% crude protein. Decreased availability of pasture land and increasing prices of conventional animal feed are expected to push the growth of the segment.
The chemical synthesis segment is projected to indicate the fastest growth in the market. Technical grade products are widely used to prepare resins, pharmaceutical and cosmetic formulations, and other specialty chemicals.
UREA MARKET REGIONAL OUTLOOK
By region, the market is segmented into North America, Europe, Asia Pacific, Latin America, and the Middle East & Africa.
Asia Pacific
Asia Pacific Urea Market Size, 2025 (USD Billion)
To get more information on the regional analysis of this market, Download Free sample
Asia Pacific held the dominant share in 2025, valued at approximately USD 51.88 billion. The region has experienced significant population growth, resulting in increased food demand. This has led to increased demand for fertilizers to improve crop yields per hectare of agricultural land. In addition, the increasing use of carbamide in the animal feed industry is driving demand for feed-grade products in the region. These factors have contributed to an increase in carbamide production to meet growing demand.
The region's dominant position is attributed to the high levels of production and consumption in China, followed by India, ASEAN countries, Japan, and South Korea. Moreover, local governments in the region are assisting farmers by providing subsidies for the purchase of fertilizers to increase food-grain production. For instance, the Government of India announced a subsidy of approximately USD 269.4 billion in the financial year 2022-2023.
China Urea Market
In 2026, the China market size is estimated to reach USD 18.74 billion. China is the world’s largest producer and consumer of carbamide, with its market driven by strong agricultural and industrial demand. The Chinese government continues to promote balanced fertilization and improvements in soil health, which boosts market demand while also encouraging greater efficiency through controlled-release and stabilized formulations.
To know how our report can help streamline your business, Speak to Analyst
India Urea Market
The Indian market size in 2026 is estimated at around USD 0.25 billion, representing approximately 5.5% of global revenue.
Japan Urea Market
The Japan market size is projected to reach approximately USD 13.20 billion by 2026, accounting for about 16.7% of global sales.
Europe
Europe is expected to experience steady growth in the coming years. The European region is projected to grow at approximately 3.38% over the forecast period, reaching a valuation of USD 12.13 billion in 2025. Europe imports carbamide from Asia and the Middle East. Backed by strict regulations, technological developments in the product are expected to reduce carbon emissions as well as decrease input costs.
The developed automotive sector in the region is propelling the market. This growth is driven by the increasing adoption of measures to reduce nitrogen oxide pollutants from fuel combustion. Increasing regulations aimed at limiting greenhouse gas emissions are expected to surge demand from the automotive sector in the region.
Russia Urea Market
The Russia market size in 2026 is estimated at around USD 2.21 billion, representing approximately 2.8% of global revenue.
Germany Urea Market
Germany’s market size is projected to reach approximately USD 1.50 billion by 2026, accounting for 1.9% of global sales.
North America
North America is expected to be a steadily growing market during the forecast period. The growth in this region is mainly attributed to higher demand for agricultural products, as well as rising demand for industrial applications. Farmers use nitrogenous fertilizers to achieve higher yields of corn, canola, wheat, and other crops. This demand is expected to rise in the foreseeable future, owing to increasing food demand in the region. Additionally, the industrial use of carbamide in resin manufacturing and automotive emissions control (DEF/AdBlue) contributes to consumption.
U.S. Urea Market
In 2026, the U.S. market size is estimated to reach USD 8.36 billion. The growth of the market is driven by the country's expansive agricultural sector, which relies heavily on nitrogen-based fertilizers for corn, soybean, and wheat production. Precision farming, advanced agronomy, and increasing crop yields are key demand boosters.
Latin America
Despite the sufficient availability of raw materials, Latin America imports a considerable portion of its total requirements. For instance, in February 2022, the Brazilian government signed an agreement with the Iranian National Petrochemical Company to triple its shipments from Iran to meet rising demand in the country. Hence, there is considerable scope for expanding and establishing new manufacturing facilities in Latin America.
Brazil Urea Market
Brazil’s market value is expected to reach approximately USD 3.47 billion by 2026, equivalent to around 4.4% of global sales.
Middle East & Africa
The Middle East & Africa is one of the key manufacturing regions due to the presence of large-scale producers in the region. There is a rising demand from agriculture and the availability of raw materials at comparatively lower prices. This has led to the expansion and establishment of new manufacturing facilities in the region. GCC has significantly contributed to the growth of the market in the region, owing to the developing chemical and automotive industries.
GCC Urea Market
The GCC market is expected to reach USD 0.59 billion by 2026, accounting for approximately 0.7% of global revenues.
COMPETITIVE LANDSCAPE
Key Industry Players
Leading Players Focus on Production Expansion to Meet Rising Demand
The presence of key players in this market is fairly fragmented in terms of production and supply chains. Major producers, such as SABIC, Yara International, and Nutrien, among others, are aiming to expand their production as well as distribution capabilities through acquisitions and merger strategies. As consumer-specific needs strongly influence the market, these manufacturers are focused on ensuring a continuous supply to gain a competitive edge over their competitors. Local players are also developing resilient distribution networks to compete against large players.
LIST OF KEY UREA COMPANIES PROFILED
- SABIC (Saudi Arabia)
- Qatar Fertilizer Company (Qatar)
- EuroChem (Switzerland)
- Yara International ASA (Norway)
- Nutrien AG (Canada)
- OCI N.V. (Netherlands)
- Acron Group (Russia)
- CF Industries Holdings (U.S.)
- HUBEI YIHUA CHEMICAL INDUSTRY CO., LTD. (China)
- China National Petroleum Corporation (CNPC) (China)
- Koch Fertilizer, LLC (U.S.)
- Coromandel International Limited (India)
KEY INDUSTRY DEVELOPMENTS
- April 2026: CF Industries entered a commercial agreement with PepsiCo for certified low-carbon UAN supplied to U.S. potato growers serving Frito-Lay (first commercial launch of CF Industries’ certified low-carbon UAN), signaling commercialization of lower-emission urea-based fertilizers within traceable food supply chains.
- August 2025: Acron updated its Urea Units 1-4 modernization program at Veliky Novgorod (USD 80 million investment; completion scheduled for 2026 and targeted total site capacity of approximately 2.5 million tons annually), signaling continued progress toward additional urea output and reinforcement of its position among Europe’s largest producers.
- July 2025: CF Industries started its carbon-dioxide dehydration and compression facility at Donaldsonville, Louisiana (up to two million metric tons of CO₂ sequestration annually and approximately 1.9 million tons of low-carbon ammonia production), establishing the feedstock platform subsequently used to manufacture certified low-carbon UAN and other urea-derived nitrogen products.
- December 2024: EuroChem Group AG announced the completion of the sale of its entire 50% interest in EuroChem Migao Limited, a Hong Kong company with fertilizer production and distribution operations in China, to a prospective purchaser on 31 December 2024.
- July 2024: SABIC Agri-Nutrients Company has received approval from Saudi Arabia's Ministry of Energy to allocate the necessary feedstock for constructing its 6th plant in Jubail Industrial City. The facility will produce 1.2 MMTA of low-carbon blue ammonia and 1.1 MMTA of urea. This project aligns with Saudi Arabia's Vision 2030 to advance clean energy production and export.
- December 2023: OCI entered into a binding agreement to sell Iowa Fertilizer Company to Koch Ag & Energy Solutions (USD 3.6 billion transaction covering the Wever, Iowa nitrogen complex producing urea and urea-derived products), signaling further portfolio restructuring and the planned transfer of OCI’s principal U.S. urea asset.
- March 2022: QAFCO signed an MoU with Hassad Food Company, which includes the allocation of Hassad Company to areas within its local farms for scientific research and allowing QAFCO to use its laboratories to analyze soil, water, and fertilizer samples, with the aim of monitoring the performance of agricultural inputs and improving the quality of production.
REPORT COVERAGE
The market report provides qualitative and quantitative insights on the market share, size, growth rate, and trend analysis by different segments. Along with this, the research report provides an elaborative analysis of the market dynamics and competitive landscape. Various key insights presented in this market analysis report include Porter’s five forces, recent industry developments, regulatory scenarios, and key industry trends. The report also highlights the competitive landscape between key players operating in this market.
Request for Customization to gain extensive market insights.
REPORT SCOPE & SEGMENTATION
| ATTRIBUTE | DETAILS |
| Study Period | 2021-2034 |
| Base Year | 2025 |
| Estimated Year | 2026 |
| Forecast Period | 2026-2034 |
| Historical Period | 2021-2024 |
| Growth Rate | CAGR of 3.6% from 2026 to 2034 |
| Unit | Value (USD Billion), Volume (Million Tons) |
| Segmentation | By Grade, Application, and Region |
|
By Grade
|
|
|
By Application
|
|
|
By Region
|
|
Frequently Asked Questions
Fortune Business Insights says that the market was valued at USD 85.33 billion in 2025 and is expected to reach USD 104.54 billion by 2034.
In 2025, the market value stood at USD 51.88 billion.
Growing at a CAGR of 3.6%, the market will exhibit considerable growth over the forecast period.
By application, the agriculture segment dominated the market in 2025.
Rising crop-nutrition requirement is driving the growth of the market.
Asia Pacific is expected to hold the highest market share.
SABIC, Yara International, and Nutrien AG are the key players in the market and have adopted strategies such as acquisition and capacity expansion for their growth in the market.


- 2021-2034
- 2025
- 2021-2024
- 250
-
(Offer valid till 15th Oct 2026)
Get 30-60 hrs Free Customization
Expand Regional and Country Coverage, Segments Analysis, Company Profiles, Competitive Benchmarking, and End-user Insights.


















Related Reports
-
US +1 833 909 2966 ( Toll Free )
-
Get In Touch With Us