 Download Free Sample




Get a Quote
Receive a tailored pricing based on your needs.
- Choose license type
- Multiple user options
- Custom scope & coverage
- Fast turnaround
"Smart Strategies, Giving Speed to your Growth Trajectory"
 Listen to Audio Version
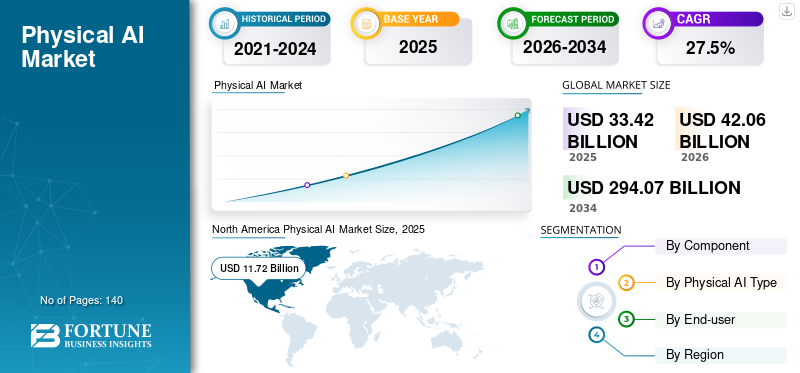
The physical AI market size was valued at USD 33.42 billion in 2025 and is projected to grow from USD 42.06 billion in 2026 to USD 294.07 billion by 2034, exhibiting a CAGR of 27.5% during the forecast period. North America dominated the global physical AI market with a market share of 35.06% in 2025. Physical AI is shifting automation from fixed programming toward adaptive systems that perceive, reason, and act across industrial and commercial environments.
Physical AI is a branch of artificial intelligence that enables machines and autonomous systems to perceive, understand, reason about, and act in the physical world. By combining AI models with sensors, physics-aware reasoning, simulation, and actuators, Physical AI allows systems such as robots, autonomous vehicles, drones, and intelligent machines to make decisions, execute physical actions, and adapt to changing real-world conditions under constraints such as physics, time, safety, and uncertainty.
Physical AI is moving enterprise AI from digital decision support into machines that sense, reason, act, and learn inside operating environments. According to the International Federation of Robotics (IFR), 542,000 industrial robots were installed worldwide in 2024, more than double the level a decade earlier. The installed base gives physical AI a large industrial foundation rather than a greenfield market.
The strategic shift is not simply “more robots.” It is the convergence of robotics, foundation models, simulation, edge computing, vision, and fleet orchestration. Google DeepMind introduced Gemini Robotics in March 2025, extending multimodal Gemini capabilities into robotic control. NVIDIA introduced GR00T N1 the same month, pairing a humanoid foundation model with simulation and synthetic-data tools.
The market includes hardware, software, and services that enable machines and systems to sense, understand, decide, and act in the physical world. It covers robotics, autonomous vehicles and machines, vision AI and smart spaces, and other specialized systems. Physical AI is used across manufacturing, automotive and transportation, logistics and warehousing, healthcare and life sciences, construction and infrastructure, agriculture, government and defense, and other industries. It combines artificial intelligence with sensors, computing, control systems, and automation tools to support real-time interaction, improve operational efficiency, and perform physical tasks with greater intelligence and independence.
Growing demand for industrial automation, autonomous systems, smart manufacturing, and AI-based decision-making is driving the market’s growth. NVIDIA Corporation, ABB Ltd, FANUC CORPORATION, and YASKAWA Electric Corporation are some of the top players in the market.
Physical AI is therefore a capital-allocation question: which workflows can generate durable productivity gains after integration, safety, maintenance, and workforce costs are included? In the coming years, utilization, reliability, interoperability, and recurring operating value will matter more than prototype novelty. Regional policy, labor availability, manufacturing density, and local technology ecosystems will further separate scalable programs from isolated pilots.
Download Free sample to learn more about this report.
 Global Market Size & Forecast
 Market Share
 Key Regional Highlights
North America
North America led the market, supported by strong AI development, advanced robotics companies, and high automation spending.
Asia Pacific
Asia Pacific is projected to record the highest CAGR, driven by rapid factory automation, electronics production, and AI infrastructure investment.
Europe
Europe holds a significant market share, supported by its strong manufacturing, automotive, robotics, and industrial automation base.
U.S.
The market was valued at around USD 9.89 billion in 2025, accounting for roughly 29.6% of global sales.
Japan
The market was valued at around USD 1.93 billion in 2025, accounting for roughly 5.8% of the global market.
Read More

Growing Use of Digital Twins and Simulation for Physical AI Development
Companies are increasingly using digital twins and simulation tools to train, test, and improve machines before using them in the real world. These tools create virtual copies of factories, warehouses, robots, vehicles, and other physical objects or parts. Developers can test robot movements, safety, navigation, robotic perception, and quality inspection without stopping real operations. Simulation also supports foundation models, reinforcement learning, computer vision, and multimodal sensor fusion by creating synthetic data for AI training. This wide technology stack helps companies reduce development time, improve safety, and deploy smarter machines faster across major industries.
According to the International Federation of Robotics (IFR), 74% of new industrial robot installations in 2024 were in Asia, highlighting the region’s large installed base supporting physical AI development. The dominant trend is vision-language-action, or VLA, models connecting perception, reasoning, and movement. During the forecast period, VLA architectures will become a core software layer for higher-variance robotic tasks, reducing dependence on task-specific programming.
Google DeepMind introduced Gemini Robotics in March 2025, while Figure introduced Helix in February 2025. Both moves signal a shift toward models interpreting environments and generating actions rather than classifying text or images.
Another trend is simulation-led commercial development. NVIDIA introduced GR00T N1 and supporting simulation frameworks in March 2025, emphasizing synthetic data and physics-based training. Digital environments will increasingly prepare systems before real-world deployment. Physical AI is moving from optimizing individual machines toward coordinating robots, schedules, routes, work queues, and human interventions.
Download Free sample to learn more about this report.
Rising Demand for Automation across Industries Drives Market Growth
Companies are using AI-powered robotics, autonomous robotics, vision AI, and smart machines to improve speed, accuracy, safety, and productivity. The use of autonomous systems, vehicles, and robots is increasing across factories, warehouses, transport networks, farms, hospitals, and construction sites. These technologies use artificial intelligence to perform repetitive, risky, and complex tasks with less human effort. Rising labor shortages and the need for real-time decisions are also supporting physical AI adoption. As investment increases across industries, the global physical AI market is expected to benefit from wider use of intelligent machines.
According to the International Federation of Robotics, 542,000 industrial robots were installed globally in 2024, while the global operational stock reached 4.66 million units, up 9% from 2023, confirming an established automation base. Labor scarcity is the immediate catalyst. IFR identifies staff shortages as a key driver for professional service robots, while logistics already represents a large operating application.
During the forecast period, labor-constrained manufacturers and logistics operators will accelerate adoption where physical AI executes repetitive tasks while handling greater environmental variation.
Another driver is model generalization. Google DeepMind introduced Gemini Robotics in March 2025, connecting multimodal reasoning with robotic action. NVIDIA introduced GR00T N1 the same month, pairing a humanoid foundation model with simulation and synthetic-data tools. Together, these developments shift robotics from fixed programming toward adaptable behavior.
Industrial networks, machine vision, edge computing, digital twins, and fleet software provide deployment foundations. Buyers can add intelligence without replacing every installed asset. Physical AI will increasingly be evaluated as a productivity layer over existing automation. Demand will come from factories, warehouses, inspection environments, and autonomous mobility systems where workflows produce data.
Market Drivers - Impact & CAGR Contribution (2026–2034)
| Rank | Market Drivers | Overall impact rank | CAGR contribution (2026–2034) | Impact: 2026-2028 | Impact: 2029-2031 | Impact: 2032-2034 |
|---|---|---|---|---|---|---|
| 1 | Rising demand for automation across manufacturing, logistics, automotive, and other industries is increasing the use of robots, autonomous machines, and smart systems. | High | 7.2% | High | High | High |
| 2 | Rapid advances in AI models, computer vision, edge AI, robot learning, and real-time decision-making are improving the performance of Physical AI systems. | High | 6.4% | High | High | High |
| 3 | Growing use of robots and autonomous machines in factories, warehouses, transport, and industrial operations is supporting wider market adoption. | High | 5.8% | Medium | High | High |
| 4 | Increasing use of digital twins, simulation, vision AI, and smart spaces is helping companies test, train, and deploy Physical AI systems faster. | High | 5.4% | Medium | High | High |
| 5 | Rising investments, partnerships, and product development by AI, robotics, and automation companies are expanding the Physical AI ecosystem. | Medium | 4.9% | Medium | High | High |
| 6 | Others (growing use in healthcare, agriculture, construction, government, defense, and other sectors) are creating new growth opportunities. | Medium | 4.6% | Low | Medium | High |
| Total Positive Growth Contribution | 34.30% | |||||
Source: Fortune Business Insights
Download Free sample For In-Depth Market Drivers & Impact Forecasts
High Integration Costs and Complex Deployment Limit Market Growth
The high cost and complexity of deploying physical AI systems can limit physical AI market growth. Companies often need advanced sensors, AI software, edge computing, and skilled technical teams to install and manage these solutions. Integrating with existing machines, networks, and control systems can be difficult. This process often requires significant spending on system design, testing, programming, training, and maintenance. Small and medium-sized companies may find these costs difficult to manage. Complex integration can also increase deployment time and technical risks, slowing adoption in cost-sensitive industries.
The largest restraint remains reliability. Physical systems encounter contact, obstruction, sensor degradation, changing layouts, network latency, and human activity that benchmarks do not fully capture. Scaled deployments will require documented safety cases, integration testing, human-override procedures, and lifecycle controls before broader rollout across regulated, safety-sensitive, and customer-facing operating environments.
Physical AI must connect with manufacturing execution systems, warehouse management systems, industrial controls, cybersecurity, maintenance, and workforce procedures. Each interface adds engineering effort, testing, and failure points. Robots need interaction data across varied environments, yet collecting it remains slower than collecting digital training data. Simulation and synthetic data reduce the burden but cannot eliminate physical validation in production environments.
General-purpose machines carry sensors, compute, actuators, batteries, and maintenance requirements. Buyers will therefore demand evidence that machines sustain productive utilization across changing tasks.
Market Restraints - Impact & Negative CAGR Contribution (2026–2034)
| Rank | Market Restraints | Overall impact rank | Negative CAGR contribution (2026–2034) | Impact: 2026-2028 | Impact: 2029-2031 | Impact: 2032-2034 |
|---|---|---|---|---|---|---|
| 1 | High costs of robots, sensors, AI hardware, software, integration, and maintenance can limit adoption, especially among small and medium-sized companies. | High | -2.1% | High | High | Medium |
| 2 | Safety, reliability, and regulatory concerns can slow the deployment of robots, autonomous vehicles, and other Physical AI systems in real-world environments. | High | -1.8% | High | High | Medium |
| 3 | Shortage of skilled professionals and difficulty in connecting Physical AI systems with existing machines and software increase deployment complexity. | High | -1.5% | High | Medium | Medium |
| 4 | Others (cybersecurity risks, data privacy concerns, uncertain return on investment, and long deployment cycles) can reduce adoption in some industries. | Medium | -1.4% | Medium | Medium | Low |
| Total Negative Growth Impact | -6.80% | |||||
Source: Fortune Business Insights
Download Free sample For In-Depth Market Restraints & Risk Analysis
Growing Use of Physical AI in Healthcare Creates New Growth Opportunities
The healthcare sector offers a strong growth opportunity as hospitals and care centers are starting to use smart machines, service robots, and vision-based systems to support doctors, nurses, and patients. Humanoid robots can support routine hospital tasks and may also assist with patient movement, delivery, rehabilitation, and basic care activities. Physical AI can reduce the workload of medical staff and improve the speed of daily operations. Growing healthcare demand, aging populations, and staff shortages are expected to support wider use of intelligent machines. As hospitals invest in automation, companies can expand into new healthcare applications and services.
Manufacturing is the clearest expansion area. Existing robotic cells provide structured environments. Physical AI can extend automation into kitting, inspection, machine tending, mixed-model assembly, and exceptions.
Logistics is the second major opportunity because warehouses generate dense transaction data and measured cycle times. Adaptive manipulation will broaden automation. Healthcare will expand selectively by workflow. Medical robotics is growing, but clinical validation will constrain unsupervised autonomy. Pharmaceutical manufacturing offers an earlier bridge because production environments are standardized and repeatable.
Construction, agriculture, utilities, and infrastructure are the frontier. Vision systems and autonomous machines address inspection, hazardous work, monitoring, and movement. Service models create opportunity. IFR reports growing robot-as-a-service adoption, allowing enterprises to procure capacity through recurring arrangements instead of owning every asset.
Physical AI is fragmenting into a layered market spanning hardware, intelligence, services, machine categories, and end-user workflows. According to the International Federation of Robotics (IFR), industrial robotics provides the mature foundation while service and medical robotics broaden the operating environment. The question is where intelligence expands viable enterprise tasks.
Enterprise buyers will increasingly evaluate physical AI through task economics, safety, interoperability, utilization, and deployment speed rather than robot specifications alone.
Hardware Leads Due to Strong Demand for Physical AI Infrastructure
Based on component, the market is divided into hardware, software, and services.
Hardware
In 2025, hardware led the market with a 55.2% share as robots, autonomous machines, and smart spaces require processors, sensors, cameras, controllers, actuators, and edge computing devices to operate. Hardware also carries a high value per installation because several physical parts are needed to build and deploy these systems.
Hardware remains the physical foundation of physical AI, spanning robot bodies, sensors, actuators, batteries, edge processors, connectivity, safety, and end effectors. Demand is moving beyond fixed-function machines toward platforms designed for richer perception, manipulation, software updates, and collaboration. The distinction is between hardware optimized for one motion and hardware supporting changing intelligence.
Software
Software is becoming the intelligence layer because physical AI must perceive environments, interpret instructions, plan actions, and control movement. Google DeepMind introduced Gemini Robotics, connecting multimodal reasoning with robotic action in physical environments. NVIDIA introduced GR00T N1 the same month, combining a humanoid foundation model with simulation and synthetic-data tooling for robot development.
The value pool is shifting toward software that transfers capabilities across tasks. Buyers will scrutinize portability, ownership, latency, cybersecurity, exceptions, evaluation, and integration. The question is whether software reduces engineering effort while improving execution.
The software segment is projected to grow at the highest CAGR of 29.6% during the forecast period as companies are increasing their use of AI models, simulation tools, perception software, robot learning, and autonomous control platforms. Software can also be updated and added to existing machines more easily, which supports faster adoption across industries.
Services
Services will shift from installation support toward recurring operational management as physical AI scales across facilities. Services turn physical AI capability into reliable operations. Integration, site engineering, safety validation, workflow redesign, operator training, maintenance, and fleet management remain essential because intelligent machines must connect with existing controls and enterprise systems. IFR identifies robot-as-a-service as an expanding procurement model.
Robotics is the Dominating Physical AI Type Driven by Wide Industrial Adoption
Based on physical AI type, the market is segmented into robotics, autonomous vehicles & machines, vision AI & smart spaces, and others.
Robotics
In 2025, robotics held the largest share (46.9%) of the physical AI market as industrial robots, collaborative robots, mobile robots, and service robots already have a large installed base across factories, warehouses, and other workplaces. According to the International Federation of Robotics, about 4.66 million industrial robots were operating worldwide in 2024, showcasing the large existing base for robotics. Enterprises will operate hybrid robot portfolios combining fixed automation for stable tasks with adaptive machines for variability.
Robotics remains the broadest physical AI category, covering industrial arms, collaborative robots, mobile systems, humanoids, medical machines, and specialist platforms. Conventional robots will remain dominant where precision, repeatability, and throughput outweigh flexibility. General-purpose machines will address variable objects, layouts, sequences, and exceptions.
Autonomous Vehicles & Machines
Autonomous vehicles and machines extend physical AI into warehouses, roads, ports, farms, mines, and industrial sites. They combine perception, localization, planning, control, and fleet management. Adoption depends on whether environments can be mapped, monitored, and expanded.
Waymo’s international strategy shows that autonomy extends beyond vehicle technology into mapping, fleet operations, regulation, customer interfaces, and safety validation. Mobileye’s agreement to acquire Mentee Robotics shows convergence between autonomous-driving expertise and humanoid robotics.
Autonomous machines will scale fastest where operating environments can be bounded, monitored, validated, and expanded progressively.
Vision AI & Smart Spaces
The vision AI & smart spaces segment is expected to grow at the highest CAGR of 30.2% during the forecast period as companies are using AI cameras, computer vision, edge AI, and smart monitoring systems to understand physical environments in real time. These systems can often be added to existing factories, warehouses, buildings, and public spaces without replacing the full physical infrastructure, which supports faster expansion.
Vision AI and smart spaces move intelligence beyond individual machines into factories, warehouses, campuses, hospitals, stores, and infrastructure. Cameras, depth sensing, edge processors, spatial models, and digital twins can augment existing assets. Strong applications include inspection, safety monitoring, asset tracking, quality control, and process observation.
This category also creates a governance burden because smart environments observe people and operations. Buyers will require disciplined retention, access controls, cybersecurity, and model-training rules. Opportunity is strongest where visual information triggers operational action.
Vision AI will expand fastest where existing sensing can be converted into closed-loop operational decisions rather than standalone alerts.
To know how our report can help streamline your business, Speak to Analyst
Manufacturing is the Leading End-user Due to High Automation Use and Significant Investment
Based on end-user, the market is subdivided into manufacturing, automotive & transportation, logistics & warehousing, healthcare & life sciences, construction & infrastructure, agriculture, government & defense, and others.
Manufacturing
In 2025, the manufacturing segment dominated with a 29.0% market share. Factories are already using a large number of robots, machine vision systems, automated equipment, and smart production technologies. The electronics, automotive, metal, machinery, food, and other manufacturing industries continue to invest in automation to improve productivity, quality, and safety, with IFR reporting 542,076 industrial robot installations worldwide in 2024.
Manufacturing remains the primary proving ground because factories provide repeatable processes, dense data, and measurable throughput. Existing automation creates a natural platform for additional intelligence. The next adoption cycle will extend into inspection, kitting, machine tending, intralogistics, assembly, and exception handling.
BMW’s humanoid robotics work illustrates flexible automation inside established production environments. The implication is broader task coverage, not replacement of mature automation. Manufacturers will favor adaptive systems where variability makes conventional programming expensive.
Manufacturing will lead scaled adoption where adaptive systems improve flexibility without forcing wholesale replacement of established automation.
Automotive & Transportation
Automotive connects industrial robotics with autonomous mobility. Plants provide structured environments for inspection, movement, assembly support, and tending, while transportation adds mapping, perception, fleet intelligence, and autonomous operations.
Waymo’s Tokyo initiative shows how autonomous mobility requires local partners, mapping, regulatory preparation, and operating discipline. Mobileye’s transaction reinforces convergence between vehicle autonomy and embodied intelligence.
Automotive will remain a strategic bridge between industrial robotics, autonomous mobility, and embodied intelligence.
Logistics & Warehousing
Logistics and warehousing have a strong physical AI fit because movement, picking, sorting, scanning, and inspection generate measurable transactions. Mobile robots automate transport, while newer systems target manipulation and exceptions. Warehouses provide controlled environments where autonomy can be monitored, measured, and expanded. IFR identifies transportation and logistics as a major professional service robotics application.
Figure’s humanoid work illustrates adaptable handling. Adoption will progress from structured movement toward more complex manipulation, with vision systems and fleet orchestration connecting machines into workflow systems.
Logistics will move from transport automation toward adaptive handling as manipulation reliability improves.
Healthcare & Life Sciences
Healthcare and life sciences will adopt physical AI selectively because safety, validation, and workflow reliability are critical. IFR identifies medical robotics across surgery, rehabilitation, diagnostics, and laboratory automation.
Opportunities include hospital logistics, sterile-environment monitoring, laboratory handling, and assistive systems. Pharmaceutical manufacturing offers a nearer-term bridge because production processes are structured and quality-controlled. Clinical environments will move more slowly where autonomy affects patient outcomes. Healthcare adoption will advance fastest where physical AI augments professionals or automates controlled operational processes.
Construction & Infrastructure
Construction and infrastructure represent a harder physical AI frontier because terrain, materials, weather, and workflows change continuously. Early applications will center on surveying, inspection, monitoring, prefabrication, autonomous equipment, and hazardous-task substitution.
Vision AI can enter before full autonomy because it augments existing processes. Digital twins can support pre-deployment testing, while autonomous machines can address repeated routes and maintenance. Utilities offer similar opportunities through distributed-asset inspection. Infrastructure adoption will concentrate first on repeatable inspection and maintenance workflows before fully autonomous construction.
Agriculture
Agriculture is projected to record the highest CAGR of 31.7% for the forecast period as farms are increasingly adopting autonomous machines, drones, robotic equipment, AI vision, and precision farming systems. Rising labor shortages, the need to improve crop output, and demand for more efficient use of water, fertilizer, and other resources are expected to support faster physical AI adoption in agriculture.
Agriculture will adopt physical AI where labor scarcity, crop value, and precision requirements support automation. IFR identifies agricultural robots as an established service-robot category, but conditions differ materially from factories. Vision systems support crop monitoring, treatment, harvesting, and disease identification, while autonomous machines extend capabilities into field operations.
Seasonality remains the central economic constraint. Multifunction platforms, flexible leasing, and service models will become more relevant. Large farms and controlled environments will lead where workflows are standardized. Agriculture will prioritize multifunction autonomy that raises annual asset utilization across seasonal operating cycles.
Government & Defense
Government and defense will deploy physical AI across surveillance, logistics, inspection, maintenance, and hazardous work. Commercial robotics provides the technology base, while government users add requirements for cybersecurity, resilient communications, secure supply chains, testing, and human control.
Japan’s Ministry of Economy, Trade and Industry is advancing AI-and-robotics policy work focused on social implementation and robot-friendly environments. This shows how physical AI is becoming part of industrial competitiveness and national capability planning. Government and defense adoption will favor secure, resilient architectures that combine commercial technology scale with mission-specific controls.
By geography, the market is categorized into North America, South America, Asia Pacific, Europe, and the Middle East & Africa.
North America Physical AI Market Size, 2025 (USD Billion)
To get more information on the regional analysis of this market, Download Free sample
North America holds the largest physical AI market share due to strong AI development, advanced robotics companies, high automation spending, and early adoption of autonomous systems. The U.S. also has a large base of technology firms, system integrators, cloud providers, and industrial users. Strong investment in manufacturing, defense, logistics, healthcare, and autonomous mobility further supports wide use of these solutions.
The region has a mature robotics base, while the United States provides deep concentrations of technology developers and deployment ecosystems. Adoption will center on manufacturing flexibility, warehousing, autonomous transportation, inspection, infrastructure, and defense applications where integration can produce measurable operating improvements across enterprise facilities and networks.
To know how our report can help streamline your business, Speak to Analyst
The U.S. market was valued at around USD 9.89 billion in 2025, accounting for roughly 29.6% of the global sales. The United States remains the region’s central physical AI market, supported by advanced computing, robotics research, logistics, manufacturing, autonomous driving, and venture-backed development. The country retains a substantial industrial-robot installed base. Demand will increasingly favor systems connecting perception, planning, machine control, and enterprise workflows. Manufacturing, warehousing, mobility, infrastructure, and defense will remain important deployment environments across major enterprise facilities and operating networks.
Asia Pacific is expected to grow at the highest CAGR over the projected timeline due to rapid factory automation, strong electronics production, rising robot use, and increasing investment in AI infrastructure. China, Japan, South Korea, and India are expanding smart factories, autonomous machines, logistics automation, and vision AI. Growing manufacturing activity and government support for advanced technologies are also creating strong demand across the region.
Asia Pacific remains the center of global robotics deployment and manufacturing activity. The region accounts for most new industrial-robot installations. China, Japan, South Korea, and India combine manufacturing scale with expanding AI and robotics ecosystems. Physical AI competition will increasingly connect robot production, semiconductors, foundation models, simulation, and industrial software. Policy support will reinforce localization and commercialization across industrial markets, emerging supply chains, and technology ecosystems.
Japan's market was valued at around USD 1.93 billion in 2025, accounting for roughly 5.8% of the global market. Japan combines decades of robotics expertise with a growing policy focus on AI-enabled machines and societal implementation. The country retains one of the world’s largest industrial-robot operating bases. Physical AI will expand across manufacturing, logistics, healthcare, agriculture, and services. Buyers will value reliability, safety, compact automation, human-machine collaboration, and technology suited to labor-constrained operating environments as robotics expands into physical workflows across society and industry.
China’s market was valued at USD 4.43 billion in 2025, roughly 13.3% of global sales, making it one of the largest globally.
The Indian market was valued at USD 1.02 billion in 2025, accounting for roughly 3.1% of global revenues. India is expanding its physical AI ecosystem through smart factories, logistics automation, autonomous machines, industrial vision, and related applications. Local manufacturers, technology providers, research institutions, and policy programs are supporting commercialization. Competitive advantage will depend on manufacturing scale, component integration, software capabilities, and deployment speed across domestic supply chains.
Europe holds a significant market share fueled by a strong manufacturing, automotive, robotics, and industrial automation base. The region benefits from high robot density, advanced engineering skills, and wide use of smart factory systems. Germany, France, Italy, and other countries continue to invest in digital production, robotics, machine vision, and intelligent industrial systems.
Europe combines a deep industrial automation base with pressure to improve productivity, resilience, and manufacturing competitiveness. Western Europe maintains high robot density relative to other major regions. Germany remains the principal industrial hub, while Italy, France, Spain, and the United Kingdom contribute distinct ecosystems. Physical AI adoption will emphasize safety, energy efficiency, workforce productivity, nearshoring, and regulatory alignment across advanced industrial environments and supply chains.
The U.K. market was valued at USD 1.44 billion in 2025, accounting for roughly 4.3% of the global market. The United Kingdom has a smaller industrial-robotics base but benefits from strong research, software, logistics, engineering, and autonomous-systems capabilities. Government policy increasingly links robotics with productivity and innovation. Physical AI adoption will focus on logistics, advanced manufacturing, healthcare, infrastructure, and autonomous systems, particularly where flexible procurement models can support commercial deployment across logistics, manufacturing, and healthcare.
Germany's market reached USD 2.11 billion in 2025, around 6.3% of global sales. Germany remains Europe’s leading industrial-robotics market, supported by automotive, machinery, electronics, chemicals, and industrial suppliers. Physical AI will extend established automation into inspection, flexible handling, machine tending, intralogistics, and collaborative workflows. BMW’s humanoid initiatives illustrate growing interest in adaptive machines. Buyers will prioritize reliability, worker integration, safety engineering, and compatibility with existing factory controls and production software across advanced German manufacturing facilities and operating teams.
The Middle East & Africa region is expected to record the second-highest CAGR as governments and businesses increase spending on smart cities, automation, defense systems, and digital infrastructure. GCC countries are investing in AI, autonomous transport, smart buildings, logistics, and industrial projects. The growing interest in advanced technologies, combined with a smaller current market base, supports faster physical AI adoption across the region.
Middle East and Africa will develop physical AI demand around logistics, energy, infrastructure, agriculture, inspection, and security. Gulf economies are emphasizing smart infrastructure and autonomous systems, while African markets present opportunities in mining, logistics, and agriculture. Adoption will depend on integration partners, financing, technical capabilities, and workforce readiness. Imported platforms with strong local support will have practical advantages for deployments.
The GCC market reached USD 0.68 billion in 2025, accounting for roughly 2.0% of global revenues.
Latin America remains an emerging physical AI market, with adoption concentrated in automotive, logistics, agriculture, mining, and industrial processing. Mexico provides the strongest manufacturing platform, while Brazil offers broader opportunities across agriculture, resources, and logistics. Nearshoring will support automation investment, particularly where export manufacturers seek consistent quality and capacity. System integration, financing, technical talent, and service networks will determine deployment readiness as supply chains modernize.
South America holds a smaller share of the market as automation levels, AI infrastructure, and technology spending remain lower than in North America, Europe, and Asia Pacific. Physical AI adoption is mainly concentrated in Brazil and selected industries such as manufacturing, agriculture, mining, automotive, and logistics. Limited investment, lower robot use, and slower digital adoption restrict the region’s overall market size.
Brazil’s market was valued at USD 1.10 billion in 2025, accounting for roughly 3.3% of the global market.
Robotics and AI Partnerships Increase Market Competition, Enabling Companies to Build Better Systems
Competition in the physical AI market is growing as companies develop smarter robots, autonomous machines, vision AI systems, and software for real-world use. Leading companies are investing in AI models, edge computing, simulation, digital twins, safety tools, and robot learning to improve performance and reduce deployment time. Partnerships between AI firms, robot makers, manufacturers, and software providers are also increasing. These partnerships help companies combine skills, improve products, and reach more industries.
Physical AI competition is consolidating around four tiers: Leaders, Visionaries, Challengers, and Niche Players. The decisive battleground is moving upward from mechanical differentiation toward intelligence, simulation, safety, data, and deployment.
Leaders
NVIDIA is establishing a platform position by connecting accelerated computing, simulation, world models, robotics software, and partner ecosystems. Its March 2026 robotics announcements brought industrial robot makers, humanoid developers, surgical robotics companies, and autonomous-machine specialists into a physical AI stack. Amazon represents a different leadership model, combining robotics deployment with software that coordinates warehouse operations. The strategic advantage is workflow integration rather than robot design.
Visionaries
Google DeepMind and Figure are advancing general-purpose embodied intelligence. Google DeepMind’s Gemini Robotics family connects multimodal reasoning with robotic action, while Figure’s Helix program focuses on generalist humanoid control. Their positioning centers on model adaptability, dexterity, embodied reasoning, and transfer across robotic embodiments. In July 2026, Google DeepMind advanced whole-body control, dexterity, and multi-robot collaboration through Gemini Robotics 2.
Challengers
Mobileye is extending autonomous-driving expertise into humanoid robotics through its agreement to acquire Mentee Robotics in January 2026. Agility Robotics is commercializing Digit around industrial and logistics workflows, emphasizing human-compatible operation and deployment readiness. The challenger strategy is narrower than an infrastructure stack but stronger where domain expertise accelerates adoption.
Niche Players
Specialists across sensors, actuators, industrial controls, safety, simulation, digital twins, and system integration remain strategically important. Their products often become embedded inside larger platforms, creating influence without owning the complete stack.
Taken together, these moves represent a structural shift from standalone robot vendors toward ecosystem competition. The winning position will increasingly depend on interoperability, deployment data, safety evidence, software portability, and recurring workflow value.
The physical AI market research report provides an assessment of the market size, forecasts, segmentation, growth drivers, challenges, key trends, and major developments. The report covers key components, including hardware, software, and services used in physical AI systems. It also studies major types, including robotics, autonomous vehicles and machines, vision AI and smart spaces, and other systems. In addition, the report examines demand across manufacturing, automotive and transportation, logistics and warehousing, healthcare and life sciences, construction and infrastructure, agriculture, government and defense, and other industries. The report also analyzes market share, product launches, partnerships, mergers and acquisitions, investments, business strategies, and the leading companies operating across major regions globally.
Request for Customization to gain extensive market insights.
| ATTRIBUTE | DETAILS |
| Study Period | 2021-2034 |
| Base Year | 2025 |
| Estimated Year | 2026 |
| Forecast Period | 2026-2034 |
| Historical Period | 2021-2024 |
| Growth Rate | CAGR of 27.5% from 2026-2034 |
| Unit | Value (USD Billion) |
| Segmentation | By Component, Physical AI Type, End-user, and Region |
| By Component |
|
| By Physical AI Type |
|
| By End-user |
|
| By Region |
|
Fortune Business Insights says that the global market value stood at USD 33.42 billion in 2025 and is projected to reach USD 294.07 billion by 2034.
In 2025, North America’s market value stood at USD 11.72 billion.
The market is expected to grow at a CAGR of 27.5% over the forecast period.
By end-user, the manufacturing segment leads the market.
Growing automation demand, labor shortages, advances in generative AI and robotics, and increasing investment in smart factories and autonomous systems are some of the key factor driving market growth.
NVIDIA Corporation, ABB Ltd, FANUC CORPORATION, and YASKAWA Electric Corporation are top players in the market.
North America held the largest market share in 2025.
Rising deployment of AI-enabled robots, autonomous machines, edge AI, and intelligent vision systems across industrial and commercial operations will support product adoption.
Get 30-60 hrs Free Customization
Expand Regional and Country Coverage, Segments Analysis, Company Profiles, Competitive Benchmarking, and End-user Insights.




















Related Reports
Get In Touch With Us
US +1 833 909 2966 ( Toll Free )
Receive a tailored pricing based on your needs.
Discuss your questions with our industry experts.
Have questions? Get quick answers before you purchase.

