Piezoelectric Materials Market Size, Share & Industry Analysis, By Material (Piezoceramics {PZT, Lead-free Ceramics, and Others}, Piezopolymers, Piezocomposites, and Others), By Application (Actuators, Motors, Transducers, Sensors, SONAR, Generators & Transformers, Acoustic Devices, Resonators, and Others), By End-use Industry (Automotive, Healthcare, IT & Telecom, Consumer Goods, Aerospace & Defense, and Others), and Regional Forecast, 2026-2034
 Download Free Sample

(Offer valid till 30th Sep 2026)

Piezoelectric Materials Market Size and Future Outlook
 Listen to Audio Version
The global piezoelectric materials market size was valued at USD 1.98 billion in 2025. The market is projected to grow from USD 2.10 billion in 2026 to USD 3.30 billion by 2034, exhibiting a CAGR of 5.9% during the forecast period. Asia pacific dominated the with a market share of 46.46% in 2025.
Piezoelectricity is a property exhibited by few materials, which produces an electric field when a force is applied. On the other hand, when an electric field is applied across the material, it displays deformation in its dimensions. These materials convert mechanical energy to electrical energy and vice versa. Due to this property, they are referred to as transducers. These materials use piezoelectricity to measure changes in speed, strain, stress, force, or heat by converting the differential in energy into electrical charge. Based on this effect, such materials find application in producing and detecting sound and frequency, SONAR, ignition devices, and pressure & displacement measurement systems.
Currently, piezoelectric devices employ a wide variety of materials such as Rochelle salt, quartz crystal, ceramics, macro-fiber composites, polymers, flexoelectric materials, and ferroelectrets. The selection of material for different applications is based on properties such as stability, consistency, malleability, high input-to-output ratio, and heat & humidity resistance. Primarily, quartz crystals were employed in piezoelectric devices. However, its inability to react at low voltages and function at temperatures above 300ᵒC led to its replacement by modern materials such as piezo composites and piezoceramics.
The consumer goods sector is a significant driver of the market. Growing purchasing power, high living standards, and rapid urbanization in several developed and developing countries are expected to drive the consumer goods sector, thereby driving product demand in the coming years.
PI Ceramics GmbH, L3Harris Technologies, Inc., CeramTec, TDK Corporation, and Solvay are key players operating in the market. The companies have modified their production plants to accommodate the growing demand from the healthcare industry. They have also developed novel products in collaboration with healthcare electronics manufacturers.
For instance, PI Ceramics developed piezoceramics that enable precise liquid handling for in vitro diagnostics for early diagnosis and disease detection.
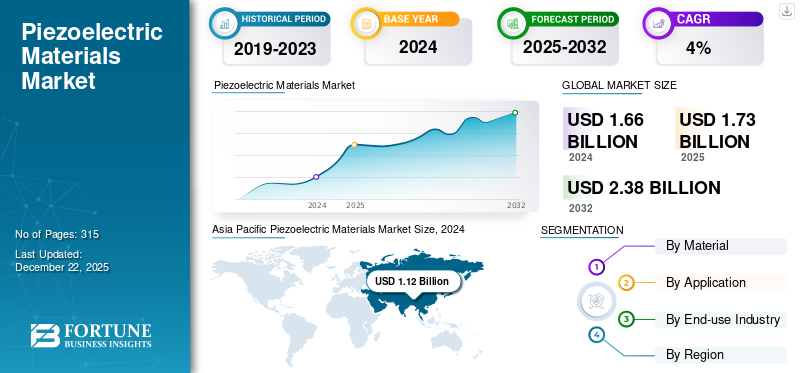
Download Free sample to learn more about this report.
Piezoelectric Materials Market Trends
Development of Lead-Free Piezoceramics has Emerged as a Growing Trend in Market
The development of lead-free piezoelectric ceramics has emerged as a key trend in the global market, driven by increasing environmental regulations and sustainability-focused product development. Conventional PZT-based materials offer strong piezoelectric performance but contain lead, creating compliance and health-related concerns. As a result, manufacturers and research institutions are investing in alternatives such as barium titanate, potassium sodium niobate, and sodium bismuth titanate-based ceramics. Although lead-free piezoelectric materials still face challenges related to performance consistency, durability, and scalability, ongoing innovation is improving their commercial viability. This trend is expected to accelerate as industries prioritize safer, regulatory-compliant, and environmentally sustainable material solutions.
MARKET DYNAMICS
Market Drivers
Download Free sample to learn more about this report.
Increasing Demand for Automation in End-Use Industries to Boost Market Growth
End-use industries such as automotive and electronic manufacturing have pushed for automation in their manufacturing lines. This push has increased demand for devices such as sensors, transducers, actuators, and motors to run the production line smoothly. As these devices use properties endowed by the product materials to measure various quantities such as pressure, strain, acceleration, and acoustic intensity, the demand for such materials is projected to expand considerably with the increasing dependence of industries on automation.
Over the years, major manufacturing companies have expanded their investments in introducing automation systems as an effective method to minimize running costs during development. The growing importance of automation in manufacturing industries to improve productivity and minimize lead time is projected to encourage the use of sensors, transducers, actuators, and motors. This is anticipated to boost the demand for piezoelectric materials during the forecast period.
Market Drivers - Impact & CAGR Contribution (2026–2034)
| Rank | Market Drivers | Overall Impact Rank | CAGR Contribution (2026–2034) (2026-2034) |
Impact: 2026-2028 | Impact: 2029-2031 | Impact: 2032-2034 |
|---|---|---|---|---|---|---|
| 1 | Rising adoption of piezoelectric materials in consumer electronics, wearables, haptics, acoustic devices, and smart devices | High | 2.20% | High | High | Medium |
| 2 | Increasing use in automotive and electric vehicles for sensors, actuators, fuel injection systems, safety systems, and battery monitoring | High | 1.90% | Medium | High | High |
| 3 | Growing demand from healthcare applications, including ultrasound imaging, medical diagnostics, surgical tools, and wearable health monitoring devices | Medium-High | 1.60% | Medium | High | High |
| 4 | Expansion of industrial automation, robotics, IoT sensors, vibration monitoring, and predictive maintenance applications | Medium | 1.40% | Medium | Medium | High |
| 5 | Energy harvesting and sustainability initiatives supporting self-powered sensors, smart infrastructure, and low-power electronic devices | Medium-Low | 1.00% | Low | Medium | High |
| 6 | Others: aerospace and defense applications, telecom components, research in lead-free materials, miniaturization, and smart infrastructure | Low | 0.80% | Low | Medium | Medium |
| Total Positive Growth Contribution | 8.90% | |||||
Source: Fortune Business Insights
Rising Incorporation of Piezoelectric Materials in Daily Use Consumer Goods to Drive Market Growth
The consumer goods sector is driving demand for piezoelectric materials as manufacturers integrate smarter, more responsive, and energy-efficient features into everyday devices. These materials are increasingly used in smartphones, wearables, gaming accessories, remote controls, and household appliances to enable touch sensing, pressure response, tactile feedback, and compact energy-harvesting capabilities. Their ability to function reliably in small spaces makes them suitable for miniaturized electronics, while energy generation from movement or pressure can support longer battery life and improved sustainability. Piezoelectric materials also enhance durability and product performance under frequent use. Overall, they help companies differentiate products through better interactivity, efficiency, reliability, and innovative design.
Market Restraints
Environmental Regulations Associated with Lead-Based Products to Hamper Market Growth
Environmental regulations are expected to restrain the growth of the global market due to the industry’s dependence on lead-based compounds including lead zirconate titanate, which deliver strong performance but raise environmental and health concerns. Regulations such as EU RoHS and REACH restrict hazardous substances, increasing compliance pressure on manufacturers. Although lead-free alternatives are being developed, they often face limitations in efficiency, durability, and thermal stability, especially for aerospace, defense, and medical applications. High R&D costs, regional regulatory differences, and product redesign requirements further increase operational complexity, making environmental compliance a key market restraint.
Market Restraints - Impact & Negative CAGR Contribution (2026–2034)
| Rank | Market Restraints | Overall Impact Rank | Negative CAGR contribution (2026–2034) (2026-2034) |
Impact: 2026-2028 | Impact: 2029-2031 | Impact: 2032-2034 |
|---|---|---|---|---|---|---|
| 1 | Environmental regulations restricting the use of lead-based piezoelectric materials such as PZT | High | -1.20% | Medium | High | High |
| 2 | High manufacturing costs due to complex processing, sintering, poling, precision shaping, metallization, and quality testing | Medium-High | -0.90% | High | Medium | Medium |
| 3 | Performance and commercialization challenges of lead-free piezoelectric alternatives compared with conventional PZT materials | Medium | -0.60% | Medium | Medium | Low |
| 4 | Others: raw material price volatility, supply-chain dependency, tariff exposure, qualification delays, and limited supplier base | Low | -0.30% | Low | Low | Medium |
| Total Negative Growth Impact | -3.00% | |||||
Source: Fortune Business Insights
Market Opportunities
Advances in Energy Harvesting Using Piezoelectric Materials Create Market Growth Opportunities
Energy harvesting and sustainability initiatives are expected to create strong growth opportunities for the global market. Piezoelectric materials can convert mechanical stress, vibrations, movement, and pressure into electrical energy, making them suitable for low-power and remote applications. They can be integrated into industrial machinery, vehicles, smart walkways, bridges, buildings, wearable devices, and IoT sensors to support self-powered or energy-efficient systems. Rising focus on renewable energy, reduced fossil fuel dependence, and environmentally friendly technologies is encouraging investment in piezoelectric energy harvesting solutions. As conversion efficiency, durability, and lead-free material development improve, these applications are expected to drive piezoelectric materials market growth.
Market Challenges
High Manufacturing Costs Limit Piezoelectric Material Adoption
High manufacturing costs remain a key challenge for the global market. Production involves complex processes such as high-purity raw materials preparation, calcination, sintering, poling, precision shaping, metallization, and rigorous quality testing. Advanced materials such as piezocomposites, lead-free ceramics, and specialty single crystals require tighter process control, specialized equipment, and higher R&D investment, increasing overall production costs. In addition, manufacturers serving medical, aerospace, defense, and precision electronics applications must meet strict performance and reliability standards, further raising certification and testing expenses. These cost pressures can limit adoption of piezoelectric materials in price-sensitive applications, slowing broader market penetration.
TRADE PROTECTIONISM AND GEOPOLITICAL IMPACT
Policies such as the U.S.-led semiconductor export controls and China's retaliatory mineral restrictions directly affect the piezoelectric material availability. Tariffs set by the U.S. further complicate cross-border trade, increasing costs for manufacturers reliant on global supply chains.
Segmentation Analysis
By Material
Piezoceramics Segment to Hold Dominant Share in Market Due to its Excellent Piezoelectric Properties
Based on material, the market is classified into piezoceramics, piezopolymers, piezocomposites, and others. Piezoceramics are further segregated into lead zirconate titanate (PZT), lead-free ceramics, and others.
The piezoceramics segment is expected to dominate and captured 70.4% of the market share in 2025 due to its excellent piezoelectric properties, including high sensitivity and operating temperature. The consumption of PZT is increasing for the manufacturing of transducers and actuators, as the performance of PZT can be easily modified based on the usage of doping materials. While doping with niobium produces soft-PZT, which increases its response capabilities, doping with iron forms hard-PZT, which shows negligible hysteresis in the piezoelectric response. Such adaptability of piezoelectric ceramic materials has resulted in their large-scale consumption in the electronics and automotive sectors.
On the other hand, piezocomposites segment is likely to grow with a substantial CAGR of 7.8% during the forecast period and are swiftly gaining market share as they are preferable for application in ultrasonic equipment, non-destructive testing, and underwater acoustics. Composites offer smaller acoustic impedance than piezoceramics, are more plastic, and can better adapt to mechanical loads. They possess better piezoelectric sensitivity and electromechanical activity and thus are considered to be effective alternatives to piezoceramics.
By Application
Sensors Segment to Grow with Prominent CAGR Due to Its Application in Various Fields
In terms of application, the market is segmented into actuators, motors, transducers, sensors, SONAR, generators & transformers, acoustic devices, resonators, and others.
The sensors segment is expected to grow at a considerable CAGR owing to its application in various fields, including automatic vehicles, manufacturing lines, and consumer electronics. Sensors detect the change in energy and convert the difference into electrical signals, which are used to make necessary changes in the system. For instance, the TV's remote control has a pressure sensor, which detects the pressure on a button and converts it into an electrical signal that activates the IR blaster present on the remote. Inside the television unit, the IR sensor detects the change in energy and converts it into a digital signal, providing control of the unit. The automotive and healthcare sectors are significant drivers of the piezoelectric sensors market. In automotive applications, piezoelectric sensors are used in collision detection, active safety systems, and tire pressure monitoring. In healthcare, they are used in ultrasonic imaging, pacemakers, and hearing aids.
On the other hand, the actuators segment is likely to grow with a substantial CAGR of 5.2% during the forecast period. An actuator converts electrical signals sent by the system or user into mechanical energy to control the designated part to perform a certain action in the manufacturing line. Thus, the actuators segment is expected to account for the largest piezoelectric materials market share in the global market, with its application ranging from precision control of industrial machining tools, vehicle acceleration & braking systems, and robotic arms used in various end-use industries.
By End-use Industry
To know how our report can help streamline your business, Speak to Analyst
IT & Telecom Segment to Account for Largest Share Due to Rising Use in Emerging Technologies
Based on end-use industry, the market is segmented into automotive, healthcare, IT & telecom, consumer goods, aerospace & defense, and others.
IT & telecom segment captured the largest market share in 2025. The growth is attributed to introduction of 5G technology in the emerging economies of China and India. The U.S. and Japan are dedicated for improvement in their telecom sector to improve the reach of network signal to every corner of the country. These factors are expected to drive the growth of the IT & Telecom end-use industry in the global market.
The automotive segment is projected to grow at a stable CAGR of 5.9% during the forecast period owing to the requisition of these materials for actuators, fuel injectors, sensors, and braking systems present in the automobile. Furthermore, fuel atomizers, seat belt buzzers, airbag sensors, and tire pressure sensors are a few major automotive parts wherein these materials find application, thus resulting in the automotive industry holding a considerable share of the global market.
PIEZOELECTRIC MATERIALS MARKET REGIONAL OUTLOOK
Geographically, the market is studied across North America, Europe, Asia Pacific, Latin America, and the Middle East & Africa.
Asia Pacific
Asia Pacific Piezoelectric Materials Market Size, 2025 (USD Billion)
To get more information on the regional analysis of this market, Download Free sample
Asia Pacific is the largest consumption region, driven by electronics, consumer devices, telecom components, automotive manufacturing, and industrial equipment. China, Japan, South Korea, Taiwan, India, and Southeast Asia support strong demand for piezoceramics, piezopolymers, resonators, acoustic devices, sensors, buzzers, haptics, and actuators. The region benefits from large-scale manufacturing and rising demand for smartphones, wearables, EVs, appliances, medical devices, and automation systems. Growth is also supported by IoT and self-powered sensor applications.
Japan Piezoelectric Materials Market
Japan’s market to be valued at USD 0.17 billion in 2025, equivalent to around 8.6% of global sales.
China Piezoelectric Materials Market
China’s market reached USD 0.32 billion in 2025, representing roughly 16.2% of global sales.
India Piezoelectric Materials Market
India’s market was valued at USD 0.10 billion in 2025, equivalent to around 5.1% of global sales.
North America
Demand for piezoelectric materials is driven by healthcare, aerospace and defense, industrial automation, and advanced electronics. The U.S. leads regional consumption through applications such as medical ultrasound, sonar, precision sensors, actuators, robotics, semiconductor equipment, and defense electronics. These sectors require high-performance materials with strong reliability and tight specifications. Growth is also supported by IoT sensors, condition monitoring, and energy-harvesting devices, where piezoelectric materials help convert vibration and motion into usable electrical signals.
U.S. Piezoelectric Materials Market
The U.S. market is estimated to be one of the largest globally, with 2025 revenues reached USD 0.43 billion in 2025, accounting for roughly 21.7% of global sales.
Europe
Demand in Europe is mainly supported by automotive electronics, industrial automation, medical technology, renewable energy, and sustainability-led innovation. Piezoelectric materials are used in sensors, actuators, fuel injection systems, vibration monitoring, precision control, and healthcare diagnostics. Environmental regulations are also encouraging interest in lead-free piezoceramics and alternative materials, although PZT remains important for high-performance uses. Growth is further supported by aerospace, structural health monitoring, smart infrastructure, and energy-efficiency initiatives across industrial and mobility applications.
U.K. Piezoelectric Materials Market
The U.K. market reached USD 0.04 billion in 2025, equivalent to around 2.0% of global sales.
Germany Piezoelectric Materials Market
Germany’s market reached USD 0.09 billion in 2025, equivalent to around 4.5% of global sales.
Latin America
Demand in Latin America is driven by automotive piezoelectric components, industrial sensors, mining, oil and gas, healthcare equipment, consumer electronics, and imported electronic devices. Brazil and Mexico are the leading consumption centers, with Mexico supported by automotive and electronics supply chains, while Brazil has broader industrial and healthcare demand. Piezoelectric materials are mainly used in sensors, actuators, buzzers, transducers, ultrasonic devices, and vibration-monitoring systems. Growth remains moderate due to import dependence and limited local advanced material production.
Brazil Piezoelectric Materials Market
Brazil’s market reached USD 0.04 billion in 2025, equivalent to around 2.0% of global sales.
Middle East & Africa
Demand in the Middle East & Africa is mainly supported by oil and gas, mining, industrial monitoring, infrastructure, defense, healthcare equipment, and imported electronics. GCC countries use piezoelectric materials in ultrasonic inspection, flow measurement, vibration sensing, and condition monitoring for energy and infrastructure assets. South Africa contributes through mining and industrial applications, while Israel supports demand through defense, aerospace, medical devices, and advanced sensors. Growth is import-driven but supported by smart infrastructure and energy-sector modernization.
GCC Piezoelectric Materials Market
GCC market reached USD 0.04 billion in 2025, equivalent to around 2.0% of global sales.
Competitive Landscape
Key Industry Players
Focus on Product Development by Key Players to Maintain a Strong Stance in Market
The competitive landscape depicts a fairly consolidated piezoelectric materials market, with a handful of manufacturing companies accounting for a majority share. Key players are investing a large number of resources in the research and development of novel materials and their applications as a course to gain market share.
Furthermore, key players operating in the market have adopted the strategy of capacity expansion and acquisition of smaller enterprises to improve their offering portfolio and services. This trend is projected to positively impact the global market during the forecast period.
LIST OF KEY PIEZOELECTRIC MATERIALS COMPANIES PROFILED
- PI Ceramics GmbH (Germany)
- APC International, Ltd. (U.S.)
- L3Harris Technologies, Inc. (U.S.)
- CeramTec (Germany)
- Arkema (France)
- Solvay (Belgium)
- Sparkler Ceramics (India)
- Piezomechanik GmbH (Germany)
- TDK Corporation (Japan)
- Hong Kong Piezo Co. Ltd. (China)
- Mide Technology (U.S.)
- Meggitt PLC (U.K.)
- HOERBIGER Motion Control GmbH (Germany)
- Piezo Kinetics Inc. (U.S.)
- TRS Technologies, Inc. (U.S.)
KEY INDUSTRY DEVELOPMENTS
- February 2025: CeramTec developed a new bismuth sodium titanate-barium titanate (BNT-BT) based lead-free piezoceramic, and it has great potential for medical applications.
- December 2024: PI Ceramic introduced a new fully automated production line for multilayer technology to accelerate the production of small-scale series and prototype development projects. The company has invested USD 1.08 billion in the development and installation of this new production line with the goal of cutting its time for sample production by half and increasing flexibility in the manufacturing of piezoceramics.
- May 2024: PI Ceramic launched a new product category of piezoceramic composites. The piezoelectric ceramics is embedded in the filling polymers to develop this technology. The new composites offer an alternative to the well-known all-ceramic components with added advantages over all-ceramics. The company offers two different types of filling polymers that include epoxy resins for rigid composites and silicone-free polymers for flexible composite
- November 2023: PI Ceramic introduced a new class of power ultrasonic transducers at the COMPAMED trade fair in Düsseldorf, Germany. This new class of power ultrasonic transducers are known as Langevin and will be used in the preparation of microfluidic samples. These transducers can potentially be used to develop microfluidics catering to numerous applications in the diagnosis and therapy of a wide variety of diseases.
- October 2022: PI Ceramic invested USD 16.24 billion to construct a new building in Lederhose, Germany. This move has increased the company’s production capacity of high-quality piezo components by approximately 50 percent. The company aims to continue to invest in capacity expansion, considering the rise in demand for its products and solutions.
REPORT COVERAGE
The global piezoelectric materials market report provides a detailed analysis of the market and focuses on key aspects such as leading companies, materials, end-use industries, and applications. Besides this, the research report offers insights into the market trends and highlights key industry developments. In addition to the factors above, the report encompasses several factors that have contributed to the growth rate of the market over recent years.
Request for Customization to gain extensive market insights.
Report Scope & Segmentation
| ATTRIBUTE | DETAILS |
| Study Period | 2021-2034 |
| Historical Period | 2021-2024 |
| Base Year | 2025 |
| Estimated Year | 2026 |
| Forecast Period | 2026-2034 |
| Unit | Volume (Million Cubic Centimetres) and Value (USD Billion) |
| Growth Rate | CAGR of 5.9% from 2026 to 2034 |
| Segmentation | By Material, Application, End-use Industry, and Region |
| By Material |
|
| By Application |
|
| By End-use Industry |
|
|
By Region
|
|
Frequently Asked Questions
Fortune Business Insights says that the global market size was USD 1.98 billion in 2025 and is projected to reach USD 3.30 billion by 2034.
Growing at a CAGR of 5.9%, the market will exhibit steady growth during the forecast period (2026-2034).
The IT & telecom segment is the leading end-use industry in the market.
Considerable investments by countries such as India, China, and the U.S. in space exploration activities to improve the strength of their military are a key factor in boosting this market's growth.
Asia Pacific held the highest market share in 2025.
The focus of automotive and electronics manufacturing companies on automation of manufacturing plants to reduce the occurrence of product failures, coupled with high demand for consumer electronics are factors expected to enhance the adoption of these materials.


- 2021-2034
- 2025
- 2021-2024
- 265
-
(Offer valid till 30th Sep 2026)
Get 30-60 hrs Free Customization
Expand Regional and Country Coverage, Segments Analysis, Company Profiles, Competitive Benchmarking, and End-user Insights.


















Related Reports
-
US +1 833 909 2966 ( Toll Free )
-
Get In Touch With Us