 Download Free Sample



Get a Quote
Receive a tailored pricing based on your needs.
- Choose license type
- Multiple user options
- Custom scope & coverage
- Fast turnaround
"Designing Growth Strategies is in our DNA"
 Listen to Audio Version
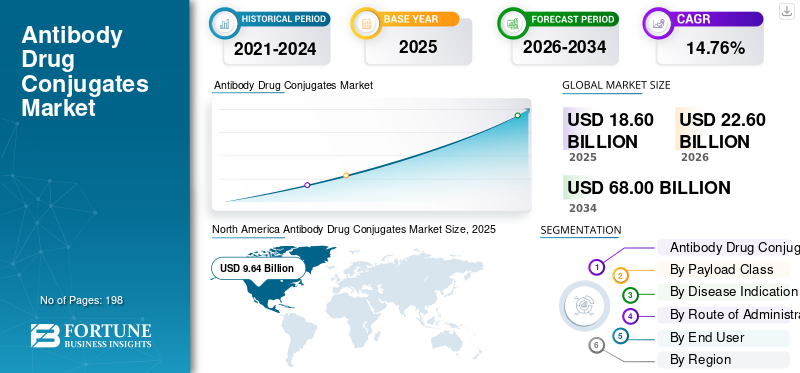
The global antibody-drug conjugates market size was valued at USD 18.60 billion in 2025 and is projected to grow from USD 22.60 billion in 2026 to USD 68.00 billion by 2034, exhibiting a CAGR of 14.76% during the forecast period. North America dominated the global market with a market share of 51.83% in 2025.
Antibody Drug Conjugates (ADCs) represent targeted cancer treatments that merge the specificity of monoclonal antibodies with the lethal efficacy of highly potent cytotoxic agents. The market is expanding as cancer treatments increasingly shift toward more precise, individualized therapies that enhance treatment efficacy while minimizing unnecessary harm to healthy tissues.
Growing approvals in solid tumors and blood cancers, broader application of ADCs in earlier treatment lines, and robust clinical advancement efforts by leading pharmaceutical firms are facilitating greater adoption. The global product demand is also increasing as ADC platforms advance, with enhanced linker stability, more efficient payload types such as topoisomerase I inhibitors and microtubule inhibitors, and a wider range of tumor targets.
Key players operating in the global market include Daiichi Sankyo Company, Limited, AstraZeneca, Pfizer Inc., Astellas Pharma Inc., Gilead Sciences, Inc., and F. Hoffmann-La Roche Ltd. Their strategies include new product launches, regulatory approvals, co-development partnerships, acquisitions, and investment in next-generation ADC platforms to strengthen their presence in high-growth cancer treatment areas.
The Structural Antibody-Drug Conjugates (ADCs) market is shaped by advances in targeted oncology, antibody engineering, linker chemistry, and potent cytotoxic payloads. Commercial demand is concentrated in approved therapies, while clinical development continues to expand across tumor types and treatment settings. Market performance depends on clinical benefit, biomarker prevalence, treatment sequencing, and the ability to manage toxicity.
Human epidermal growth factor receptor 2 (HER2)-directed ADCs represent an established product family, supported by therapies used across selected breast and other cancers. Trophoblast cell-surface antigen 2 (TROP2)-directed products have also gained clinical relevance in breast and lung cancer. Nectin-4-directed ADCs serve an important role in urothelial cancer, while CD30-directed ADCs remain relevant in selected lymphomas.
Payload selection influences efficacy and safety. Topoisomerase I inhibitors have gained prominence in newer ADC designs, while microtubule inhibitors remain important in established products. Linker stability, drug-to-antibody ratio, target expression, internalization, and payload release collectively affect therapeutic performance. These factors shape product differentiation and influence development costs.
Market growth is supported by clinical evidence, expanding treatment indications, and pharmaceutical investment in targeted therapies. However, the category faces substantial constraints. Adverse events, resistance, manufacturing complexity, high treatment costs, and competition from other oncology modalities can limit adoption. ADCs also require specialized production controls because antibody, linker, and payload components must function as an integrated system.
Download Free sample to learn more about this report.
 Market Size & Forecast
 Market Share
 Key Regional Highlights
North America
North America led the market with a value of USD 9.64 billion in 2025.
Asia Pacific
Asia Pacific is expected to reach USD 4.74 billion by 2026, driven by expanding oncology care access.
Europe
Europe is projected to grow at a CAGR of 13.95% during the forecast period.
U.S.
The market is projected to reach USD 10.66 billion in 2026, accounting for 47.2% of global revenue.
Japan
The market is estimated at USD 1.54 billion in 2026, representing 6.8% of global revenue.
Read More

Focus on Development of Next-Generation Antibody Drug Conjugates is a Significant Trend Observed in Market
The advancement of next-generation antibody-drug conjugates is a significant trend in the global ADC market, as firms aim to enhance the safety, efficacy, and tumor targeting of current ADCs. Previous ADCs demonstrated significant clinical benefits, but issues such as off-target toxicity, unstable linkers, limited payload delivery, and resistance in certain patients underscored the need for improved ADC designs. Consequently, organizations are developing ADCs with more robust linkers, site-specific conjugation, higher drug-to-antibody ratios, innovative payloads, dual-payload structures, and enhanced tumor-targeting mechanisms.
This movement is aiding the expansion of ADC applications beyond conventional targets such as HER2 and CD30 to emerging solid tumor targets, including TROP2, CLDN6/9, CDH17, VEGF, and various tumor-associated antigens. It is also enabling companies to place ADCs earlier in the treatment line and in challenging cancers where standard chemotherapy offers little advantage. Consequently, the advancement of next-generation ADCs is anticipated to bolster the market's long-term growth by improving treatment outcomes, expanding cancer coverage, and creating new business opportunities for both major pharmaceutical and biotech firms. These factors are supporting the overall global antibody drug conjugates market growth.
Download Free sample to learn more about this report.
Increasing Adoption of Targeted Cancer Therapies is Driving Market Growth
The increasing adoption of targeted cancer therapies is a major driver of the global market, as cancer treatment is moving away from broad chemotherapy toward medicines that target specific tumor markers. ADCs fit this shift well, as they combine an antibody that recognizes a cancer target with a potent payload that kills cancer cells more selectively. This helps oncologists use a more personalized treatment approach based on biomarkers such as HER2, TROP2, Nectin-4, CD30, and folate receptor alpha.
As biomarker testing becomes more common in oncology, more patients can be matched with ADC therapies that are suitable for their tumor profile. This is increasing ADC use across breast cancer, urothelial cancer, lung cancer, lymphoma, ovarian cancer, and gastric cancer. The rising number of approvals and label expansions also shows that ADCs are moving into broader patient groups and earlier treatment settings. Therefore, growing demand for targeted cancer care is directly supporting higher adoption of ADC drugs and strengthening market growth.
Demand for antibody-drug conjugates (ADCs) is supported by oncology pathways increasingly guided by tumor biology, biomarker status, and prior therapy. These medicines combine target recognition with payload delivery, creating options for patients whose disease has progressed after established treatments.
Approvals and label expansions can widen eligible groups, while trial results shape treatment sequencing and physician confidence. In January 2025, the United States Food and Drug Administration approved the TROP2-directed ADC datopotamab deruxtecan for a defined metastatic breast cancer population, illustrating continued expansion of targeted options.
FDA
HER2-directed therapies benefit from established testing pathways and multiple treatment settings. Nectin-4 targeting has a role in advanced urothelial cancer, while CD30-directed treatment remains important in selected lymphomas. These differences create distinct commercial demand profiles.
Advances in linker chemistry, antibody engineering, and payload design support development. Better control of drug release and target engagement may improve the balance between efficacy and toxicity. Pharmaceutical companies are investing in these capabilities to differentiate products and extend therapeutic reach.
High Research and Development Costs to Limit Market Growth
Elevated research and development expenses pose a limitation for the global market, as ADC development is more complex than that of many standard cancer medications. Businesses must enhance the antibody, linker, payload, drug-to-antibody ratio, stability, toxicity profile, and production process before an ADC advances effectively through clinical trials. This boosts expenditures in discovery, preclinical research, clinical development, analytical testing, and specialized production.
The risk remains considerable as numerous ADC candidates might fail due to safety concerns, limited effectiveness, or challenges in demonstrating distinct advantages over current treatments. Consequently, smaller ADC developers might have to cut back on research efforts, postpone programs, find partners, or focus solely on the most promising assets. This may hinder pipeline growth and slow the pace at which new ADCs enter the market. Consequently, while ADCs present significant commercial opportunities, substantial R&D expenses and developmental risks may limit market expansion.
The Structural Antibody-Drug Conjugates (ADCs) market faces scientific, manufacturing, and commercial constraints. Target expression can vary within and between tumors, limiting the consistency of treatment response. Antigen loss, reduced cellular uptake, and altered intracellular processing can also contribute to resistance, even when a therapy initially produces clinical benefit.
Toxicity remains a major development challenge. Adverse effects can arise from target expression in healthy tissue, unintended payload exposure, or the biological properties of the cytotoxic agent. These risks influence dose selection, treatment duration, patient monitoring, and the range of patients who can receive therapy.
Manufacturing complexity adds further pressure. Each ADC combines an antibody, linker, and potent payload, requiring control of conjugation, drug-to-antibody ratio, impurities, stability, and batch consistency. Specialized containment and handling procedures increase production demands and limit the number of facilities able to manufacture these products reliably.
Rising Investments in Oncology Drug Development to Offer Market Growth Opportunities
Increasing funding in oncology drug development is generating a significant opportunity for the global market, with ADCs now regarded as one of the most appealing sectors in targeted cancer therapy. Major pharmaceutical corporations and biotechnology companies are boosting investments in ADC development due to the potential of these treatments to target high-priority cancers such as breast cancer, lung cancer, ovarian cancer, gastric cancer, and urothelial cancer. This funding is assisting firms in creating new targets, enhanced payloads, advanced linker technologies, and superior manufacturing capabilities.
It is additionally fostering increased licensing agreements, acquisitions, and strategic alliances between global pharmaceutical companies and biotech firms centered on ADCs. With increased investment in ADC research, companies can expedite the progression of candidates into clinical trials and examine them across a broader range of tumor types and treatment lines. This presents a significant business prospect as effective ADCs can achieve high pricing, extensive oncology application, and extended lifecycle growth via additional indications.
The Structural Antibody-Drug Conjugates (ADCs) market offers opportunities in tumors where existing therapies provide limited benefit or resistance develops. New targets may expand treatment options, but selection must balance tumor expression, healthy-tissue exposure, internalization, and clinical relevance.
Linker and conjugation technologies create an opportunity. Site-specific conjugation and improved linker stability may produce consistent drug-to-antibody ratios and reduce unintended payload release. These approaches could improve differentiation if studies confirm a therapeutic window and manufacturing remains scalable.
Payload diversification may help address resistance and crowded target classes. Alternative mechanisms, dual-payload constructs, and bispecific formats are under investigation. Their value depends on whether added complexity improves efficacy or tolerability rather than increasing development cost.
Limited Availability of Specialized Production Facilities Poses a Prominent Challenge to Market Growth
The limited availability of specialized production facilities poses a significant challenge for the global market, as ADC manufacturing requires highly specialized skills that are absent in conventional biologics or chemotherapy plants. Producing ADCs necessitates specialized knowledge in monoclonal antibody production, managing highly potent payloads, linker chemistry, bioconjugation, aseptic filling, containment, and analytical testing. Due to the high potency of cytotoxic payloads, facilities must adhere to stringent safety and containment regulations, leading to increased capital investment and limiting the number of qualified manufacturers. This may cause bottlenecks as additional ADC candidates transition from clinical trials to commercial production. Smaller biotech firms may face extended timelines or higher outsourcing costs due to their reliance on a limited number of ADC-centric CDMOs. With increasing demand, businesses are enhancing capacity, yet constructing and qualifying new facilities requires years. Consequently, the lack of dedicated ADC manufacturing facilities may hinder commercialization and pose a market obstacle.
The Structural Antibody-Drug Conjugates (ADCs) market is segmented by target family, payload class, disease indication, route of administration, and end user. Each category reflects a different aspect of commercial value: target biology shapes patient eligibility, payload design influences therapeutic performance, and disease indication determines clinical positioning. Administration and treatment setting affect infrastructure requirements, access, and purchasing behavior.
Strong Commercial Adoption of HER2-directed ADCs Boosted Segment Dominance
In terms of product/target family, the market is divided into HER2-directed ADCs, Nectin-4-directed ADCs, TROP2-directed ADCs, CD30-directed ADCs, CD79b-directed ADCs, Folate Receptor Alpha-directed ADCs, and others.
HER2-Directed ADCs
The HER2-directed ADCs segment led the global antibody-drug conjugates market share in 2025. This is attributed to the significant commercial success and broader clinical application of products such as Enhertu and Kadcyla in HER2-positive and HER2-low cancers. The segment's dominance is due to the significant disease burden of breast cancer, gastric cancer, and other solid tumors that express HER2, resulting in a sizable pool of patients eligible for HER2-targeted therapy.
Human epidermal growth factor receptor 2 (HER2)-directed ADCs represent an established segment, supported by clinical use across selected breast cancers and other HER2-expressing malignancies. Their commercial position benefits from established testing pathways, accumulated clinical experience, and treatment guidelines that define eligible patient populations.
The segment is not biologically uniform. HER2 expression levels, tumor heterogeneity, prior treatments, and disease setting influence therapeutic selection. Newer approaches have expanded attention beyond tumors with the highest expression, although eligibility and expected benefit remain product-specific. Clinical evidence must distinguish treatment effects across different expression categories and tumor types.
Moreover, HER2-targeted ADCs have seen wider acceptance due to their demonstrated effectiveness in patients with few prior targeted therapies, particularly in metastatic disease scenarios. The ongoing growth of HER2 testing, rising label approvals, and the shift of these medications to earlier treatment stages are expected to drive the segment’s growth over the projected timeframe.
The folate receptor alpha-directed ADCs segment is anticipated to rise with a CAGR of 27.09% over the forecast period.
Nectin-4-Directed ADCs
Nectin-4-directed ADCs occupy a defined position in urothelial cancer treatment. Enfortumab vedotin combines a Nectin-4-targeting antibody with a microtubule-disrupting payload. Its clinical role has established this target as commercially relevant, while combination regimens have broadened its treatment context.
Demand depends on disease incidence, diagnosis, treatment eligibility, prior therapy, and reimbursement. Urothelial cancer care often involves sequential treatments, making the placement of an ADC within the treatment pathway commercially important. Clinical evidence and evolving standards can shift use across treatment settings.
Target expression and safety remain central considerations. Nectin-4 biology supports targeted delivery, but adverse effects can still limit treatment intensity or duration. Physicians weigh clinical benefit, patient comorbidities, and the need for monitoring.
The segment's competitive position also depends on the availability of alternative therapies. Immunotherapies, platinum-based chemotherapy, and other targeted treatments shape treatment decisions. Future growth may come from combination studies and revised treatment sequencing, subject to regulatory decisions and clinical results.
TROP2-Directed ADCs
Trophoblast cell-surface antigen 2 (TROP2)-directed ADCs are an important development area in solid tumors, especially breast and lung cancers. Their commercial appeal reflects target prevalence in selected tumor types and the potential to deliver cytotoxic payloads to malignant cells.
Products differ in linker chemistry, payload characteristics, drug-to-antibody ratio, and clinical evidence. These distinctions affect exposure, tolerability, and treatment outcomes. Developers must show advantages within specific disease settings rather than assume that targeting the same antigen produces comparable performance.
The segment faces competition from established therapies and other ADCs. Market growth depends on evidence supporting use in defined patient groups, including patients previously treated with chemotherapy or other systemic agents. Biomarker requirements may vary by product and indication.
Manufacturers are evaluating combination regimens, earlier treatment lines, and additional tumor types. These strategies may expand commercial reach, but each creates new clinical and regulatory requirements. Market share will depend on comparative outcomes, tolerability, treatment duration, and access.
CD30-Directed ADCs
CD30-directed ADCs are associated primarily with selected lymphomas, including Hodgkin lymphoma and certain systemic anaplastic large-cell lymphomas. Brentuximab vedotin combines CD30 targeting with a microtubule inhibitor payload. Its established clinical use provides a distinct commercial profile from ADCs focused on solid tumors.
Demand is linked to lymphoma incidence, treatment eligibility, clinical guidelines, and the position of the therapy within combination regimens. Treatment decisions depend on disease subtype, prior treatment, response, and patient-specific safety considerations.
Because the target is associated with defined hematological malignancies, the addressable population differs from that of broadly expressed solid-tumor targets. Growth depends more on indication-specific evidence and treatment sequencing than on expansion across unrelated cancers.
To know how our report can help streamline your business, Speak to Analyst
Established Clinical Use of Microtubule Inhibitor ADCs Supported Segment Dominance
Based on payload class, the market is classified into topoisomerase I inhibitor ADCs, microtubule inhibitor ADCs, maytansinoid ADCs, DNA-damaging ADCs, and others.
Microtubule Inhibitor ADCs
The microtubule inhibitor ADCs segment captured the leading position in the global market in 2025. This is owing to the early approval and strong commercial use of ADCs carrying auristatin- and maytansinoid-based payloads. The segment's dominance stems from the widespread use of products such as Adcetris, Padcev, Kadcyla, Polivy, and Tivdak in lymphoma, urothelial cancer, breast cancer, cervical cancer, and other oncology indications. These payloads are commonly used because they inhibit cancer cell division once introduced into tumor cells, making them effective against rapidly growing cancers.
Additionally, the sector has gained from recognized physician knowledge, broader practical application, and several approved products for both solid tumors and hematologic cancers. The ongoing application of microtubule inhibitor ADCs in combination therapies is anticipated to promote consistent uptake of these medications in the marketplace. Furthermore, the segment is set to hold 36.3% share in 2026.
Topoisomerase I Inhibitor ADCs
The topoisomerase I inhibitor ADCs segment is anticipated to rise with a CAGR of 21.70% over the forecast period. Topoisomerase I inhibitor ADCs have gained prominence in solid-tumor development. These payloads interfere with DNA replication and can cause cell death after intracellular release. Their use has the development of ADCs targeting HER2, TROP2, and other tumor-associated antigens.supported
Commercial performance depends on the complete construct. Linker stability, drug loading, antibody distribution, internalization, and payload release all influence therapeutic exposure. Payload potency alone cannot establish clinical advantage because systemic exposure and off-target effects can constrain dosing.
This class also raises important safety considerations. Interstitial lung disease, myelosuppression, gastrointestinal effects, and other adverse events may require monitoring, depending on the specific product. Risk profiles vary across constructs and cannot be generalized solely from payload class.
Large Patient Pool and Wider ADC Use in Breast Cancer Led to Segment Dominance
Based on disease indication, the market is classified into breast cancer, urothelial cancer, lymphoma, lung cancer, ovarian cancer, gastric & gastroesophageal cancer, and others.
The breast cancer segment dominated the market share in 2025. This is due to the high number of patients eligible for ADC-based treatment and the strong use of approved ADCs in metastatic settings. Additionally, factors such as the broad adoption of ADCs, growing use of biomarker testing, rising preference for targeted therapies, and ongoing label expansions are supporting higher ADC adoption in breast cancer. Furthermore, the segment is set to hold 39.0% share in 2026.
The ovarian cancer segment is anticipated to rise with a CAGR of 28.76% over the forecast period.
Hospital-based Infusion Use Fostered Intravenous Segment Dominance
On the basis of route of administration, the market is divided into intravenous and others.
In 2025, the market share was primarily led by the intravenous segment. This is owing to the fact that almost all approved antibody drug conjugates are given through IV infusion under medical supervision. The segment's dominance is linked to the intricate characteristics of ADCs, which integrate monoclonal antibodies with potent payloads and require careful dosing, dilution, infusion monitoring, and management of potential infusion-related reactions. IV administration enables oncologists to closely observe patients for toxicities such as neutropenia, neuropathy, ocular events, and liver-related side effects. Furthermore, the segment is set to hold 99.7% share in 2026.
The others segment is anticipated to rise with a CAGR of 26.19% over the forecast period.
Hospitals-led market due to Availability of Advanced Oncology Care Infrastructure
Based on end user, the market is segmented into hospitals, cancer specialty centers, academic & research hospitals, ambulatory infusion centers, and others.
The hospitals segment dominated the market share in 2025. The segment's dominance stems from the fact that most ADCs are administered via intravenous infusion, which requires skilled oncology teams, infusion centers, dosage monitoring, and management of potential side effects. In addition, hospitals typically have resources for diagnostic testing, oncology experts, pharmacy preparation units, and emergency care, positioning them as the preferred locations for complex cancer treatments. Numerous patients undergoing ADCs additionally require routine imaging, blood analyses, and toxicity assessments, typically handled by hospital oncology departments. Furthermore, the segment is set to hold 51.9% share in 2026.
In addition, ambulatory infusion centers are projected to grow at a 19.07% CAGR during the forecast period.
By geography, the market is divided into Latin America, Asia Pacific, Europe, North America, and the Middle East & Africa.
North America Antibody Drug Conjugates Market Size, 2025 (USD Billion)
To get more information on the regional analysis of this market, Download Free sample
North America held the largest share of the global market, attaining USD 7.65 billion in 2024. In 2025, the region continued its dominance, with USD 9.64 billion. North America is expanding due to strong adoption of advanced oncology therapies, high cancer treatment spending, and early availability of approved ADCs.
The U.S. market led the North American region and is projected to be approximately USD 10.66 billion in 2026, representing about 47.2% of the global market.
The market in Europe is set to grow at a CAGR of 13.95% during the forecast period. Europe is growing steadily due to rising adoption of targeted cancer therapies, strong reimbursement systems in major countries, and increasing use of ADCs in breast cancer, lymphoma, and urothelial cancer.
The U.K. market in 2026 is estimated at around USD 0.69 billion, representing roughly 3.0% of global revenues.
The German market size is projected to reach approximately USD 1.11 billion in 2026, equivalent to around 4.9% of global sales.
The Asia Pacific market size is expected to reach a valuation of USD 4.74 billion by 2026. Asia Pacific is expected to grow owing to the factors such as show strong growth due to a large cancer patient pool, improving access to oncology care, and rising healthcare spending in China, Japan, South Korea, Australia, and India.
The market in Japan in 2026 is estimated at around USD 1.54 billion, accounting for roughly 6.8% of global revenues.
The market in China is projected to reach USD 1.54 billion in 2026, representing roughly 6.8% of global sales.
The Indian market in 2026 is estimated at around USD 0.25 billion, accounting for roughly 1.1% of global revenues.
The growth in the Latin America and Middle East & Africa regions is anticipated to be slower over the forecast period. The growth of the market is driven by rising cancer burden, growing private healthcare coverage, and increasing use of specialty cancer medicines are supporting ADC demand. The Latin America market in 2026 is estimated at around USD 0.87 billion.
In the Middle East & Africa region, the GCC market is projected to reach approximately USD 0.21 billion in 2026, representing about 0.9% of global revenues.
Strong ADC Product Portfolio and Strategic Collaborations to Contribute to Players’ Market Dominance
The global antibody drug conjugates market features a semi-consolidated competitive landscape, with leading pharmaceutical companies such as Daiichi Sankyo Company, Limited, AstraZeneca plc, Pfizer Inc., Gilead Sciences, Inc., and F. Hoffmann-La Roche Ltd dominating the market. These players are focusing on regulatory label expansions, co-development agreements, acquisitions, and the development of next-generation ADC pipelines to strengthen their market positions across breast cancer, urothelial cancer, lymphoma, ovarian cancer, and other solid tumors.
Other significant participants include AbbVie Inc., GSK plc, RemeGen, Astellas Pharma Inc., and Jiangsu Hengrui Pharmaceuticals Co., Ltd., among others. These companies are focusing on ADC product launches, regional commercialization, clinical trial expansion, and strategic partnerships to capture growth opportunities in the global market.
The global antibody drug conjugates market analysis includes a thorough evaluation of the market size and forecasts for every segment highlighted in the report. It offers insights into the market dynamics and trends expected to drive the market throughout the forecast period. It provides an understanding of essential factors, including technological progress, product innovations, pipeline analysis, the regulatory environment, and the launch of new products. Additionally, it details partnerships, mergers & acquisitions, as well as key developments in the industry within the market. The global market forecast report also provides an in-depth competitive landscape, including information on market share and profiles of key active players.
Request for Customization to gain extensive market insights.
| ATTRIBUTE | DETAILS |
| Study Period | 2021-2034 |
| Base Year | 2025 |
| Estimated Year | 2026 |
| Forecast Period | 2026-2034 |
| Historical Period | 2021-2024 |
| Growth Rate | CAGR of 14.76% from 2026 to 2034 |
| Unit | Value (USD Billion) |
| Segmentation | By Product/Target Family, Payload Class, Disease Indication, Route of Administration, End User, and Region |
| By Product/Target Family |
|
| By Payload Class |
|
| By Disease Indication |
|
| By Route of Administration |
|
| By End User |
|
| By Region |
|
According to Fortune Business Insights, the global market value stood at USD 18.60 billion in 2025 and is projected to reach USD 68.00 billion by 2034.
In 2025, the market value in North America stood at USD 9.64 billion.
The market is expected to exhibit a CAGR of 14.76% during the forecast period of 2026-2034.
By product/target family, the HER2-directed ADCs segment is expected to lead the market.
Increasing approvals across solid tumors and hematologic cancers, expanding use of ADCs in earlier lines of therapy, and strong clinical development activity by major pharmaceutical companies are primarily driving market expansion.
DAIICHI SANKYO COMPANY, LIMITED, AstraZeneca, Pfizer Inc., Gilead Sciences, Inc., and F. Hoffmann-La Roche Ltd are some of the prominent players in the global market.
North America dominated the market in 2025.

Get 30-60 hrs Free Customization
Expand Regional and Country Coverage, Segments Analysis, Company Profiles, Competitive Benchmarking, and End-user Insights.













.webp)






Get In Touch With Us
US +1 833 909 2966 ( Toll Free )
Receive a tailored pricing based on your needs.
Discuss your questions with our industry experts.
Have questions? Get quick answers before you purchase.

